Listed in Singapore · Wireless IoT & telecoms infrastructure
SGX: NXR · Information cut-off 24 August 2026
Investor snapshot
Business model
iWOW designs and operates wireless monitoring, metering and elder-care systems and also installs telecommunications infrastructure.
Latest figures
FY2026 produced S$5.372m of operating cash and S$11.471m of closing cash despite a statutory loss, but contracted acquisition consideration of S$13.6m exceeded that balance-sheet cash and a completed placement raised about S$15.0m gross.
Main risk
The central risk is that acquisition payments, new share issuance and receivable timing mask the economics of the operating businesses.
Next proof
The next test is the next filing's post-acquisition segment contribution, purchase-price allocation and cash bridge after the placement.
No public rating. Information cutoff 24 August 2026, 22:30 SGT. The latest reported period is FY2026 (the year to 31 March 2026), audited, with the annual report signed on 14 July 2026. Two material events and the later option exercise fall after that balance-sheet date and are recorded below. The issuer announcement tape was re-swept through the cutoff. Every number here is as reported in a primary filing or computed from one, with the computation shown.
Evidence balance
The live questionWill project work convert into invoiced cash fast enough to fund contracted acquisition consideration without further share issuance?It matters now because FY2026 ended with S$11.5m of cash against S$13.6m of contracted consideration already falling due, and 66% of the receivable book cannot yet be invoiced.
What improved
FY2026 revenue rose 19% to S$41.3m and operating profit 150% to S$3.59m; Wireless Engineering Solutions margin ran 15.2%, 8.7% and 20.0% across FY2024 to FY2026, and the audited cash-flow statement records S$5.372m of operating cash flow, leaving S$2.274m of post-lease free cash flow.
What became more demanding
Against that, consideration already contracted and falling due totals S$13.6m, S$2.2m more than the S$11.5m of cash held at the balance-sheet date, and invoiced trade receivables are only S$6.6m against S$13.9m of contract assets, 66% of the book, that cannot yet be billed.
Strongest alternative explanation
The gap could be timing rather than strain: contract assets are revenue already recognised on satisfied performance obligations awaiting a billing milestone, the earn-out charge is a measure of the acquisition succeeding, and the completed placement raising about S$15.0m gross would be consistent with the obligations being funded without pressure on trading cash.
The decisive missing fact
The next filing's post-acquisition segment contribution, purchase-price allocation and cash bridge after the placement would settle it; the purchase price allocation had not been finalised when the accounts were authorised, The Gentle Group's revenue is still undisclosed, and the earn-out calculation has never been published.
Drawn from the evidence on this page: the improvement, the constraint, the benign reading and the fact that would settle it. It states no view on the shares.
About the private research record
Also on file for this company, behind the private view 🔒 (author-only): a current 24 August monitoring note and understanding sheet. The verified 20 August workbook and older PDF/deck are archived because the supported workbook editor was unavailable for the latest share-count update. All conclusions remain private and do not appear on this public evidence page.
On this page
Business anatomy · operations, customers and cash
Wireless engineering connects devices, networks and monitoring programmes
iWOW combines hardware, systems integration and software platforms, but enterprise installations and connected-device programmes are distinct customer outcomes.
Read each card by investor role: business line, operating step, customer outcome or cash conversion.
Customer needMonitoring gap
Define the wireless job
What happensA utility, public agency or enterprise specifies a connected-device or communications problem.
Commercial triggerThe customer funds a project, programme or service requirement.
Business lineConnected devices
Design the field hardware
What happensSensors, radio modules and connectivity are integrated into meters, alerts, trackers and other devices.
How it earnsHardware and programme delivery contribute project revenue.
Business lineSystems integration
Install the network
What happensiWOW engineers and integrates radios, communications equipment and the surrounding infrastructure.
How it earnsEnterprise and infrastructure customers pay for installed systems and support.
Recurring servicePlatform
Turn signals into a service
What happensConnected devices send data into monitoring platforms used by the customer’s operating team.
Revenue driverPlatform, monitoring and service elements can extend revenue beyond installation.
Original SMID Research comic. AI-assisted, analyst-directed monochrome artwork depicts the evidenced operating steps of iWOW Technology; deterministic captions and dated mix figures state the economics using issuer disclosures available to 2026-08-24. The drawings are representative—not issuer artwork, an exact product or site design, a statement of scale, or a company forecast.
Investor translation
What matters after the operating picture
Four questions connect the business model to cash and balance-sheet risk. This is a factual reading aid, not a valuation or recommendation.
Value lever
Higher recurring service contribution and profitable conversion of connected-device programs.
Cash bottleneck
Hardware, project work and receivables are funded before installation acceptance and service cash.
Balance-sheet pressure
Accessible cash and committed lines fall short of project working capital and acquisition obligations.
Next proof
Recurring-service mix, project collections, gross margin and legal-entity liquidity.
Text version of this comic
Customer need · Define the wireless job A utility, public agency or enterprise specifies a connected-device or communications problem. Commercial trigger: The customer funds a project, programme or service requirement.
Business line · Design the field hardware Sensors, radio modules and connectivity are integrated into meters, alerts, trackers and other devices. How it earns: Hardware and programme delivery contribute project revenue.
Business line · Install the network iWOW engineers and integrates radios, communications equipment and the surrounding infrastructure. How it earns: Enterprise and infrastructure customers pay for installed systems and support.
Recurring service · Turn signals into a service Connected devices send data into monitoring platforms used by the customer’s operating team. Revenue driver: Platform, monitoring and service elements can extend revenue beyond installation.
Why the loss is not the earnings
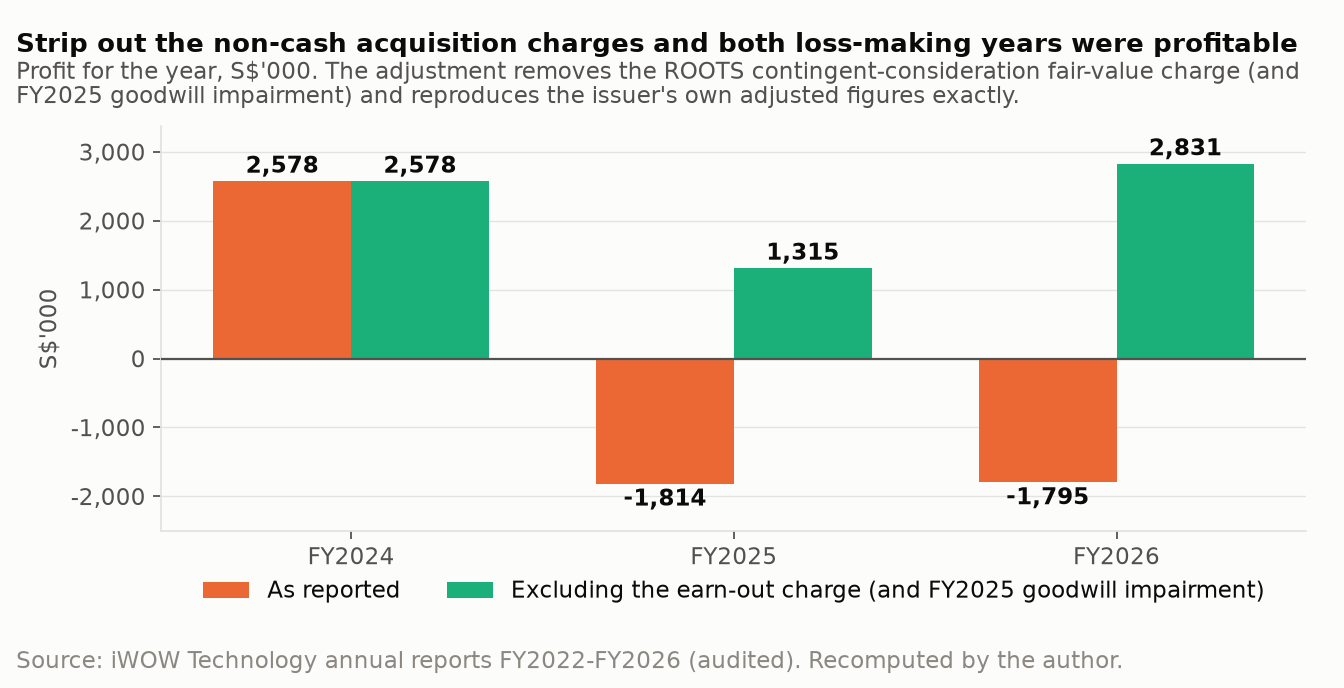
In FY2026 iWOW reported revenue of S$41.3m, up 19%, and an operating profit of S$3.59m, up 150%. It also reported a loss for the year of S$1.80m. One line explains the whole gap.
In the year to 31 March 2023 the company acquired ROOTS Communications Pte Ltd and its Malaysian subsidiary. The price was not fixed: it was set at six times the audited average annual net profit after tax of the ROOTS group over the three years from 1 April 2023 to 31 March 2026, capped at S$18.0m. Under the applicable accounting standard, changes in the fair value of that contingent consideration after the measurement period go through the income statement rather than adjusting goodwill.
ROOTS outperformed. The liability was first carried at S$1.9m; it finished at S$9.526m. The increases — S$3.0m in FY2025 and S$4.626m in FY2026 — were charged to profit. Both loss-making years are that charge.
Removing the contingent-consideration charge (and the FY2025 goodwill impairment) reproduces the issuer’s own adjusted figures of S$1,315k for FY2025 and S$2,831k for FY2026 exactly.
Two things follow, and both are matters of record rather than interpretation. The charge is a measure of the acquisition succeeding. On 19 August 2026 the company fixed total consideration at S$17,432,106, or 96.8% of the S$18.0m cap, based on audited average annual net profit after tax of S$2,905,351 for the three-year measurement period. The post-balance-sheet announcement is the final contractual amount; it supersedes the FY2026 balance-sheet estimate.
A note on timing. The FY2026 accounts carried a S$9.526m contingent-consideration estimate at 31 March. The 19 August announcement subsequently determined the final second tranche at S$9,332,106. The difference is a post-balance-sheet finalisation, not a reason to keep using the earlier estimate.
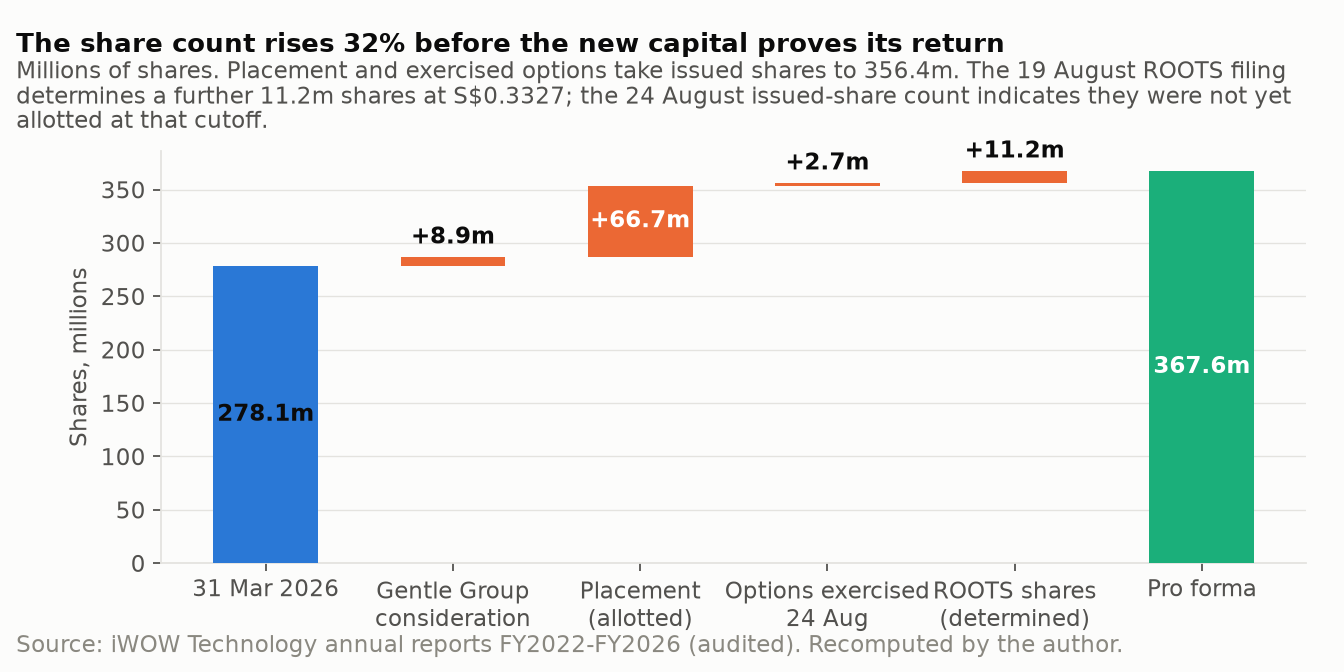
What does not end with the charge. The final second tranche is S$5,599,264 in cash and S$3,732,842 in 11,219,845 new shares at S$0.3327. The shares were determined on 19 August but were not included in the issued-share count reported on 24 August.
The company that listed in 2022 no longer exists
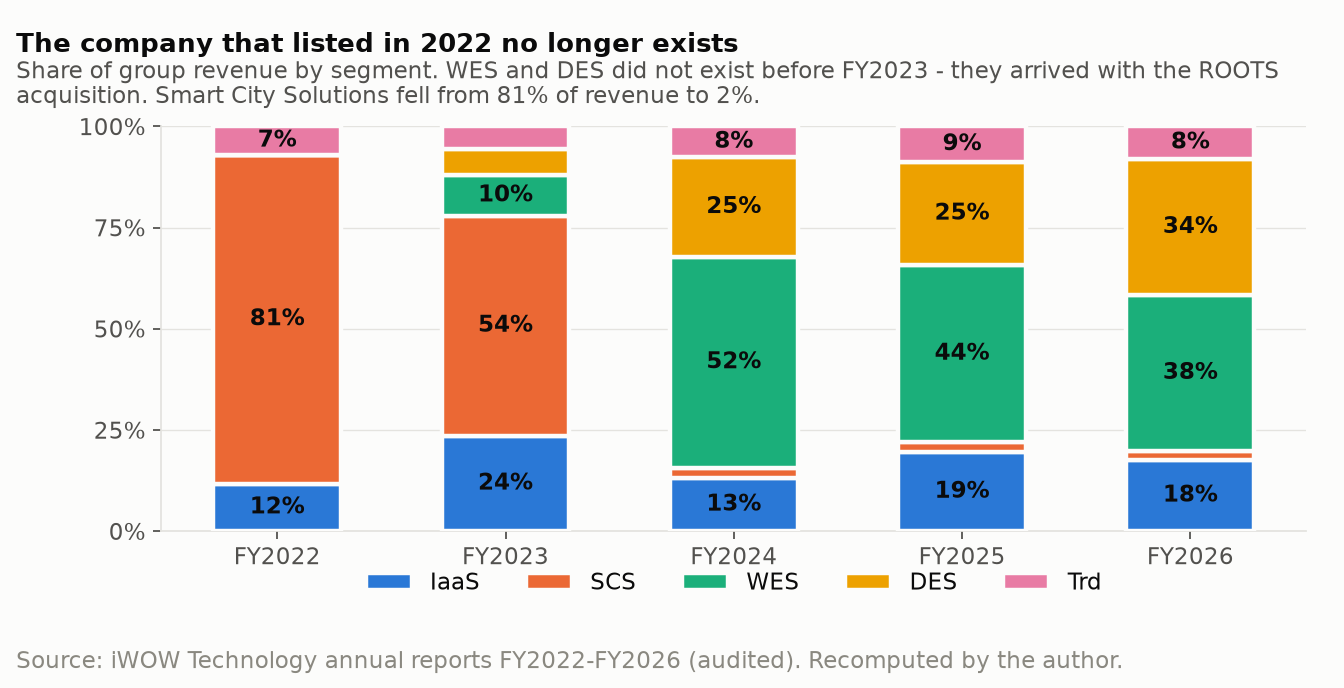
This is the single most important structural fact on this page, and it is the one most likely to be missed by anyone reading a multi-year growth rate.
Smart City Solutions was 81% of revenue in FY2022 and 2% in FY2026. Wireless Engineering Solutions and Datacomm & Enterprise Solutions have no figures before FY2023 because they did not exist — they arrived with ROOTS.
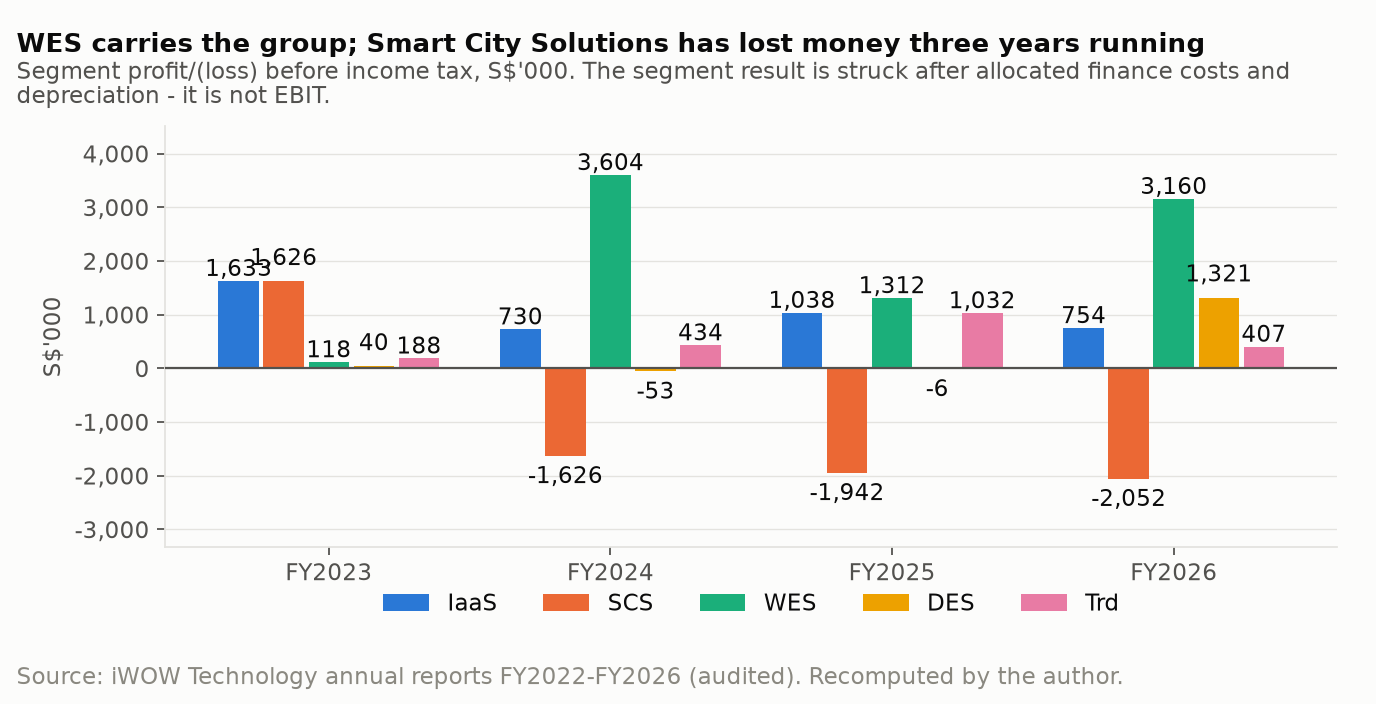
In FY2022 the Smart City Solutions segment produced S$28.1m of revenue and S$3.5m of profit before tax. In FY2026 it produced S$0.97m of revenue and a loss of S$2.05m — its third consecutive and widest loss. Over the same span the two segments acquired with ROOTS grew from nothing to S$29.7m, 72% of revenue.
Any series plotted across FY2022 and FY2023 therefore crosses a perimeter break. A revenue compound growth rate through it describes two different companies joined together.
The as-filed record
S$’000
FY2021
FY2022
FY2023
FY2024R
FY2025
FY2026
Revenue
26,422
34,532
25,569
45,622
34,581
41,256
Operating profit
4,071
4,372
3,898
3,135
1,434
3,590
Operating margin
15.4%
12.7%
15.2%
6.9%
4.1%
8.7%
Earn-out fair-value charge
—
—
—
—
(3,000)
(4,626)
Profit / (loss) for the year
3,715
3,866
3,558
2,578
(1,814)
(1,795)
Operating cash flow
4,633
5,696
(394)
(1,328)
2,020
5,372
Cash and equivalents
4,656
4,797
9,856
6,327
4,415
11,471
R FY2024 is the restated basis. See the restatement section below.
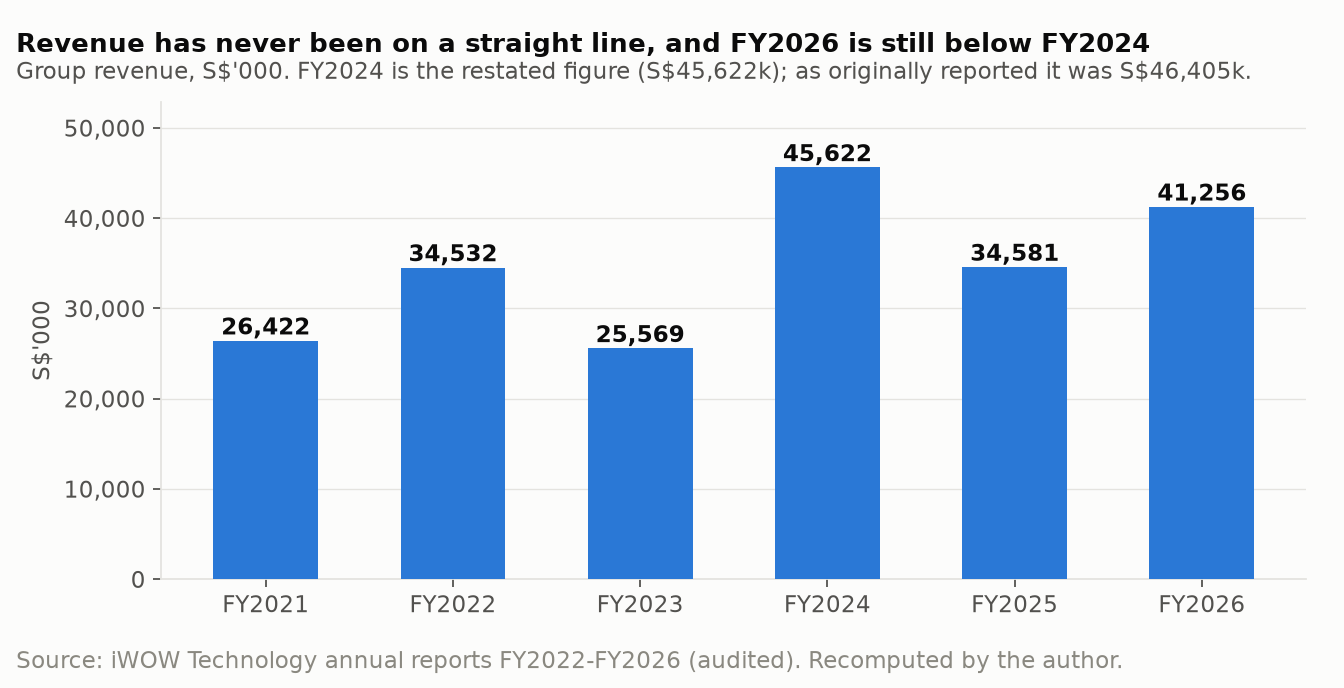
Revenue has run 26.4, 34.5, 25.6, 45.6, 34.6 and 41.3. FY2026 is 10% below restated FY2024. Growth measured from the FY2025 trough is measured from a trough.
Second-half weighting is severe and one-directional. The first half of FY2026 produced a profit before tax of S$699k; the full year reported a loss of S$1,036k, because the entire earn-out charge fell in the second half. Of the year’s S$3.59m operating profit, 80% arose in the second half.
Segment economics
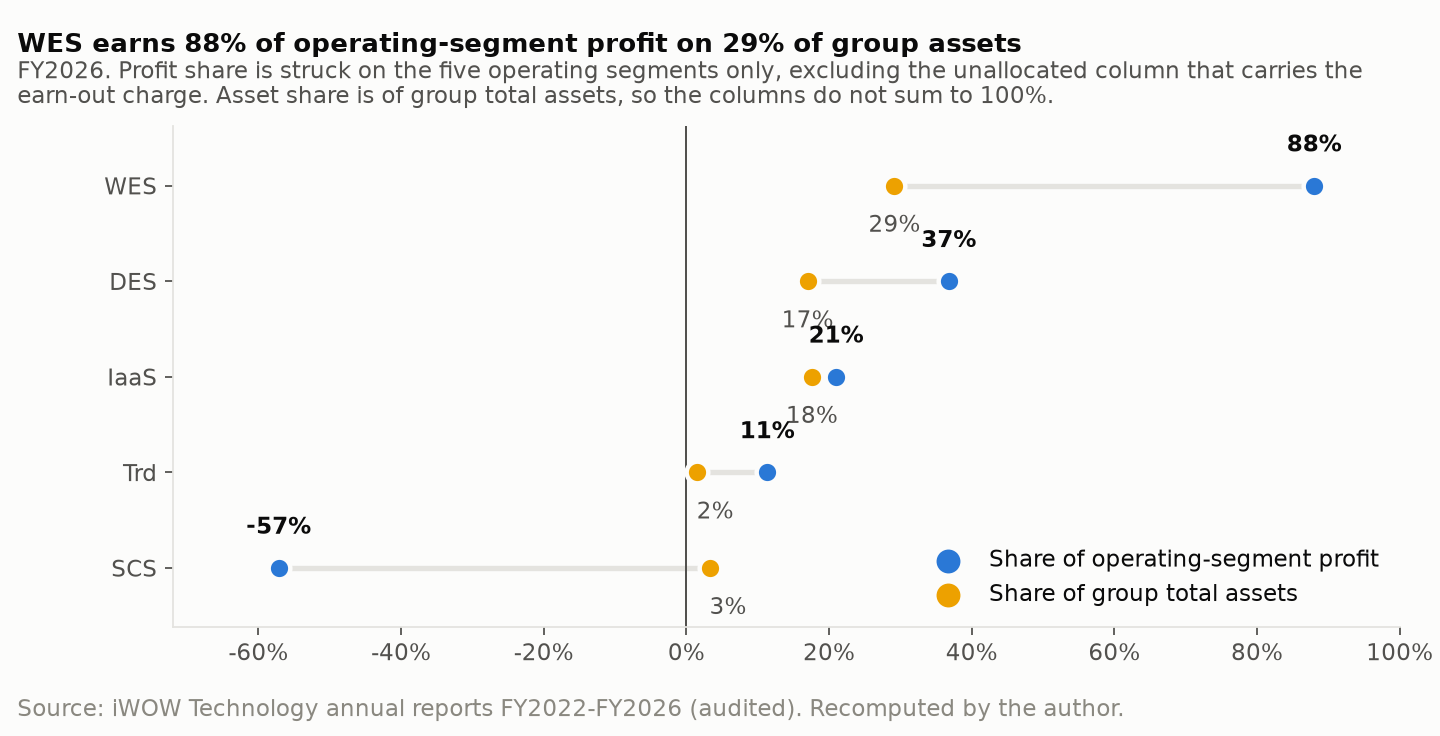
Judging these segments by margin alone gets the answer wrong. The clarifying comparison is what share of profit each produces against what share of the group’s assets it occupies.
Profit share is struck on the five operating segments only, excluding the unallocated column that carries the earn-out charge; asset share is of group total assets, so the two do not sum to 100%.
FY2026
Revenue
Segment PBT
Margin
Segment assets
Return on segment assets
Wireless Engineering Solutions
15,809
3,160
20.0%
12,859
24.6%
Datacomm & Enterprise Solutions
13,936
1,321
9.5%
7,494
17.6%
IoT-as-a-Service
7,251
754
10.4%
7,760
9.7%
Trading & Others
3,293
407
12.4%
679
59.9%
Smart City Solutions
967
(2,052)
n.m.
1,472
(139.4)%
The issuer’s segment result is struck before income tax but after allocated finance costs and depreciation. It is not EBIT and not gross profit, and comparing it with a peer’s EBIT-basis segment margin would be a silent error. Segment assets are disclosed as ending balances; no averages are published, so every return above is on ending assets.
Wireless Engineering Solutions margin ran 15.2%, 8.7% and 20.0% across FY2024 to FY2026. This is project contracting; the margin is an outcome, not a policy.
Trading & Others is worth a second look precisely because it is small: 11% of operating-segment profit on 1.5% of group assets, a 59.9% return on the assets it uses. Smart City Solutions carries S$1.83m of employee costs against S$0.97m of revenue — it is where the AgeTech and alarm-system product development is expensed as it is incurred.
The FY2024 restatement
The FY2025 annual report restates FY2024. The stated cause, in note 34, is a fabricated sales transaction perpetrated by a non-management sales employee of an overseas subsidiary in March 2024, supported by falsified documentation and correspondence. The group states it was discovered by the local finance team during FY2025 through existing internal controls, that the employee was terminated and a police report lodged, and that there was no financial loss because no third-party transaction occurred and no commission was paid. The auditors did not qualify the accounts.
FY2024, S$’000
As reported
Adjustment
As restated
Revenue
46,405
(783)
45,622
Profit before income tax
3,386
(251)
3,135
Profit for the year
2,779
(201)
2,578
Trade receivables
22,670
(769)
21,901
Two facts about it are worth stating precisely, and neither is an allegation. First, the entire S$783k sat in Malaysia: that country’s FY2024 revenue falls from S$2,841k as reported to S$2,058k restated, so the fabricated sale was 27.6% of that subsidiary’s revenue for the year. Second, March 2024 falls inside the ROOTS earn-out measurement window, and the earn-out is computed on audited net profit after tax. Whether the restated figure was the one used in the earn-out calculation is not disclosed — the calculation itself has never been published.
The receivable book
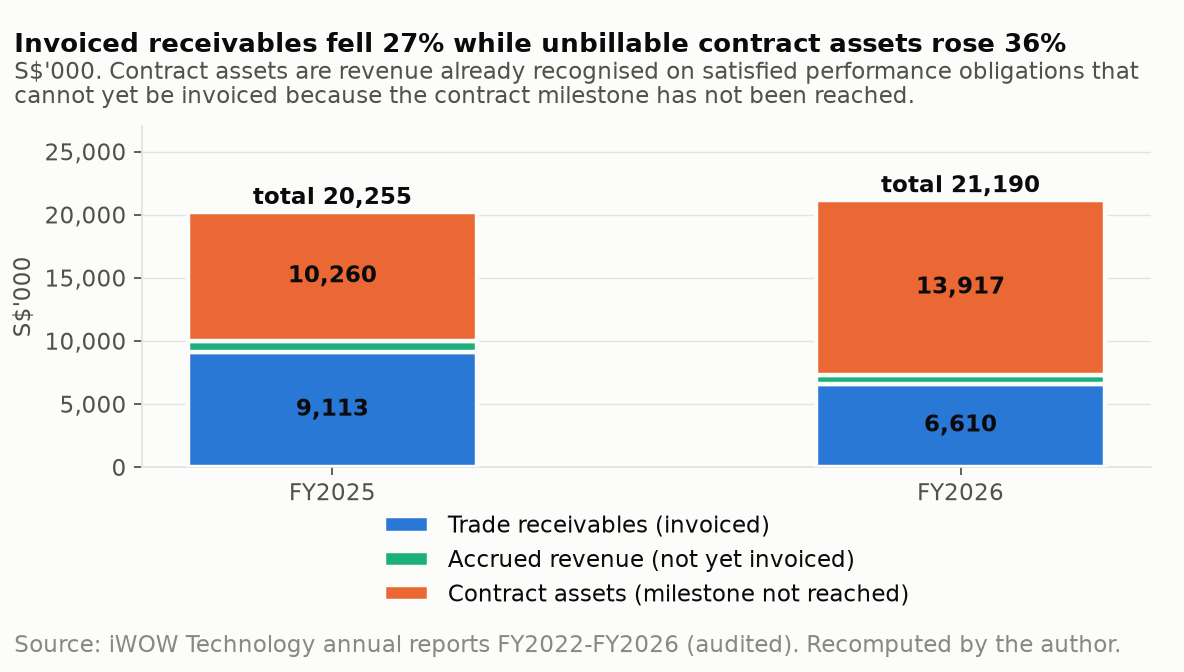
Contract assets are revenue already recognised on satisfied performance obligations that cannot yet be invoiced because a contract milestone has not been reached.
Total receivables and contract assets were S$21.2m against S$41.3m of revenue — 187 days. That blended figure is not a collection metric and should not be used as one: invoiced trade receivables are only S$6.6m, or 58 days. The remainder is S$13.9m of contract assets, 66% of the book, up from 51% a year earlier. Contract assets grew 35.6% while invoiced trade receivables fell 27.3%.
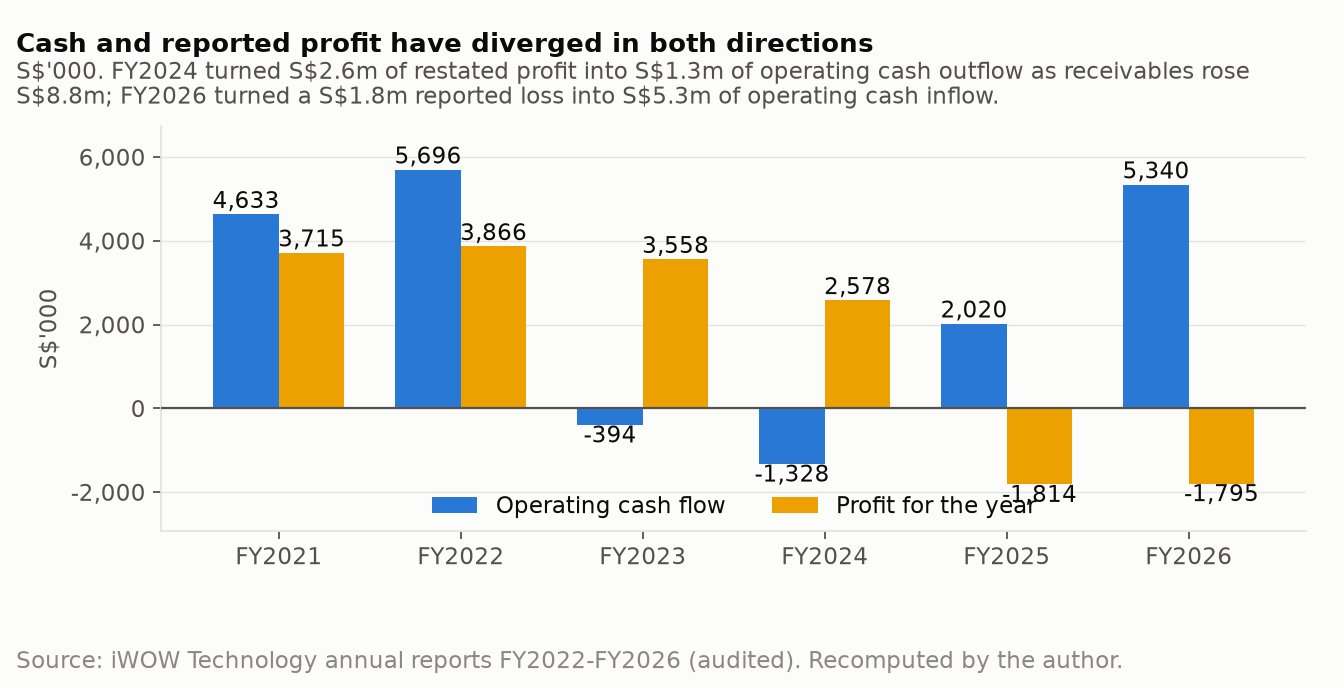
FY2024 turned S$2.6m of restated profit into a S$1.3m operating cash outflow as receivables rose S$8.8m; FY2026 turned a S$1.8m reported loss into S$5.3m of inflow. Single-year cash conversion says little here.
Cumulatively over the six years above, the company generated approximately S$16.0m of operating cash, spent approximately S$9.0m on capital expenditure and paid S$5.4m of dividends — self-funding, until the acquisitions. The audited FY2026 cash-flow statement records S$5.372m of operating cash flow, S$1.997m of cash capital expenditure and S$1.101m of lease principal, leaving S$2.274m of post-lease free cash flow.
Funding, share count and what is already committed
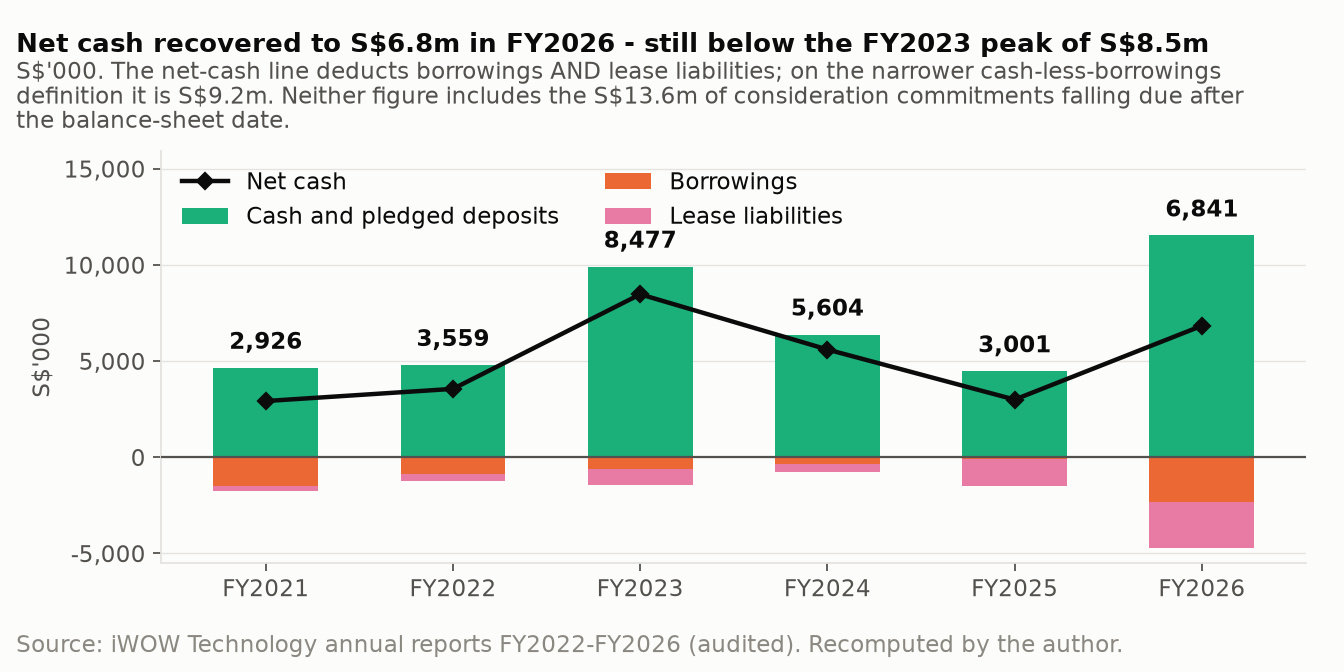
Net cash of S$6.8m after lease liabilities at FY2026 (S$9.2m before them), against S$8.5m at FY2023.
Three issuances of shares occurred within nine months, and a fourth is agreed:
October 2025 — 15,000,000 new shares for S$3,000,000, net proceeds S$2.95m.
1 July 2026 — 8,924,865 consideration shares issued on completion of The Gentle Group acquisition, taking the count from 278,132,160 to 287,057,025.
19 August 2026 ROOTS determination — 11,219,845 consideration shares determined at S$0.3327, representing S$3,732,842. They were not yet included in the 24 August issued-share count.
Placement completed — 66,667,000 new shares at S$0.225, gross approximately S$15.0m. Shareholders approved it at an extraordinary general meeting on 16 July 2026 and all 66,667,000 shares were allotted, taking the issued share count from 287,057,025 to 353,724,025.
24 August 2026 option exercise — 2,681,750 employee options were exercised at S$0.16, raising S$429,080 and taking issued shares to 356,405,775, excluding 258,100 treasury shares. A further 4,611,250 options remained exercisable.
Issued shares were 356.4m on 24 August after exercised options. Adding the 11.22m determined ROOTS shares gives 367.6m pro forma, before treasury-stock-method dilution for the 4.61m remaining options.
Against that, consideration already contracted and falling due totals S$13.6m: S$5.6m of ROOTS earn-out cash, S$7.0m paid for The Gentle Group on 1 July 2026, and S$1.0m of unconditional deferred consideration payable on a timing schedule linked to a revenue KPI. That is S$2.2m more than the S$11.5m of cash held at the balance-sheet date. Separately, section 4.6.1 of the acquisition announcement records an undertaking to provide expansion support of S$5.0m, or another agreed amount, through equity, loans, arranged third-party financing or a combination. It specifies a first S$2.0m tranche no later than 30 June 2026 and the balance according to funding needs before the relevant obligations fall due. Actual funding and the form used are not established here, so the undertaking is not treated as an additional immediate parent cash payment. Comparing the S$13.6m envelope with the S$15.0m gross placement gives 91%; that is an analyst fungibility stress, not the issuer's stated allocation. The circular describes the proceeds as 10%-15% for mergers and acquisitions, with the balance directed to manufacturing capacity, overseas expansion, research and development and working capital.
What it does with the cash
Capital allocation, as filed, from the consolidated statements of cash flows in the FY2022 to FY2026 annual reports. Read the operating-cash-flow row against the dividend row directly beneath it. In FY2023 and FY2024 the company paid dividends of $899,000 and $751,000 in years when its operations consumed $394,000 and $1,328,000 of cash. Two consecutive years of distributions funded from the balance sheet rather than from trading. The dividend then stopped.
S$’000
FY2022
FY2023
FY2024
FY2025
FY2026
Profit/(loss) before income tax
4,372
3,898
3,386
(1,695)
(1,036)
Operating cash flow
5,696
(394)
(1,328)
2,020
5,372
Additions to plant and equipment
1,407
685
173
2,028
1,505
Additions to intangible assets
546
671
516
493
492
Dividends paid
3,189
899
751
579
–
Cash at year end
4,797
9,856
6,327
4,415
11,471
What replaced it is on the same statement. FY2026 carries no dividend and instead $3.0m of proceeds from an issue of ordinary shares and $3.0m of new borrowings; the closing cash of $11.5m is the highest in the five years and most of the increase came from raising money, not from trading. Note also that profit before tax was positive in every year to FY2024 while operating cash flow was negative in two of them, and negative in FY2025 and FY2026 while operating cash flow was positive — on this company the two rows have pointed in opposite directions more often than they have agreed.
Ownership and market reference
As at 17 June 2026 the register held 128 shareholders. Kau Wee Lee held 42.59% and is the spouse of the non-executive chairman, who held a further 1.70% — a family block of 44.29%. The chief executive held 7.87%. The stated public float was 22.64%, against a Catalist minimum of 10%. Nineteen holders owned 96.83% of the company.
Lead independent director and audit and risk management committee chair Ang Swee Tian retired effective 31 July 2026. Based on the filings held through the cutoff, the resulting board has four directors, two of whom are independent; no successor lead independent director or audit-committee chair had been announced in the held source set.
Market-reference facts, from a daily price and volume series covering the twelve months to 18 August 2026: the closing price on 18 August 2026 was S$0.265; the twelve-month range was S$0.173 to S$0.500; the median daily traded value across all sessions was S$8,466, and the shares did not trade at all on 68 of 251 sessions. At 24 August 2026 there were 356,405,775 issued shares excluding treasury shares and 4,611,250 options remaining at a S$0.16 exercise price. At the S$0.265 reference price those remaining options represent approximately 1.827m treasury-stock-method incremental shares.
Events after the balance-sheet date
Two are recorded in the FY2026 annual report and both fall after 31 March 2026.
The Gentle Group Pte Ltd, a provider of clinically formulated therapeutic meals and rehabilitation solutions for hospitals, nursing homes and senior day-care operators, was acquired under an agreement dated 30 April 2026 and completed on 1 July 2026. Total consideration was S$11.2m, satisfied by net cash of approximately S$7.039m after a S$314k set-off, 8,924,865 shares with a fair value of about S$2.847m, and S$1.0m of deferred consideration payable to the founder. The purchase price allocation had not been finalised when the accounts were authorised on 14 July 2026, so no goodwill or intangible figure exists yet.
A placement of 66,667,000 new shares at S$0.225 was agreed on 30 June 2026 with ZICO Capital Pte Ltd, approved at an extraordinary general meeting on 16 July 2026 and completed. It was priced under Catalist Rule 811(3), which requires specific shareholder approval for a discount of more than 10 per cent: a 31.8 per cent discount to a volume-weighted average price of S$0.33 struck on 26 June 2026. The issued share count rose to 353,724,025.
Employee options added 2,681,750 shares on 24 August 2026 at S$0.16 per share, for S$429,080 of proceeds. The exercise split the 7.293m options already disclosed at FY2026 into shares now issued and 4,611,250 options still outstanding; it did not create a new option pool. The shares are expected to trade from 27 August 2026. SGX announcement, 24 August 2026. (R/D)
The share price and what came with its moves
Over the window iWOW returned +16.2% on a dividend-adjusted basis; the Straits Times Index returned +80.0% and the median of the 3 listed comparisons +94.3%.
Click a quarter — on the chart or in the return strip under it — to read its filings beside its large moves.
Key: iWOW (NXR) as a solid line; Straits Times Index rebased, dashed; peer median rebased, dotted; the peer median runs off scale Jun 26–Jun 26 and is clipped there; filing ticks above the axis; ex-dividend ticks on it; numbered pins are moves with a written note; plain dots are other detected moves.
Key moves
The five largest moves over a day or up to two weeks, with no day counted twice.
Each move is shown next to the market over the same days (and peers, where shown). News listed with a move was published within its dates; that does not mean the news caused the move. The quarter view has all the news.
Index: Straits Times Index. Peers: the median of three listed companies used as a sector check; the notes name them and their limits.
Q3 2023
22 Aug 2023 – 29 Sep 2023 (part quarter)
NXR +0.0%STI +1.8%Peer median −5.9%Range S$0.23–S$0.25Close S$0.23
The customer is described as a leading commercial real-estate services provider in Singapore. The initial component of about S$2.3m (smart-metering equipment, system maintenance and billing-as-a-service) runs over 60 months; a five-year extension option adds up to about S$2.5m. Excluding the option, the order book rises from S$84.7m at 30 June 2023. The company said the contract is not expected to have a material impact on FY2024 (the year to 31 March 2024).
Next session (24 Aug): NXR +0.0% · STI +0.2% · peers +0.0%
The deck recaps FY2023 (year to 31 March 2023) at revenue S$25.6m, net profit S$3.6m and a 13.9% net margin, and shows the order book rising from S$56.0m in June 2022 to S$84.7m in June 2023 and S$106.1m in August 2023 after the S$20.0m Smart City Infrastructure award of July 2023 and the S$4.8m smart-metering award. It lists the Roots Communications acquisition (completed January 2023), a Malaysian R&D office, a personal alert button and new electronic-monitoring tags in development, and Japan, Thailand, Malaysia, Indonesia and the UAE as target markets. No new contract or financial figure is disclosed.
Next session (26 Sep): NXR +0.0% · STI −0.0% · peers +0.0%
Large price moves
14 Sep 2023 · +9% · index 0% · peers 0%
2week to 8 Sep 2023 · +9% · index −1% · peers −3%
Q4 2023
2 Oct 2023 – 29 Dec 2023
NXR −6.4%STI +0.7%Peer median +1.4%Range S$0.20–S$0.24Close S$0.22
Smart City Solutions revenue fell 97% to S$0.4m with no TraceTogether-token sales and no alert-alarm installation work after project completion; the Wireless Engineering (S$8.9m) and Datacomm & Enterprise (S$3.3m) segments that came with Roots Communications contributed S$12.2m against nil a year earlier; IoT-as-a-Service eased 3% to S$2.9m. Employee benefits tripled to S$5.9m as headcount rose from 51 to 164 (65 excluding the Roots segments) and other operating expenses rose to S$5.2m, including S$3.9m of sub-contracting. Profit before tax was S$0.3m against S$2.7m. Cash fell by about S$2.9m to about S$7.0m after a S$2.1m working-capital outflow on accrued revenue awaiting infrastructure billing milestones and the S$0.7m FY2023 dividend; borrowings were S$0.5m. No interim dividend.
Guidance: Order book S$100.4m at 31 October 2023; the company said it was 'cautiously confident' of 2H FY2024 revenue as the bulk of the S$20.0m July 2023 installation contract is fulfilled, while some projects fall into FY2025 and continued R&D hiring 'may add short term pressure to the bottom line'.Next session (15 Nov): NXR +0.0% · STI +0.9% · peers +1.5%
The deck for the 8 December 2023 webinar on the 1H FY2024 results adds an order-book fulfilment horizon (S$37.9m within one year, S$54.7m in one to five years, S$7.8m beyond five years) and restates the half-year figures: revenue S$17.3m, net profit S$0.3m, net asset value 7.18 cents a share. No new contracts are disclosed.
Next session (8 Dec): NXR −4.8% · STI +1.2% · peers +1.5%
Large price moves
324 Oct 2023 · −13% · index +1% · peers +5%
4week to 27 Oct 2023 · −13% · index −1% · peers −1%
53 Nov 2023 · +10% · index +2% · peers 0%
620 Nov 2023 · +14% · index 0% · peers +1%
721 Nov 2023 · −13% · index −1% · peers 0%
813 Dec 2023 · +15% · index 0% · peers 0%
9week to 15 Dec 2023 · +15% · index 0% · peers +9%
1026 Dec 2023 · −11% · index 0% · peers 0%
Q1 2024
2 Jan 2024 – 28 Mar 2024
NXR −4.5%STI −0.5%Peer median −10.0%Range S$0.18–S$0.23Close S$0.21
Total consideration S$12,914 including costs. A further 112,600 shares were bought at S$0.20 on 27 February 2024, taking treasury shares to 177,100 (0.07% of issued shares) and issued shares excluding treasury to 263,213,160. These are the only purchases under that mandate on the tape.
The solution bundles a battery-powered button with an intercom, a dedicated eldercare helpdesk and a caregiver app. The company called it 'an important milestone' in its eldercare roadmap but said it was not expected to have a material impact on FY2024. Broadcast at 12:09, during the trading session.
Large price moves
1112 Mar 2024 · +24% · index 0% · peers 0%
12week to 15 Mar 2024 · +21% · index +1% · peers 0%
Q2 2024
1 Apr 2024 – 28 Jun 2024
NXR −4.8%STI +3.4%Peer median +3.3%Range S$0.20–S$0.23Close S$0.20
The contract from a major Singapore telecommunications service provider covers expansion, safety-enhancement, recovery, relocation and retrofitting works on radio base stations and other mobile-network sites. The company said it was not expected to have a material impact on FY2025 (the year to 31 March 2025). The order book is down from S$100.4m in October 2023 as work was fulfilled.
Next session (18 Apr): NXR +7.1% · STI +1.0% · peers −0.6%
Wireless Engineering revenue rose to S$23.8m from S$2.5m and Datacomm & Enterprise to S$11.2m from S$1.7m (two months' contribution in FY2023), helped by progress on the S$20.0m July 2023 contract; Smart City Solutions fell 92% to S$1.2m after the TraceTogether-token project ended; IoT-as-a-Service was flat at S$6.0m. The second half carried the year: 2H FY2024 revenue S$29.1m (up 242.5%) and net profit S$2.5m (up 115.3%) against S$0.3m in the first half. Net margin was 6.0% against 13.9%. Operating activities used cash as trade receivables rose to S$22.7m from S$12.8m on S$5.7m of accrued revenue awaiting infrastructure billing milestones; cash fell to S$6.3m from S$9.9m. The board said it intends to recommend dividends of at least 20% of net profit for FY2024 and FY2025.
Guidance: Order book about S$93.5m as of April 2024, expected to generate revenue over the next five years; the BOP Button and new wrist tags for electronic monitoring are expected to create new revenue streams; 'cautiously optimistic' on long-term prospects.Next session (28 May): NXR −9.1% · STI +0.4% · peers −1.6%
Large price moves
138 May 2024 · −12% · index −1% · peers 0%
1410 May 2024 · +19% · index +1% · peers 0%
1513 May 2024 · −15% · index 0% · peers 0%
1617 May 2024 · +19% · index 0% · peers −1%
1720 May 2024 · −16% · index 0% · peers 0%
Q3 2024
1 Jul 2024 – 30 Sep 2024
NXR −0.4%STI +7.6%Peer median +0.5%Range S$0.19–S$0.20Close S$0.20
Approved at the AGM of 26 July 2024; the record date was 5 pm on 8 August 2024 and payment followed on 23 August 2024. The ex-date is taken as the market day before the record date. It is the only dividend in the window: none was declared for FY2025 or FY2026.
Large price moves
1826 Sep 2024 · −5% · index 0% · peers +3%
Q4 2024
1 Oct 2024 – 31 Dec 2024
NXR −5.6%STI +5.6%Peer median +0.0%Range S$0.19–S$0.23Close S$0.19
IoT-as-a-Service rose 16% to S$3.4m on smart-metering and electronic-monitoring demand and Wireless Engineering 11% to S$9.9m on the S$20.0m July 2023 contract; Datacomm & Enterprise fell 18% to S$2.7m, Trading & Others 55% to S$0.8m and Smart City Solutions 34% to S$0.3m. Employee benefits rose 9% to S$6.5m (higher CPF rates, less R&D capitalisation and the first ESOS grant); a S$146,000 tax credit from an M&A allowance on the Roots acquisition supported the profit line. Operating cash inflow was S$3.0m as inventories fell S$1.9m; S$1.5m went into IaaS leasing assets; cash rose S$0.5m to S$6.8m. The BOP Button went on sale at Harvey Norman from end-October 2024. No interim dividend.
Guidance: Order book S$83.5m at 31 October 2024, down from S$93.5m in April; the company said the BOP Button launch 'will be pivotal' to new public-sector and consumer opportunities and that it remained 'cautiously optimistic' on long-term prospects amid rising expenses.Next session (12 Nov): NXR +0.0% · STI −0.7% · peers +0.0%
Large price moves
197 Oct 2024 · +7% · index 0% · peers 0%
2021 Oct 2024 · +12% · index −1% · peers 0%
21week to 25 Oct 2024 · +12% · index −1% · peers −2%
227 Nov 2024 · −13% · index +2% · peers 0%
23week to 8 Nov 2024 · −13% · index +5% · peers +2%
Q1 2025
2 Jan 2025 – 28 Mar 2025
NXR +1.6%STI +4.9%Peer median −6.1%Range S$0.18–S$0.19Close S$0.19
Announced after a trading halt requested at 13:19 on 27 January 2025 and lifted with the announcement. The contract from a statutory board, named as the Government Technology Agency in a 3 February 2025 press release, covers design, supply, installation, operation and maintenance of alert buttons in HDB rental flats as an IoT-as-a-Service subscription, extending a system in 51 blocks since November 2019 to around 170 more blocks and about 26,800 more seniors, with optional fall sensors and wearables. The company stressed that the contract specifies no overall value: the S$50m base and S$80m total are its own projections from a tentative deployment schedule. The base award lifts the order book by 55%, or S$46m, from the 31 October 2024 figure; no material impact on FY2025 was expected.
Next session (3 Feb): NXR +5.6% · STI −0.8% · peers +0.0%
Total consideration S$15,368; cumulative purchases under both mandates are 0.1% of issued shares, and issued shares excluding treasury fall to 263,132,160. This is the last buy-back on the tape.
Large price moves
243 Feb 2025 · +6% · index −1% · peers 0%
256 Feb 2025 · +6% · index 0% · peers 0%
Q2 2025
1 Apr 2025 – 30 Jun 2025
NXR −8.5%STI −0.2%Peer median −3.4%Range S$0.17–S$0.19Close S$0.17
Operating profit before tax is expected at S$1.4m against S$3.1m, which the company attributed to a higher cost base from R&D and business-development hiring while revenue was held back by delayed awards, including the WAAS contract. The estimated Roots consideration was raised from S$10.0m to S$13.0m because the earn-out, six times the Roots group's average net profit over 1 April 2023 to 31 March 2026, is running above plan; the charge is non-cash and goes through the income statement rather than goodwill. A S$0.1m goodwill impairment is also flagged. FY2024 comparatives are restated, with details deferred to the results.
Guidance: Order book about S$131m at April 2025 (April 2024: S$94m); WAAS deployment expected to begin contributing revenue from May 2025.Next session (26 May): NXR +1.7% · STI −0.2% · peers +0.7%
Wireless Engineering fell 36% to S$15.1m after the one-off S$20.0m infrastructure project completed, Datacomm & Enterprise 15% to S$9.5m, Trading & Others 33% to S$2.3m and Smart City Solutions 27% to S$0.9m; IoT-as-a-Service rose 12% to S$6.7m. Second-half revenue was S$17.5m, down 38%. Operating profit fell 54% to S$1.4m; the net loss compares with a restated S$2.6m profit (adjusted net profit S$1.3m). The restatement removed S$0.8m of FY2024 revenue and S$0.2m of profit for a sale fabricated in March 2024 by a sales employee of an overseas subsidiary, caught by the local finance team with no cash loss. Operating cash inflow was S$2.0m; S$2.4m went into IaaS leasing assets and development; cash fell to S$4.4m from S$6.3m. No dividend, citing the loss, against the 20%-of-profit intention stated a year earlier.
Guidance: Order book S$131.0m at 30 April 2025, up from S$83.5m in October 2024, with improvement in financial performance expected 'as these orders are progressively fulfilled'; BOP Pte Ltd awarded a S$1m DBS Foundation grant over two years.Next session (30 May): NXR −2.2% · STI −0.6% · peers +0.0%
BOP was one of four winners globally and the only one from Singapore. The release gives the deployment record under HDB's wireless alert alarm system since November 2019: about 20,200 activations, of which around 1,600 required emergency intervention. The first tranche was received in 1H FY2026 and booked in other operating income.
Next session (10 Jun): NXR +0.0% · STI −0.1% · peers +1.0%
Large price moves
265 May 2025 · −6% · index 0% · peers 0%
2730 Jun 2025 · −6% · index 0% · peers 0%
Q3 2025
1 Jul 2025 – 30 Sep 2025
NXR +67.6%STI +8.5%Peer median +33.8%Range S$0.17–S$0.32Close S$0.29
The subscriber, private investor Mehta Vimesh Piyush, held 2.73% and would hold 7.98% of the enlarged capital; the issue is 5.7% of existing shares (computed), under the general mandate, with no placement agent, no introducer and no moratorium. Proceeds: S$2.0m (67.8%) for investments, M&A and 'payment obligations arising from previously completed transactions', and S$950,000 for Age-Tech working capital including capital expenditure on the WAAS deployment. The directors said working capital was adequate with or without the subscription.
Next session (23 Sep): NXR +31.0% · STI +0.1% · peers +0.8%
Large price moves
2825 Jul 2025 · +11% · index 0% · peers 0%
29week to 25 Jul 2025 · +9% · index +2% · peers +17%
309 Sep 2025 · +6% · index 0% · peers 0%
3117 Sep 2025 · +9% · index 0% · peers −1%
32week to 19 Sep 2025 · +17% · index −1% · peers +1%
3323 Sep 2025 · +31% · index 0% · peers +1%
3429 Sep 2025 · +37% · index 0% · peers +1%
Q4 2025
1 Oct 2025 – 31 Dec 2025
NXR +44.8%STI +8.0%Peer median +8.6%Range S$0.33–S$0.50Close S$0.42
The listing and quotation notice was announced at 12:07 the same day and the shares were to trade from about 17 October 2025. Gross proceeds S$3.0m. The subscriber later reported crossing 9% through market purchases (17 November 2025 notice).
Datacomm & Enterprise revenue rose 120% to S$6.0m on network-infrastructure sales, Trading & Others 85% to S$1.4m and Smart City Solutions 114% to S$0.6m; Wireless Engineering fell 23% to S$7.7m against the prior year's S$20.0m contract; IoT-as-a-Service was flat at S$3.4m. Other operating income rose to S$0.8m on the first DBS Foundation tranche. Employee benefits rose 9% on hiring for the WAAS deployment and depreciation 31% on new Age-Tech leasing assets. Operating cash inflow was S$2.3m; cash rose S$2.8m to S$7.2m; a S$0.3m stake was taken in a local AI start-up for senior wellness. BOP Presence, a Wi-Fi-sensing smart plug, was launched, with the BOP Monitor fall sensor due in 1Q 2026. No interim dividend.
Guidance: WAAS deployment 'still in its early phase', with month-on-month revenue growth expected over a three-to-four-year rollout and 'higher margin contribution from each additional WAAS revenue dollar'; M&A in the 'Silver Economy' being pursued; order book S$115.2m at 31 October 2025.Next session (11 Nov): NXR +1.0% · STI +1.2% · peers +0.0%
Large price moves
351 Oct 2025 · +22% · index +1% · peers +1%
36week to 3 Oct 2025 · +57% · index +3% · peers +3%
3716 Oct 2025 · +21% · index 0% · peers −1%
38week to 17 Oct 2025 · +33% · index −2% · peers −7%
Q1 2026
2 Jan 2026 – 31 Mar 2026
NXR −16.7%STI +5.1%Peer median +1.7%Range S$0.35–S$0.42Close S$0.35
The unnamed target makes clinically formulated therapeutic diets, including texture-modified foods for dysphagia, kidney disease and diabetes, mainly for healthcare and eldercare institutions; its controlling shareholders hold about 95%. Only the consideration, its form, exclusivity and confidentiality bind. The cash portion (including S$1.0m to the founder) carries no earn-out or clawback; the issue price of the consideration shares was left to be agreed. The company framed the deal as a move from Age-Tech into a broader 'silver economy' offering.
Next session (2 Feb): NXR −3.6% · STI −0.3% · peers −2.3%
Large price moves
394 Mar 2026 · −6% · index −2% · peers −4%
4023 Mar 2026 · −10% · index −2% · peers −3%
Q2 2026
1 Apr 2026 – 30 Jun 2026
NXR −5.7%STI +5.8%Peer median +71.6%Range S$0.31–S$0.41Close S$0.33
The Gentle Group makes clinically formulated therapeutic meals and texture-modified foods for hospitals, nursing homes and senior-care operators; the press release cites revenue growth of about 51% a year over FY2022-FY2025 without giving the level. Institutional vendors get S$5.6m cash at completion, minority and option holders S$0.4m; founder Dr Shen Yiru gets S$1.0m cash, S$2.85m in consideration shares under moratorium (not more than 10% below the S$0.354 VWAP of 29 April 2026) and S$1.0m of deferred cash, paid in October 2027 if revenue for the year to 31 March 2027 is at least 20% above calendar 2025, otherwise April 2028. Figures are from management accounts; no independent valuation. Pro forma goodwill S$8.8m; NTA per share 3.28 cents from 5.66. No shareholder vote was required (Catalist Rule 1006 figures between 5% and 75%).
The estimated Roots consideration rises from S$13.0m to a final S$17.4m as the three-year earn-out period closed on 31 March 2026; the company said no further adjustment would follow. Operating profit after tax would have been S$2.8m against S$1.3m. Revenue growth came from all five segments, led by the Smart City Infrastructure businesses.
Guidance: Order book about S$107m at April 2026; WAAS subscription revenue 'expected to scale progressively'; the Gentle Group acquisition expected to add to the revenue base on completion.Next session (27 May): NXR +0.0% · peers +0.0%
Datacomm & Enterprise revenue rose 58% to S$13.9m, Wireless Engineering 4% to S$15.8m, IoT-as-a-Service 8% to S$7.3m on WAAS subscriptions and electronic monitoring, Trading & Others 8% to S$3.3m and Smart City Solutions 13% to S$1.0m. Second-half revenue was S$22.2m, up 27%. Employee benefits rose 10% to S$14.0m and depreciation 28% to S$2.3m on the WAAS rollout; other operating income rose 72% to S$1.1m on the DBS grant. Adjusted net profit was S$2.8m (FY2025: S$1.3m); the reported loss narrowed from S$1.8m. Operating cash inflow was S$5.3m; cash rose S$7.1m to S$11.5m after the S$3.0m placement and a new loan for the WAAS project that took borrowings to S$2.3m from S$0.1m. No dividend for a second year, citing the loss.
Guidance: Order book about S$107m at 30 April 2026, 'providing healthy revenue visibility into FY2027 and beyond'; WAAS revenue to scale over a four-year deployment; the Gentle Group deal 'expected to be earnings-accretive over time as the business scales'.Next session (2 Jun): NXR +0.0% · STI +1.2% · peers −3.5%
ZICO Capital is placement agent on a best-efforts basis with Maybank Securities as sub-placement agent; the shares are 24.0% of existing issued shares and 19.3% of an enlarged 344,799,160. Net proceeds of about S$14.46m after S$542,000 of costs: 25-35% to expand Clinical Nutrition manufacturing capacity, the rest across overseas expansion, sales and marketing, R&D, M&A and working capital. The board cited wide bid-ask spreads and thin liquidity, the size of the raise and intermediary feedback in setting the price. Shareholders passed the resolution at the 16 July 2026 EGM with 173,517,456 votes, 100%, in favour.
Next session (1 Jul): NXR +0.0% · STI −0.2% · peers +1.4%
Large price moves
417 May 2026 · +5% · index 0% · peers +4%
4215 Jun 2026 · −6% · index +1% · peers +4%
4322 Jun 2026 · −8% · index 0% · peers +2%
4423 Jun 2026 · +7% · index 0% · peers −7%
Q3 2026
1 Jul 2026 – 21 Aug 2026 (part quarter)
NXR −18.2%STI +10.0%Peer median +0.1%Range S$0.23–S$0.34Close S$0.27
Cash at completion: S$5,612,216 to institutional vendors, S$1,000,000 to the founder, S$84,472 to minority holders and S$342,201 to option holders; the founder's S$1.0m deferred payment remains outstanding. A condition requiring service agreements with two other option holders was waived at the company's request. The 2 July 2026 press release (19:20) says the target won two three-year contracts, with a leading operator of public nursing homes and a senior-care provider, since January, taking the group order book to about S$127m at 1 July 2026 from about S$107m at 30 April, and that a new production facility is expected to lift the target's capacity by up to five times once renovated.
Next session (2 Jul): NXR +0.0% · STI +1.1% · peers −0.4%
The Catalist Rule 704(5) notice also records a S$158,000 fair-value loss, through other comprehensive income, on an unquoted investment, taking total equity to S$24.23m from S$24.39m. Operating profit of S$3.59m is unchanged; the earn-out adjustment is equity-settled and has no effect on total equity or cash.
Mr Ang, citing personal reasons including his age, also leaves the nominating and remuneration committees. The Audit & Risk Management Committee is left with two members (Thong Yuen Siew Jessie and Liew Kok Oon) against a minimum of three; the board said it would fill the vacancy within two months and no later than three.
Placees named include fund managers under Singapore's Equity Market Development Programme, Dr Lim Cheok Peng (managing director of IHH Healthcare in 2011-13) and institutions including Amova, Areca Capital, Asdew Acquisitions, Avanda, Azure Capital, Ginko-AGT Global Growth Fund, ICH Synergrowth Fund, Lion Global Investors, Tokio Marine Life Insurance Singapore, UOB Asset Management and Value Partners. Net proceeds about S$14.5m; the press release (18:59) says 25-35% goes to expanding GentleFoods manufacturing capacity by up to five times.
Next session (29 Jul): NXR −8.6% · STI +1.7% · peers −0.8%
Average net profit of the Roots group over 1 April 2023 to 31 March 2026 was S$2,905,351; six times that gives S$17,432,106, below the S$18.0m cap and above the S$1.35m profit-guarantee floor. The initial S$8.1m tranche (60% cash, 40% shares) was paid at completion on 31 January 2023. The issue price is a 10% discount to the 30-day VWAP to 31 March 2026 of S$0.3696; the shares are 3.17% of issued capital, go to three nominees of the vendor, the largest of whom (Chan Kin Kok) will hold 4.97% of the enlarged 364,943,870 shares, and are issued under the general mandate of the 31 July 2026 AGM.
Next session (20 Aug): NXR +0.0% · STI −0.4% · peers −2.6%
Large price moves
4517 Jul 2026 · −10% · index −1% · peers −2%
4620 Jul 2026 · +7% · index 0% · peers +1%
4729 Jul 2026 · −9% · index +2% · peers −1%
4830 Jul 2026 · −11% · index −1% · peers −2%
49week to 31 Jul 2026 · −28% · index +1% · peers −4%
505 Aug 2026 · +18% · index −1% · peers +1%
51week to 7 Aug 2026 · +15% · index +1% · peers +1%
Notes and sources
Share price record
How this section was built
The detector flagged 51 large moves in the window — 39 single sessions and 12 weekly windows — before any news was read. 2 sector moves; 49 are left over after both controls, unexplained by them. Of those, 5 followed a filing by timestamp, 4 coincided with one in the same session or week and 40 have nothing filed against them beyond routine notices and are recorded as unexplained rather than explained away.
This section records the 36-month price history and puts every large move through two subtractions and reports what is left over, not what caused it: first the Straits Times Index, then the median of the 3 listed comparisons — Addvalue Technologies, ISDN Holdings and Venture Corporation — which trade the same session. “Left over” is what survives both controls.
Each quarter panel pairs two records. Key developments are the filings that carry information — results, contract awards, the placement and subscription, the clinical-nutrition acquisition, dividend events — with the figures as filed, the guidance given, the close on the day and how the reacting session traded against the controls; a filing after the 09:00 open is read against the next session. Large price moves are the threshold-detected sessions, detected before any news was read and dispositioned from the controls and the enumerated tape; rows with a written note carry a numbered pin, the rest are dots on the line.
How to read the tags.Market-wide and Sector-wide mean the index or the peer median moved with the share over the same session or week; Residual means the move is still large after both are subtracted. A residual is what is left over, not a cause: it does not establish that the company’s own news moved the price, and an unchanged or thinly traded price is not proof that no information arrived. Returns use the dividend-adjusted close; a filing released after the open is read against the next session.
Prices are NXR.SI daily adjusted closes over 22 August 2023 to 21 August 2026 (the only dividend in the window is the 0.22-cent FY2024 final), cross-checked against the SGX official daily series for the last twelve months; the filings tape is every SGXNet announcement by the issuer over the same window from the SGX announcements API, with SGX broadcast times. A filing after the open is read against the next session.
Limitations bound every row above. The tape is every SGXNet broadcast by iWOW Technology over 22 August 2023 to 21 August 2026 — 133 announcements, of which six are results releases, two are profit-guidance notices, three are contract awards, two are placements and four concern acquisitions; 71 are disclosure-of-interest notices, most of them small market purchases by the chairman's spouse in February–March and July–September 2025 and the shareholding changes around the two placements, and the rest are AGM, annual-report, option-grant and buy-back paper. Broker notes, block trades and substantial-shareholder timing, trade press and index reviews were not examined. The operating subsidiaries — Roots Communications (the Smart City Infrastructure segments), BOP Pte Ltd (Age-Tech), The Gentle Group (from 1 July 2026) and iWOW Malaysia — have no disclosure stream of their own, and no separate announcement record was compiled for them, so their news reaches the tape only through the parent's filings. The stock is thinly traded: 68 of the 251 sessions in the twelve-month SGX series used here had no volume, so many detected moves are single prints. The peer control is three listed electronics and IoT names (Addvalue, ISDN, Venture) whose session returns frequently differ in nature from a Catalist age-tech and telecoms-infrastructure contractor; of the 51 detected moves, four followed a filing, four sat in the same week as one, two were read as market or sector moves, and 41 had no material filing in the preceding three sessions.
A quarter shows only the columns it has. An empty developments column means: No filings beyond routine disclosures this quarter. An empty moves column means: No session cleared the large-move threshold this quarter.
The full move register — every large move and its market and sector controls
Every threshold-detected move in the window with its controls, dispositioned in the price-driver register; rows with a written note carry a numbered pin on the chart.
#
Session
NXR
STI
Peers
Left over
Control result
What the evidence supports
1
4 Sep 2023
+8.7%
+0.2%
+0.0%
+8.7%
Residual
Against an index move of +0.2% and a peer median of +0.0%, about 9 points are left over; 0.8× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +3.8 · Venture −1.0
2
week to 8 Sep 2023
+8.7%
−0.8%
−2.5%
+11.2%
Residual
Weekly window, 2023-08-31 to 2023-09-08: against an index move of −0.8% and a peer median of −2.5%, about 11 points are left over. No filing beyond routine notices inside the window. Addvalue +0.0 · ISDN −2.5 · Venture −2.7
3
24 Oct 2023
−12.5%
+1.0%
+4.8%
−17.3%
Residual
Against an index move of +1.0% and a peer median of +4.8%, about 17 points are left over; 0.1× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +10.0 · ISDN +4.8 · Venture +1.7
4
week to 27 Oct 2023
−12.5%
−0.5%
−0.8%
−11.7%
Residual
Weekly window, 2023-10-20 to 2023-10-27: against an index move of −0.5% and a peer median of −0.8%, about 12 points are left over. No filing beyond routine notices inside the window. Addvalue +0.0 · ISDN −1.5 · Venture −0.8
5
3 Nov 2023
+9.5%
+2.0%
+0.0%
+9.5%
Residual
Against an index move of +2.0% and a peer median of +0.0%, about 10 points are left over; 0.0× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +0.0 · Venture +2.0
6
20 Nov 2023
+14.3%
−0.4%
+1.2%
+13.0%
Residual
Against an index move of −0.4% and a peer median of +1.2%, about 13 points are left over; 0.4× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −9.1 · ISDN +1.5 · Venture +1.3
7
21 Nov 2023
−12.5%
−0.5%
−0.4%
−12.1%
Residual
Against an index move of −0.5% and a peer median of −0.4%, about 12 points are left over; 1.2× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN −1.5 · Venture −0.4
8
13 Dec 2023
+15.0%
+0.1%
+0.0%
+15.0%
Residual
Against an index move of +0.1% and a peer median of +0.0%, about 15 points are left over; 1.6× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +0.0 · Venture −0.8
9
week to 15 Dec 2023
+15.0%
+0.2%
+9.0%
+6.0%
Residual
Weekly window, 2023-12-08 to 2023-12-15: against an index move of +0.2% and a peer median of +9.0%, about 6 points are left over. No filing beyond routine notices inside the window. Addvalue +11.1 · ISDN +9.0 · Venture −3.0
10
26 Dec 2023
−11.1%
−0.0%
+0.0%
−11.1%
Residual
Against an index move of −0.0% and a peer median of +0.0%, about 11 points are left over; 0.4× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +0.0 · Venture +0.1
11
12 Mar 2024
+23.7%
+0.1%
+0.0%
+23.7%
Residual
A single session of 100,000 shares (4.1× median volume) after four sessions in which 1,200 shares traded in all; the S$0.19 reference close was set by a 100-share print on 6 March, and against the S$0.20 at which 145,400 shares changed hands on 27 February (including the company's own 112,600-share buy-back) the move is 17.5%. The index and the peer median were flat. Nothing was filed in the prior three sessions; the subsidiary's BOP Button launch was broadcast at 12:09 on 15 March, three sessions later, and no shares traded on the 14th or the 15th. The price then sat at S$0.23 on no volume until 25 March, when it fell 8.7%. Addvalue +0.0 · ISDN −1.6 · Venture +0.3
12
week to 15 Mar 2024
+21.1%
+0.8%
+0.0%
+21.1%
Residual
Weekly window, 2024-03-08 to 2024-03-15: against an index move of +0.8% and a peer median of +0.0%, about 21 points are left over. No filing beyond routine notices inside the window. Addvalue +0.0 · ISDN +0.0 · Venture −0.6
13
8 May 2024
−12.0%
−1.1%
+0.0%
−12.0%
Residual
Against an index move of −1.1% and a peer median of +0.0%, about 12 points are left over; 0.1× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +0.0 · Venture +2.8
14
10 May 2024
+18.7%
+0.8%
+0.2%
+18.5%
Residual
Against an index move of +0.8% and a peer median of +0.2%, about 18 points are left over; 0.4× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +10.0 · ISDN +0.0 · Venture +0.2
15
13 May 2024
−14.9%
+0.4%
−0.1%
−14.8%
Residual
Against an index move of +0.4% and a peer median of −0.1%, about 15 points are left over; 1.1× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN −3.2 · Venture −0.1
16
17 May 2024
+19.3%
+0.3%
−0.5%
+19.8%
Residual
Against an index move of +0.3% and a peer median of −0.5%, about 20 points are left over; 0.9× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +20.0 · ISDN −1.6 · Venture −0.5
17
20 May 2024
−15.7%
+0.0%
+0.4%
−16.1%
Residual
Against an index move of +0.0% and a peer median of +0.4%, about 16 points are left over; 1.4× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −8.3 · ISDN +1.7 · Venture +0.4
18
26 Sep 2024
−5.0%
−0.0%
+2.5%
−7.5%
Residual
Against an index move of −0.0% and a peer median of +2.5%, about 8 points are left over; 0.1× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +10.0 · ISDN +1.7 · Venture +2.5
19
7 Oct 2024
+6.6%
+0.3%
−0.1%
+6.7%
Residual
Against an index move of +0.3% and a peer median of −0.1%, about 7 points are left over; 0.1× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −9.1 · ISDN +0.0 · Venture −0.1
20
21 Oct 2024
+12.2%
−0.7%
−0.1%
+12.3%
Residual
Against an index move of −0.7% and a peer median of −0.1%, about 12 points are left over; 1.2× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +11.1 · ISDN −3.2 · Venture −0.1
21
week to 25 Oct 2024
+12.2%
−1.3%
−1.7%
+13.9%
Residual
Weekly window, 2024-10-18 to 2024-10-25: against an index move of −1.3% and a peer median of −1.7%, about 14 points are left over. No filing beyond routine notices inside the window. Addvalue +22.2 · ISDN −3.2 · Venture −1.7
22
7 Nov 2024
−13.0%
+2.0%
+0.0%
−13.0%
Residual
Against an index move of +2.0% and a peer median of +0.0%, about 13 points are left over; 0.7× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN −1.6 · Venture +2.4
23
week to 8 Nov 2024
−13.0%
+4.8%
+2.2%
−15.2%
Residual
Weekly window, 2024-11-01 to 2024-11-08: against an index move of +4.8% and a peer median of +2.2%, about 15 points are left over. No filing beyond routine notices inside the window. Addvalue +20.0 · ISDN +1.6 · Venture +2.2
24
3 Feb 2025
+5.6%
−0.8%
+0.0%
+5.6%
Residual
Against an index move of −0.8% and a peer median of +0.0%, about 6 points are left over; 39.3× median volume. Followed the filing “Request for Lifting of Trading Halt :: REQUEST FOR LIFTING OF TRADING HALT ”, released 31 Jan 2025, 19:13. Addvalue +0.0 · ISDN −1.6 · Venture +0.6
25
6 Feb 2025
+6.1%
+0.4%
+0.0%
+6.1%
Residual
Against an index move of +0.4% and a peer median of +0.0%, about 6 points are left over; 15.3× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −9.1 · ISDN +0.0 · Venture +1.4
26
5 May 2025
−5.7%
+0.2%
+0.0%
−5.7%
Residual
Against an index move of +0.2% and a peer median of +0.0%, about 6 points are left over; 0.2× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −11.1 · ISDN +0.0 · Venture +0.4
27
30 Jun 2025
−5.5%
−0.1%
−0.4%
−5.0%
Residual
Against an index move of −0.1% and a peer median of −0.4%, about 5 points are left over; 1.2× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN −1.6 · Venture −0.4
28
25 Jul 2025
+10.6%
−0.3%
+0.3%
+10.3%
Residual
Against an index move of −0.3% and a peer median of +0.3%, about 10 points are left over; 5.3× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN +5.5 · Venture +0.3
29
week to 25 Jul 2025
+8.7%
+1.7%
+16.7%
−8.0%
Residual
Weekly window, 2025-07-18 to 2025-07-25: against an index move of +1.7% and a peer median of +16.7%, about 8 points are left over. The week included the filing “General Announcement :: NO QUESTIONS RECEIVED FROM SHAREHOLDERS RELATING TO AGM TO BE HELD ON 25 JULY 2025” (18 Jul 2025, 17:52). Addvalue +18.8 · ISDN +16.7 · Venture +0.1
30
9 Sep 2025
+6.4%
−0.2%
+0.0%
+6.4%
Residual
Against an index move of −0.2% and a peer median of +0.0%, about 6 points are left over; 13.4× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +0.0 · ISDN −1.2 · Venture +0.9
31
17 Sep 2025
+9.4%
−0.3%
−0.8%
+10.2%
Residual
Against an index move of −0.3% and a peer median of −0.8%, about 10 points are left over; 11.6× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −6.7 · ISDN +0.0 · Venture −0.8
32
week to 19 Sep 2025
+16.9%
−1.0%
+1.3%
+15.5%
Residual
Weekly window, 2025-09-12 to 2025-09-19: against an index move of −1.0% and a peer median of +1.3%, about 16 points are left over. No filing beyond routine notices inside the window. Addvalue +7.7 · ISDN −2.3 · Venture +1.3
33
23 Sep 2025
+30.9%
+0.1%
+0.8%
+30.2%
Residual
Followed the subscription agreement filed at 19:00 on 22 September, after that day's close: 15,000,000 new shares to an existing shareholder at S$0.20, a 1.6% discount to the day's VWAP of S$0.2032, raising S$3.0m, with S$2.0m earmarked for investments and M&A and S$950,000 for Age-Tech working capital. The index rose 0.1% and the peer median 0.8%, so about 30 points survive both controls, on 24× median volume. The S$0.275 close was 37.5% above the subscription price. The shares fell 9.1% the next session and a further 8.0% on 26 September, to S$0.23, before the larger move of 29 September. Addvalue −3.7 · ISDN +1.2 · Venture +0.8
34
29 Sep 2025
+37.0%
+0.1%
+0.6%
+36.4%
Residual
The largest single-session gain in the window, from S$0.23 to S$0.315 on 1,392,400 shares (57× median volume). Nothing was filed between the 26 September close and the open; the only filings that day came after the close, two disclosure notices recording the chairman's spouse buying 20,000 shares on 26 September and 10,000 on 29 September, S$6,900 in all. The index rose 0.1%; Addvalue rose 10.7% while ISDN was flat and Venture rose 0.6%, so the peer median leaves about 36 points unexplained. The tape carries no SGX query on the trading and no halt. The next session gave back 7.9%, and the one after rose 22.4%. Addvalue +10.7 · ISDN +0.0 · Venture +0.6
35
1 Oct 2025
+22.4%
+0.5%
+1.3%
+21.1%
Residual
The third 20%-plus session in seven, from S$0.29 to S$0.355 on 501,500 shares (21× median volume), with nothing filed since the two small disclosure notices of 29 September. The index rose 0.5% and the peer median 1.3%, leaving about 21 points; Addvalue, one of the three peers, rose 14.3% the same day, its third double-digit session running, while ISDN was flat and Venture rose 1.3%. The shares added 4.2% the next session, to S$0.37, and eased 2.7% on 3 October. Addvalue +14.3 · ISDN +0.0 · Venture +1.3
36
week to 3 Oct 2025
+56.5%
+3.4%
+3.3%
+53.3%
Residual
Weekly window, 26 September to 3 October: S$0.23 to S$0.36, built from the sessions of 29 September (+37.0%) and 1 October (+22.4%) with 7.9% given back between them. No filing sits inside the week beyond two disclosure notices of small purchases by the chairman's spouse; the subscription had been announced on 22 September, before the window. The index rose 3.4% and the peer median 3.3%, leaving about 53 points; the median does not show Addvalue, which rose 50.0% over the same five sessions while ISDN rose 1.2% and Venture 3.3%. Read against Addvalue alone rather than the median, about six points would be left over. Addvalue +50.0 · ISDN +1.2 · Venture +3.3
37
16 Oct 2025
+20.5%
−0.3%
−1.3%
+21.8%
Residual
To S$0.50, the window high, on 462,600 shares (19× median volume), with the index down 0.3% and the peer median down 1.3%, so about 22 points survive both controls. The subscription's completion had been filed at 17:30 on 14 October — 15,000,000 shares issued at S$0.20, issued shares to 278,132,160, the new shares to trade from 17 October — and the session that followed it, 15 October, rose 13.7% (not threshold-detected); this session came next, with nothing further filed. From the S$0.21 close of 22 September, the evening the subscription was announced, to this close is a rise of 138%. The shares held S$0.50 the next session and closed October at S$0.48. Addvalue −2.2 · ISDN −1.3 · Venture +1.4
38
week to 17 Oct 2025
+33.3%
−2.2%
−7.3%
+40.6%
Residual
Weekly window, 10 to 17 October: S$0.375 to S$0.50. The week included the completion of the 15,000,000-share subscription at S$0.20, filed at 17:30 on 14 October, and the listing of those shares from 09:00 on 17 October, a session on which the price was unchanged on 402,500 shares. The index fell 2.2% and all three peers fell — Addvalue 8.5%, ISDN 7.3%, Venture 1.6% — so about 41 points survive both controls, the largest weekly residual in the window after the week to 3 October. The 16 October close of S$0.50 is the window high; the shares closed the following week at S$0.495. Addvalue −8.5 · ISDN −7.3 · Venture −1.6
39
4 Mar 2026
−6.1%
−2.1%
−3.9%
−2.2%
Sector-wide
Tracked the sector: against an index move of −2.1% and a peer median of −3.9%, about 2 points are left over. Addvalue −6.8 · ISDN −3.9 · Venture −1.7
40
23 Mar 2026
−10.3%
−2.2%
−2.7%
−7.6%
Residual
Against an index move of −2.2% and a peer median of −2.7%, about 8 points are left over; 2.9× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −4.6 · ISDN −2.7 · Venture −2.7
41
7 May 2026
+5.4%
+0.3%
+3.6%
+1.8%
Sector-wide
Tracked the sector: against an index move of +0.3% and a peer median of +3.6%, about 2 points are left over. Addvalue +3.6 · ISDN +5.1 · Venture +2.0
42
15 Jun 2026
−5.6%
+1.0%
+3.9%
−9.4%
Residual
Against an index move of +1.0% and a peer median of +3.9%, about 9 points are left over; 6.2× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +5.0 · ISDN +3.9 · Venture +1.9
43
22 Jun 2026
−7.5%
+0.2%
+2.0%
−9.5%
Residual
Against an index move of +0.2% and a peer median of +2.0%, about 9 points are left over; 0.7× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +2.0 · ISDN +3.4 · Venture +1.3
44
23 Jun 2026
+6.5%
+0.0%
−6.5%
+12.9%
Residual
Against an index move of +0.0% and a peer median of −6.5%, about 13 points are left over; 3.7× median volume. No filing beyond routine notices in the prior three sessions. Addvalue −9.3 · ISDN −6.5 · Venture −1.2
45
17 Jul 2026
−10.4%
−0.5%
−2.1%
−8.4%
Residual
Against an index move of −0.5% and a peer median of −2.1%, about 8 points are left over; 0.1× median volume. Followed the filing “REPL :: Extraordinary/ Special General Meeting :: Voluntary”, released 16 Jul 2026, 17:52. Addvalue −2.1 · ISDN −3.8 · Venture −2.0
46
20 Jul 2026
+6.7%
−0.2%
+0.8%
+5.9%
Residual
Against an index move of −0.2% and a peer median of +0.8%, about 6 points are left over; 0.0× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +4.3 · ISDN +0.8 · Venture −0.1
47
29 Jul 2026
−8.6%
+1.7%
−0.8%
−7.8%
Residual
Followed the completion of the placement, filed at 18:32 on 28 July after that day's close: all 66,667,000 placement shares issued at S$0.225, gross proceeds about S$15.0m and net about S$14.5m, the new shares 19.3% of an enlarged 353,724,025 and due to trade from 09:00 on 30 July. The index rose 1.7% and the peer median fell 0.8%, leaving about eight points to the filing, on 292,700 shares (12× median volume). The two prior sessions had already fallen 6.3% and 3.3%, on 280,700 and 70,500 shares. The close of S$0.265 was four cents above the placement price. Addvalue +0.7 · ISDN −0.8 · Venture −1.0
48
30 Jul 2026
−11.3%
−0.7%
−1.6%
−9.8%
Residual
The first day of trading in the 66,667,000 placement shares, from 09:00 as the 28 July completion announcement had scheduled; the new shares were 19.3% of the enlarged capital and had been placed at S$0.225. The session traded 882,100 shares (36× median volume) and closed at S$0.235. The index fell 0.7% and the peer median 1.6% — Addvalue 3.4%, ISDN 1.6%, Venture 1.0% — leaving about ten points. The shares eased a further 2.1% to S$0.23 the next session and closed at S$0.225, the placement price, on 4 August, before the 17.8% rise of 5 August. Addvalue −3.4 · ISDN −1.6 · Venture −1.0
49
week to 31 Jul 2026
−28.1%
+0.7%
−4.4%
−23.7%
Residual
Weekly window, 24 to 31 July: S$0.32 to S$0.23, with falls in each of the five sessions — 6.3%, 3.3%, 8.6%, 11.3% and 2.1%. The week included the completion of the placement, filed at 18:32 on 28 July — all 66,667,000 shares placed at S$0.225 for gross proceeds of about S$15.0m, taking issued shares from 287,057,025 to 353,724,025 — and the first day of trading in those shares on 30 July, the session of the largest fall, on 882,100 shares. It also included the 24 July responses to shareholders' questions, which put the order book at about S$106.3m at 30 June, and the AGM of 31 July, at which every resolution passed. The index rose 0.7%; Addvalue fell 5.3%, ISDN 4.4% and Venture 1.3%, so about 24 points survive both controls. The 31 July close was half a cent above the placement price. Addvalue −5.3 · ISDN −4.4 · Venture −1.3
50
5 Aug 2026
+17.8%
−0.6%
+1.4%
+16.4%
Residual
Against an index move of −0.6% and a peer median of +1.4%, about 16 points are left over; 591.5× median volume. No filing beyond routine notices in the prior three sessions. Addvalue +1.4 · ISDN +3.8 · Venture +0.9
51
week to 7 Aug 2026
+15.2%
+1.2%
+1.4%
+13.8%
Residual
Weekly window, 2026-07-31 to 2026-08-07: against an index move of +1.2% and a peer median of +1.4%, about 14 points are left over. The week included the filing “REPL :: Annual General Meeting :: Voluntary” (31 Jul 2026, 18:05). Addvalue +1.4 · ISDN +0.0 · Venture +7.5
Key developments: sources, timing and notes
23 Aug 2023 · Contract award: smart-metering maintenance and billing contract worth up to about S$4.8m; order book lifted 25% to about S$106.1m.AnnouncementReaction (next session, 24 Aug): NXR +0.0% · STI +0.2% · peers +0.0%Source: SGX announcement, 23 Aug 2023
25 Sep 2023 · Business update presentation: order book S$106.1m as of August 2023, against FY2023 revenue of S$25.6m.Business updateReaction (next session, 26 Sep): NXR +0.0% · STI −0.0% · peers +0.0%Source: Investor presentation, 25 Sep 2023
14 Nov 2023 · 1H FY2024 results (six months to 30 Sep 2023): revenue up 1.2% to S$17.3m, net profit down 88% to S$0.3m; order book S$100.4m.ResultsReaction (next session, 15 Nov): NXR +0.0% · STI +0.9% · peers +1.5%Source: SGX announcement, 14 Nov 2023
7 Dec 2023 · Results webinar deck: S$37.9m of the S$100.4m order book falls due within a year, S$54.7m in one to five years.Business updateReaction (next session, 8 Dec): NXR −4.8% · STI +1.2% · peers +1.5% · 0.1× median volumeSource: Investor deck, 7 Dec 2023
15 Mar 2024 · Product launch: subsidiary BOP Pte Ltd launches the 'Buddy of Parents' BOP Button, an emergency button for seniors backed by a 24/7 response centre.AnnouncementSource: SGX announcement, 15 Mar 2024
17 Apr 2024 · Contract award: Roots Communications wins mobile-network engineering works worth up to about S$10.7m over 36 months; order book about S$93.5m.AnnouncementReaction (next session, 18 Apr): NXR +7.1% · STI +1.0% · peers −0.6% · 1.0× median volumeSource: SGX announcement, 17 Apr 2024
27 May 2024 · FY2024 results (year to 31 Mar 2024): revenue up 81.5% to S$46.4m on a full year of Roots, net profit down 21.9% to S$2.8m; final dividend cut to 0.22 cents from 0.28.ResultsReaction (next session, 28 May): NXR −9.1% · STI +0.4% · peers −1.6% · 2.0× median volumeSource: SGX announcement, 27 May 2024
11 Nov 2024 · 1H FY2025 results (six months to 30 Sep 2024): revenue down 1% to S$17.1m and net profit down 57% to S$122,000; order book S$83.5m.ResultsReaction (next session, 12 Nov): NXR +0.0% · STI −0.7% · peers +0.0%Source: SGX announcement, 11 Nov 2024
31 Jan 2025 · Contract award: GovTech Wireless Alert Alarm System front-end contract that the company projects at S$50m over ten years, plus a five-year extension option of up to S$30m; order book to about S$130m.AnnouncementReaction (next session, 3 Feb): NXR +5.6% · STI −0.8% · peers +0.0% · 83.8× median volumeSource: SGX announcement, 31 Jan 2025 · Request for trading halt, 27 Jan 2025 · Press release, 3 Feb 2025
3 Feb 2025 · Share buy-back: 81,000 shares bought at S$0.1897 under the July 2024 mandate, taking treasury shares to 258,100.Corporate actionSource: Daily buy-back notice, 3 Feb 2025
23 May 2025 · Profit guidance: FY2025 net loss of about S$1.8m expected against a restated S$2.6m profit, after a S$3.0m fair-value charge on the Roots earn-out; revenue S$34.6m against S$45.6m.Business updateReaction (next session, 26 May): NXR +1.7% · STI −0.2% · peers +0.7% · 1.4× median volumeSource: SGX announcement, 23 May 2025
29 May 2025 · FY2025 results (year to 31 Mar 2025): revenue down 24% to S$34.6m, net loss S$1.8m after the S$3.0m Roots earn-out charge, no dividend; FY2024 restated for a fabricated sale.ResultsReaction (next session, 30 May): NXR −2.2% · STI −0.6% · peers +0.0% · 1.0× median volumeSource: SGX announcement, 29 May 2025
9 Jun 2025 · Grant: BOP Pte Ltd wins the DBS Foundation Impact Beyond Award with S$1m committed over two years; the alert button is in over 10,000 senior households.AnnouncementReaction (next session, 10 Jun): NXR +0.0% · STI −0.1% · peers +1.0%Source: Press release, 9 Jun 2025
22 Sep 2025 · Placement: 15,000,000 new shares to an existing shareholder at S$0.20 for S$3.0m, a 1.6% discount to the day's VWAP of S$0.2032.Corporate actionReaction (next session, 23 Sep): NXR +31.0% · STI +0.1% · peers +0.8% · 23.9× median volumeSource: SGX announcement, 22 Sep 2025
10 Nov 2025 · 1H FY2026 results (six months to 30 Sep 2025): revenue up 12% to S$19.1m and net profit up to S$0.6m from S$0.1m, helped by the DBS grant; order book S$115.2m.ResultsReaction (next session, 11 Nov): NXR +1.0% · STI +1.2% · peers +0.0% · 1.4× median volumeSource: SGX announcement, 10 Nov 2025
30 Jan 2026 · Non-binding term sheet to buy a Singapore therapeutic-meals company for S$11.2m, about S$7.2m of it in cash and the rest in new shares to its founder.Corporate actionReaction (next session, 2 Feb): NXR −3.6% · STI −0.3% · peers −2.3% · 0.5× median volumeSource: SGX announcement, 30 Jan 2026
30 Apr 2026 · SPA to acquire The Gentle Group for S$11.2m, mostly in cash plus 8,924,865 new shares at S$0.319; the target had net tangible assets of about S$2.1m and net profit of about S$0.2m.Corporate actionReaction (next session, 1 May): NXR +0.0%Source: SGX announcement, 30 Apr 2026 · Press release, 30 Apr 2026
26 May 2026 · Profit guidance: FY2026 revenue up 19% to S$41.3m and operating profit up 150% to S$3.6m, but a net loss of S$1.6m after a final S$4.4m Roots earn-out charge.Business updateReaction (next session, 27 May): NXR +0.0% · peers +0.0%Source: SGX announcement, 26 May 2026
29 May 2026 · FY2026 results (year to 31 Mar 2026): revenue up 19% to S$41.3m, operating profit up 150% to S$3.6m, net loss S$1.6m after the S$4.4m earn-out charge; cash S$11.5m, no dividend.ResultsReaction (next session, 2 Jun): NXR +0.0% · STI +1.2% · peers −3.5%Source: SGX announcement, 29 May 2026
30 Jun 2026 · Placement of up to 66,667,000 new shares at S$0.225 to raise about S$15.0m, about 32% below the S$0.33 VWAP (computed) and so subject to an EGM under Catalist Rule 811(3).Corporate actionReaction (next session, 1 Jul): NXR +0.0% · STI −0.2% · peers +1.4% · 1.2× median volumeSource: SGX announcement, 30 Jun 2026 · Results of EGM, 16 Jul 2026
1 Jul 2026 · Gentle Group acquisition completed: about S$7.04m of cash paid (computed) and 8,924,865 shares issued at S$0.319, taking issued shares to 287,057,025; order book about S$127m.Corporate actionReaction (next session, 2 Jul): NXR +0.0% · STI +1.1% · peers −0.4%Source: Completion announcement, 1 Jul 2026 · Press release, 2 Jul 2026
15 Jul 2026 · Audited FY2026 differs from the May release: net loss S$1.795m against S$1.601m unaudited after the Roots earn-out charge rose S$194,000 to S$4.626m.AnnouncementSource: SGX announcement, 15 Jul 2026
15 Jul 2026 · Board change: lead independent director and audit-committee chairman Ang Swee Tian retires at the 31 July 2026 AGM; the board shrinks to four, two of them independent.BoardSource: SGX announcement, 15 Jul 2026
28 Jul 2026 · Placement completed: all 66,667,000 shares placed at S$0.225 for gross proceeds of about S$15.0m; issued shares rise to 353,724,025.Corporate actionReaction (next session, 29 Jul): NXR −8.6% · STI +1.7% · peers −0.8% · 7.7× median volumeSource: Completion announcement, 28 Jul 2026 · Press release, 28 Jul 2026
19 Aug 2026 · Roots earn-out settled at a final S$17.43m: a S$9.33m second tranche paid S$5.60m in cash and S$3.73m in 11,219,845 new shares at S$0.3327.Corporate actionReaction (next session, 20 Aug): NXR +0.0% · STI −0.4% · peers −2.6% · 19.1× median volumeSource: SGX announcement, 19 Aug 2026
What you can watch yourself
Every other test on this page waits for the company to file. These do not. Each row is a series you can look up yourself, free, today — with the level this reading was built against, the levels that would put it in question, and what the series cannot tell you.
wireless engineering and solutions — nothing public to watch
Searched the infocomm regulator's telecommunications statistics, the public-sector procurement portal and the satellite-services operators' releases. The revenue is a small number of project awards and government contracts, so a national subscriber or traffic series has no transmission to it; the observable that would matter — the award tape — is the issuer's own filing.
Watchlist reviewed on 2026-08-27; each observation has its own date above. This watchlist date does not change the company research cutoff. A series moving past a level is a reason to re-read the case, not a recommendation. The same series across every company covered: what you can watch.
Notes and sources
Questions the filings do not answer
What does The Gentle Group earn? iWOW paid S$11.2m — 27% of a year’s revenue. An earlier version of this page said no document disclosed the target’s figures. That was wrong. The sale-and-purchase announcement of 30 April 2026 discloses net profit after tax of about S$0.2m, net tangible assets of about S$2.1m at 31 December 2025, S$149k of profit for the half to September 2025, and a pro-forma effect of +S$183k on group earnings with S$8,806,000 of goodwill recognised — taking pro-forma net tangible assets per share from 5.66 cents to 3.28 cents. What is still not disclosed is the target’s revenue, which is why the chairman’s remark about a revenue compound growth rate of about 51% from FY2022 to FY2025 cannot be anchored to an absolute figure.
What conditions attach to the S$1.0m deferred consideration? — answered, and an earlier version of this page answered it wrongly. The sale-and-purchase announcement of 30 April 2026 (p.5) makes the S$1.0m unconditional. A revenue-growth key performance indicator of at least 20% for the year to 31 March 2027, measured against calendar 2025, determines only when it is paid: 31 October 2027 if the target is met, 30 April 2028 if it is not. This page previously described it as performance-linked consideration of the same kind that produced the last two years of reported losses. That was wrong: the amount does not vary with performance, and it is a deferred payment rather than an earn-out.
At what price will the ROOTS consideration shares be issued? — answered. The 19 August announcement fixed the issue price at S$0.3327 and the number at 11,219,845. The remaining question is allotment timing: those shares were not in the issued-share count reported on 24 August.
Was the restated FY2024 profit used in the earn-out calculation? The earn-out runs on audited net profit after tax over a window that contains the fabricated sale. The calculation has never been published.
Was the September 2025 subscription done the same way as the June 2026 placement? The June 2026 placement was struck at S$0.225, which the extraordinary-general-meeting circular states is a discount of approximately 31.8% to the volume-weighted average price, and which proceeds under the Rule 811(3) exemption — the provision that disapplies Catalist’s 10% discount limit where shareholders approve the issue. That is why a meeting was convened. The earlier issue was struck at S$0.20 against a S$0.355 close on 1 October 2025; its announcement was not retrievable, so whether it used the same route is not established here.
What is the order book, exactly? It is issuer-defined and unaudited, but it is better disclosed than most: the FY2026 annual report carries an estimated fulfilment horizon in three time buckets, a segment split, a recurring versus non-recurring split, and an “as of 30 June” series across FY2024 to FY2026. Two figures appear at two dates — S$106.3m as of June 2026 in the financial highlights and approximately S$107m as at 30 April 2026 in the chief executive’s statement — and the basis for the difference is not stated.
Who are the customers? Seven customers accounted for about 62% of trade receivables at FY2026 (six and 61% a year earlier). None is named.
Download
A print-ready PDF of this page, for reading away from the screen: iWOW Technology evidence library (PDF). It carries the same content as this page — the as-filed record, segment economics, the FY2024 restatement, the receivable book, funding and the share count, ownership, the share price and open questions — and the same omissions: no rating, no fair value, no forecast.
This page is built from iWOW’s own filings: the annual reports for FY2022 to FY2026 — complete since the April 2022 listing, with FY2026 audited by Forvis Mazars LLP and signed on 14 July 2026 — the FY2026 results announcement, the half-year results announcements for 1H FY2023 to 1H FY2026, the Catalist offer document, the extraordinary-general-meeting circular of 1 July 2026, the annual-general-meeting minutes for FY2025, the contract-award announcements of 21 July 2023 (approximately S$20m) and 23 August 2023 (up to approximately S$4.8m), and the ROOTS non-binding term sheet of 19 September 2022.
Two version traps. FY2024 exists on an as-reported and a restated basis; the restated basis is used throughout. FY2026 exists on an unaudited and an audited basis; the audited basis is used throughout. The unaudited FY2026 announcement showed a S$4,432k earn-out charge, a S$842k loss before tax and a 0.59-cent loss per share against the audited S$4,626k, S$1,036k and 0.67 cents.
Latest attachment limitation. The official exchange pages for the 19 August ROOTS determination and 24 August option exercise were indexed, but direct attachment downloads were denied by the exchange edge. Each was attempted through two routes. The filing-derived facts above are reconciled to the issuer’s later share-count disclosure; no blocked attachment is represented as locally captured.
Corrections made during the build. An independent blind review of the underlying pack returned 45 findings, twelve at the highest severity, and each was checked against the primary filing before correction. Two are worth naming here because they were false statements in an earlier draft of this page: that the placement pricing could not be reconciled with Catalist Rule 811, when the circular states the 31.8% discount and the Rule 811(3) exemption on its face; and that the order book carried no disclosed conversion horizon, when the annual report publishes one in three time buckets. Separately, two numeric errors were caught by an inspection of the rendered charts and corrected at source: contract-asset growth was stated as 39% when the figure on the total of current and non-current contract assets is 35.6% (39% was the current-only slice — two different bases); and net cash was stated as S$9.2m including lease liabilities when S$9.2m is the figure excluding them and S$6.8m the figure including them. A third error was introduced while fixing the second and caught on re-render. A basis mismatch between the restated revenue table and the as-reported geography table was caught by an arithmetic identity check during the build and corrected to the restated Malaysian figure.
This page is an evidence library. It contains no rating, no fair value, no forecast and no scenarios, and it is not a recommendation or personalised financial advice. Figures labelled derived are computed from reported figures with the computation stated.
Reader questions & corrections
Ask about this company, challenge a source or suggest a factual correction. Only selected questions that SMID Research has reviewed and answered are published.
Submissions are private by default. Your email is encrypted and never published. Please do not send confidential or inside information, allegations about individuals, promotions, or requests for personalised investment advice.
Behind the lock
A private 24 August monitoring note and understanding sheet exist beyond this page. The earlier workbook, PDFs and deck are retained only in the superseded archive because they do not contain the final share bridge. The current private credit conclusion is NR pending issuer-level liquidity and debt-perimeter evidence. This public page carries no rating or valuation conclusion.
These bounded retrospective corrections clarify specific published facts or calculations. They retain each report's existing research cutoff and do not represent a full refresh or a finding that all possible issues are resolved.
iWOW Technology
Verified Fact. The acquisition agreement records an undertaking for S$5.0m of expansion support, or another agreed amount, through equity, loans, arranged third-party finance or a combination. It specifies a first S$2.0m tranche no later than 30 June 2026. Source basis: Gentle acquisition announcement, section 4.6.1. Limitation: Actual funding and its form are not established here; the undertaking is not assumed to be an additional immediate parent cash payment.
Transcripts
Find available event transcripts in the transcript library.
Titles are from the linked SGX filing, with common words abbreviated. Summaries are written by AI and may contain inaccuracies; refer to the original announcement. Items after 24 August 2026 are not reflected in this page's analysis; earlier items are listed for reference, may not be discussed in it, and may have been updated by later announcements.