Q&M operates dental clinics in Singapore and Malaysia and consolidates the Aoxin healthcare business in China, so clinic economics and acquisition effects must be separated.
Latest figures
In 1H2026 revenue was S$99.5m and company-stated EBITDA was S$19.2m; at 30 June cash was S$119.2m against S$181.5m of borrowings and leases.
Main risk
The central risk is that acquisition accounting, segment mixing and undisclosed covenant headroom overstate the cash resilience of the core dental network.
Next proof
The next test is the next filing's pro-forma segment bridge, operating cash conversion and facility headroom.
This page carries no rating, no fair value, no price target and no view on the shares. It sets out what Q&M has filed, recomputes figures from those filings with the arithmetic shown, and names what the filings do not answer. Information cut-off: 25 August 2026; the latest reported period is 1H2026, released 14 August 2026. The issuer-tape sweep found no parent-company filing after the 16 August EM2AI memorandum of understanding through the cut-off. Evidence marks: (R) reported in a primary filing · (D) derived here by recomputation · (E) third party · (O) opinion.
Evidence balance
The live questionOnce the Aoxin consolidation is stripped out, what do the Singapore and Malaysia clinics earn, and does that cash fund the acquisitions?In 1H2026 the Aoxin consolidation still enters both revenue and segment result with no bridge published, while signed acquisitions schedule roughly S$95.5m of near-term cash uses.
What improved
1H2026 revenue rose 12.5% to S$99.5m and Malaysia grew 14.4%; once the fall in profit guarantee income is removed from both halves, Singapore grew 0.24% and Singapore plus Malaysia 1.20% rather than shrinking.
What became more demanding
In the same half operating cash fell 16.2% to S$12,563k while core dental segment result grew 5.4% against revenue growth of 13.0%, and the two signed acquisitions carry roughly S$95.5m of scheduled near-term cash uses against cash on hand of S$119.2m.
Strongest alternative explanation
The 195bp margin fall could be a consolidated-mix observation rather than deterioration in the established network, since Aoxin enters both revenue and segment-result lines and the filing provides no bridge; the vendor profit guarantees and cash escrows behind the signed acquisitions could also absorb part of any shortfall.
The decisive missing fact
A pro-forma segment bridge separating Aoxin from the established network, a like-for-like organic revenue series, the closing profit guarantee receivable, and whether facilities available to the Company are committed, would settle it.
Drawn from the evidence on this page: the improvement, the constraint, the benign reading and the fact that would settle it. It states no view on the shares.
About the private research record
Author-only research notes are available through rated view 🔒. They remain private and are not approved for public distribution.
On this page
Business anatomy · operations, customers and cash
Patient care is the hub; dental distribution is a separate sales lane
Clinics and hospitals earn care fees from patients, while distribution supplies equipment and consumables to the group network and other practices.
Read each card by investor role: business line, operating step, customer outcome or cash conversion.
Customer needCare demand
A patient needs treatment
What happensA patient enters the network with a consultation, imaging or treatment need.
Commercial triggerThe patient or payer funds the clinical service.
Business lineClinical network
Dentists deliver the care
What happensQ&M deploys dentists, diagnostics and equipment across clinics and hospitals to diagnose and treat.
How it earnsConsultation, imaging and treatment fees create care revenue.
Business lineDistribution lane
Source equipment and supplies
What happensThe group also sources dental equipment and consumables for its own network and third-party practices.
How it earnsPractices pay for delivered products; this is a product sale, not a patient-care fee.
Revenue engineTwo payers
Collect from patients and practices
What happensClinical cash comes from care recipients, while distribution cash comes from dental practices buying supplies.
How it earnsThe two lanes share a network but have different customers and economics.
Original SMID Research comic. AI-assisted, analyst-directed monochrome artwork depicts the evidenced operating steps of Q&M Dental Group; deterministic captions and dated mix figures state the economics using issuer disclosures available to 2026-08-25. The drawings are representative—not issuer artwork, an exact product or site design, a statement of scale, or a company forecast.
Investor translation
What matters after the operating picture
Four questions connect the business model to cash and balance-sheet risk. This is a factual reading aid, not a valuation or recommendation.
Value lever
Organic clinic owner earnings plus acquisition returns after funding, integration and minority interests.
Cash bottleneck
Deal consideration, clinic expansion and profit-guarantee receivables absorb cash before earnings convert.
Organic clinic margin, acquisition funding, cash conversion and guarantee collections.
Text version of this comic
Customer need · A patient needs treatment A patient enters the network with a consultation, imaging or treatment need. Commercial trigger: The patient or payer funds the clinical service.
Business line · Dentists deliver the care Q&M deploys dentists, diagnostics and equipment across clinics and hospitals to diagnose and treat. How it earns: Consultation, imaging and treatment fees create care revenue.
Business line · Source equipment and supplies The group also sources dental equipment and consumables for its own network and third-party practices. How it earns: Practices pay for delivered products; this is a product sale, not a patient-care fee.
Revenue engine · Collect from patients and practices Clinical cash comes from care recipients, while distribution cash comes from dental practices buying supplies. How it earns: The two lanes share a network but have different customers and economics.
1 · What the company actually is
Q&M runs the largest private dental network in Singapore. At 30 June 2026 it operated 113 dental outlets in Singapore (108 a year earlier) plus one medical outlet, the Q&M College of Dentistry, a dental AI company and a dental equipment and supplies distributor; 36 dental outlets and a distributor in Malaysia; and dental hospitals and polyclinics in Liaoning province held through Aoxin Q&M Dental Group (SGX Catalist: 1D4), which it owns at about 52.6% and consolidates in full. (R)
It listed on 26 November 2009 through a placement of 74,075,000 new shares at S$0.27, raising approximately S$20.0m. It reports half-yearly to a 31 December year end. (R)
The group reports two segments — Core Dental Business (dentistry plus distribution of dental supplies and equipment) and Other Businesses (formerly COVID-19 test kits and laboratory testing, now residual family medicine and aesthetics) — alongside a third Unallocated column carrying corporate costs. This is a mixed-engine group: a clinic network, a wholesale distributor, an education business and a Chinese hospital group inside one reporting-segment pair. Consolidated working-capital and margin ratios across the whole group are not economically meaningful without a bridge, and the company publishes none. (O, on R)
Ownership at 1 April 2026
Holder
Shares
%
Quan Min Holdings Pte. Ltd. — the ultimate parent, direct
528,321,389
55.79%
Dr Ng Chin Siau — direct 6,628,900 plus deemed 528,442,589
—
55.80%
IMC Dynamic Investments Pte. Ltd. (Tsao Pao Chee Group)
64,132,538
6.77%
Held by the public
—
33.93%
Treasury shares
18,824,035
1.988%
Percentages computed on 947,041,312 shares excluding treasury. Dr Ng Chin Siau is Group CEO and holds 49.80% of Quan Min Holdings directly. The Chairman, Mr Tan Teck Koon, is an independent non-executive and is unrelated to him; no Lead Independent Director has been appointed, on the stated basis that the two roles are already separate. Mr Hareesh V Nair was appointed to the board on 29 April 2026 as IMC's nominee. (R — FY2025 annual report, statistics of shareholdings and corporate governance report)
2 · FY2025 was reported with three different profit numbers
Measure, as labelled by the issuer
FY2025
FY2024
Change
Profit attributable to owners (statutory)
9,312
14,264
−35%
Excluding other gains/losses and MTN- and PSP-related expenses
17,010
16,891
+1%
Profit after tax — Core Dental Business
30,426
26,124
+16%
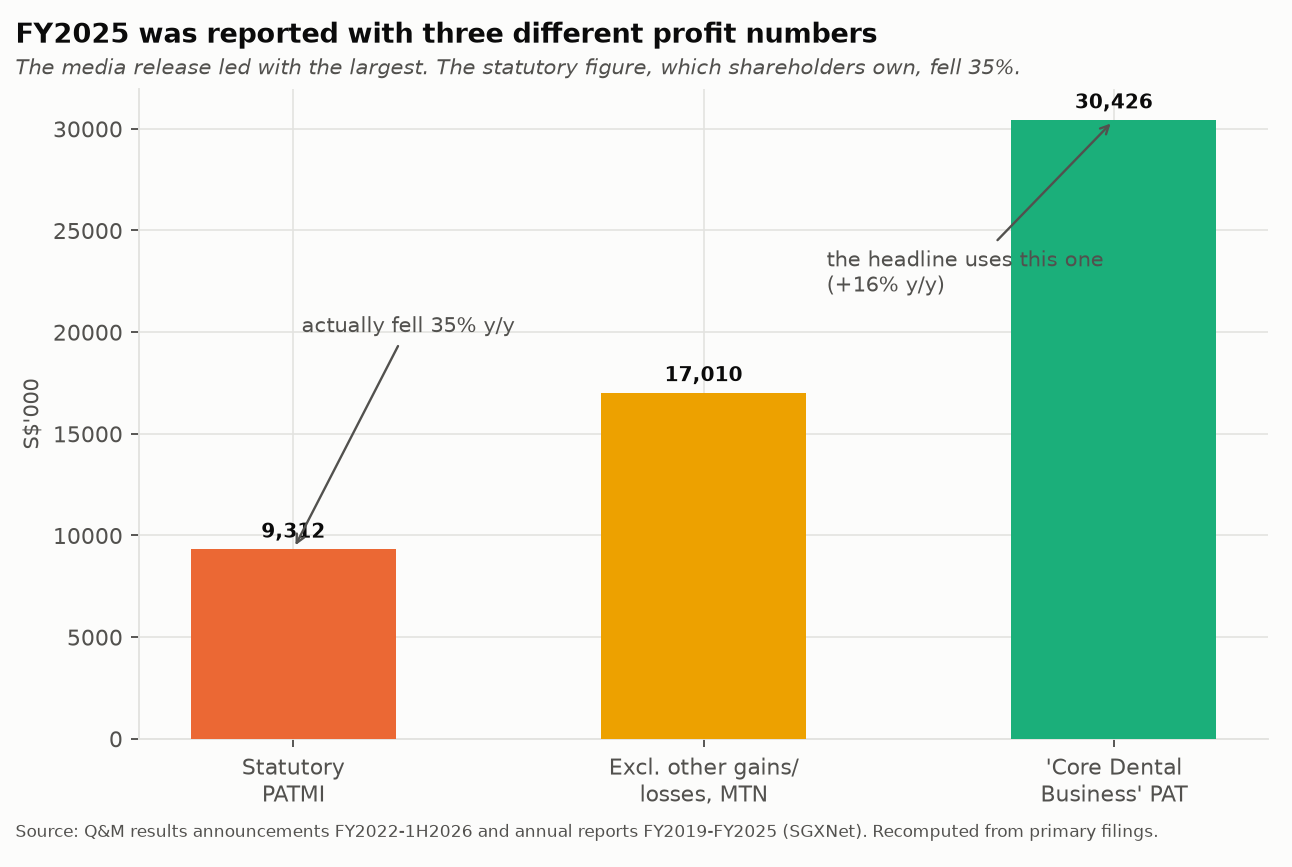
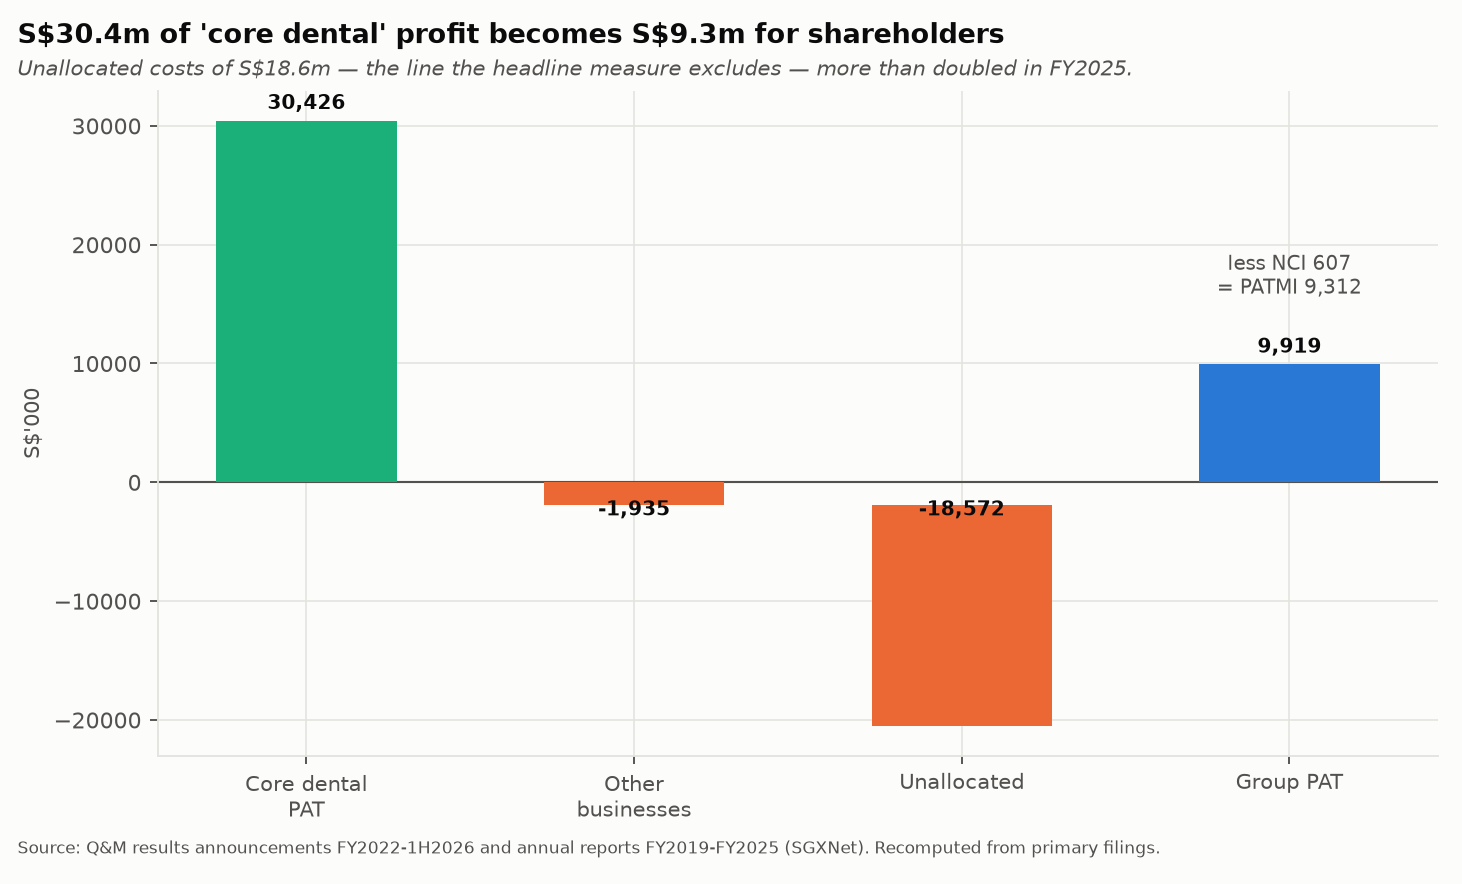
All three appear in the FY2025 media release, whose headline was “Q & M Dental Group Drives 16% Profit Growth.” The statutory figure fell 35%. The gap is not a rounding convention — the bridge is exact, and the residual is zero: (D on R)
Core dental business, profit after tax
30,426
Other businesses, profit after tax
(1,935)
Unallocated
(18,572)
Group profit net of tax
9,919
less non-controlling interests
(607)
Profit attributable to owners
9,312
The Unallocated column more than doubled, from S$(7,100)k to S$(18,572)k — the figure the bridge above carries. It is three lines rather than one: S$(16,020)k of unallocated corporate expenses, S$(2,449)k of unallocated finance costs, being the whole of the Medium Term Note interest and all of it incurred in the second half, and S$(103)k of share of losses from equity-accounted associates. The S$4,156k net loss on consolidating associates into subsidiaries is inside that S$(16,020)k, not additional to it: the annual report splits the same amount into S$(11,864)k of corporate expenses, a S$(19,820)k net loss on deemed disposal and a S$15,664k bargain purchase gain. FY2024 reads S$(7,100)k as a column against S$(7,234)k on the corporate-expense line alone, the difference being that year’s S$134k share of associate profit. The fastest-growing cost line in the group is the one the headline measure excludes. (R + D)
All three are the company's own labels for the same year. The media release led with the largest.S$30.4m of core dental profit becomes S$9.3m for shareholders once Other Businesses, Unallocated and minorities are deducted.
3 · The core business, on the only clean perimeter the company discloses
The segment table is contaminated by the Aoxin consolidation from June 2025 — Aoxin enters both the revenue and the segment-result lines and no bridge is given. The geographic table is not contaminated in the same way, and is reproduced here as filed. (R — 1H2026 results, note 2E)
Revenue, S$'000
1H2026
1H2025
Change
Singapore
78,922
79,954
−1.3%
Malaysia
6,563
5,738
+14.4%
Singapore + Malaysia
85,485
85,692
−0.2%
People's Republic of China
13,977
2,686
+420%
Group total
99,462
88,378
+12.5%
PRC revenue rose because Aoxin became a subsidiary in June 2025, not because it grew; the filing says the core-dental increase was mainly due to that consolidation. (R)
The Singapore figure does not survive netting, and both readings belong on the page. Revenue includes a profit guarantee income line (section 5) of S$81k in 1H2026 against S$1,303k in 1H2025 — a fall of S$1,222k, which is larger than the S$1,032k decline in the Singapore line. Removing it from both periods: (D on R)
1H2026 vs 1H2025
As reported
Ex profit-guarantee income
Singapore
−1.29%
+0.24%
Singapore + Malaysia
−0.24%
+1.20%
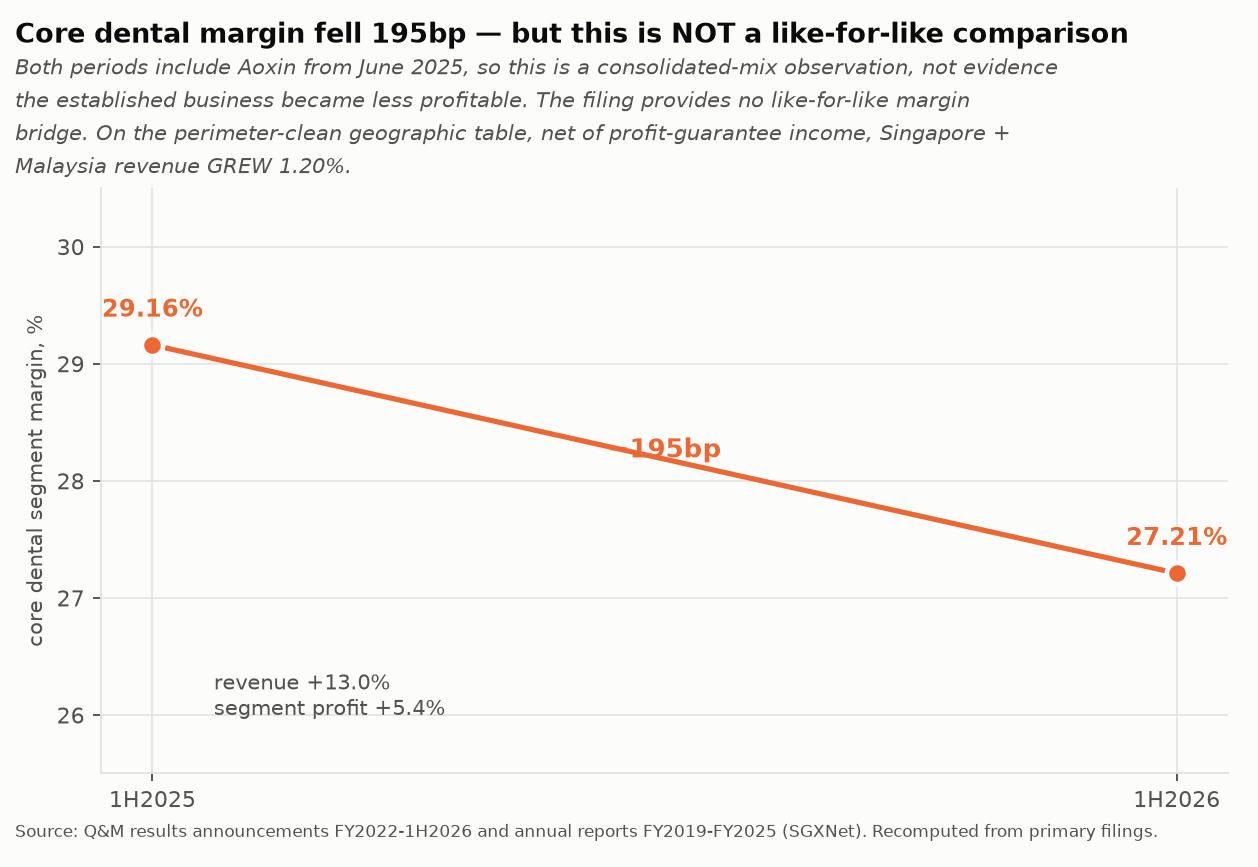
On the company's own segment disclosure, read as consolidated: core dental revenue +13.0%, core dental segment result +5.4%, margin −195bp to 27.21%, and net cash from operating activities −16.2% to S$12,563k. Revenue growth is 2.4x segment-profit growth and operating cash moved the opposite way to the headline. Because Aoxin enters both lines, the 195bp is a consolidated-mix observation and is not evidence that the established business became less profitable. (R + D)
The margin comparison is not like-for-like: both periods include Aoxin from June 2025 and the filing provides no bridge.
Industry context. Singapore's private-sector registered-dentist population grew from 980 in 2008 to 1,965 in 2022, a CAGR of 5.09%. Q&M's frequently-cited core-dental revenue CAGR over FY2021–FY2025 is approximately 5.0%, but that series splices two segment definitions and two consolidation perimeters and is an upper bound rather than a rate. On the available evidence the network grew with its industry; a share gain is not visible in the data, and the Ministry of Health series ends at 2022 so the comparison cannot be run on the most recent three years. (E — MOH registered-dentist counts via data.gov.sg; D on R)
4 · Track record — revenue has not recovered its FY2021 peak
S$'000
FY2021
FY2022
FY2023
FY2024
FY2025
Total revenue
205,599
181,214
182,723
180,674
197,226
Profit, net of tax
39,358
11,856
11,073
12,693
9,919
Attributable to owners
—
—
—
14,264
9,312
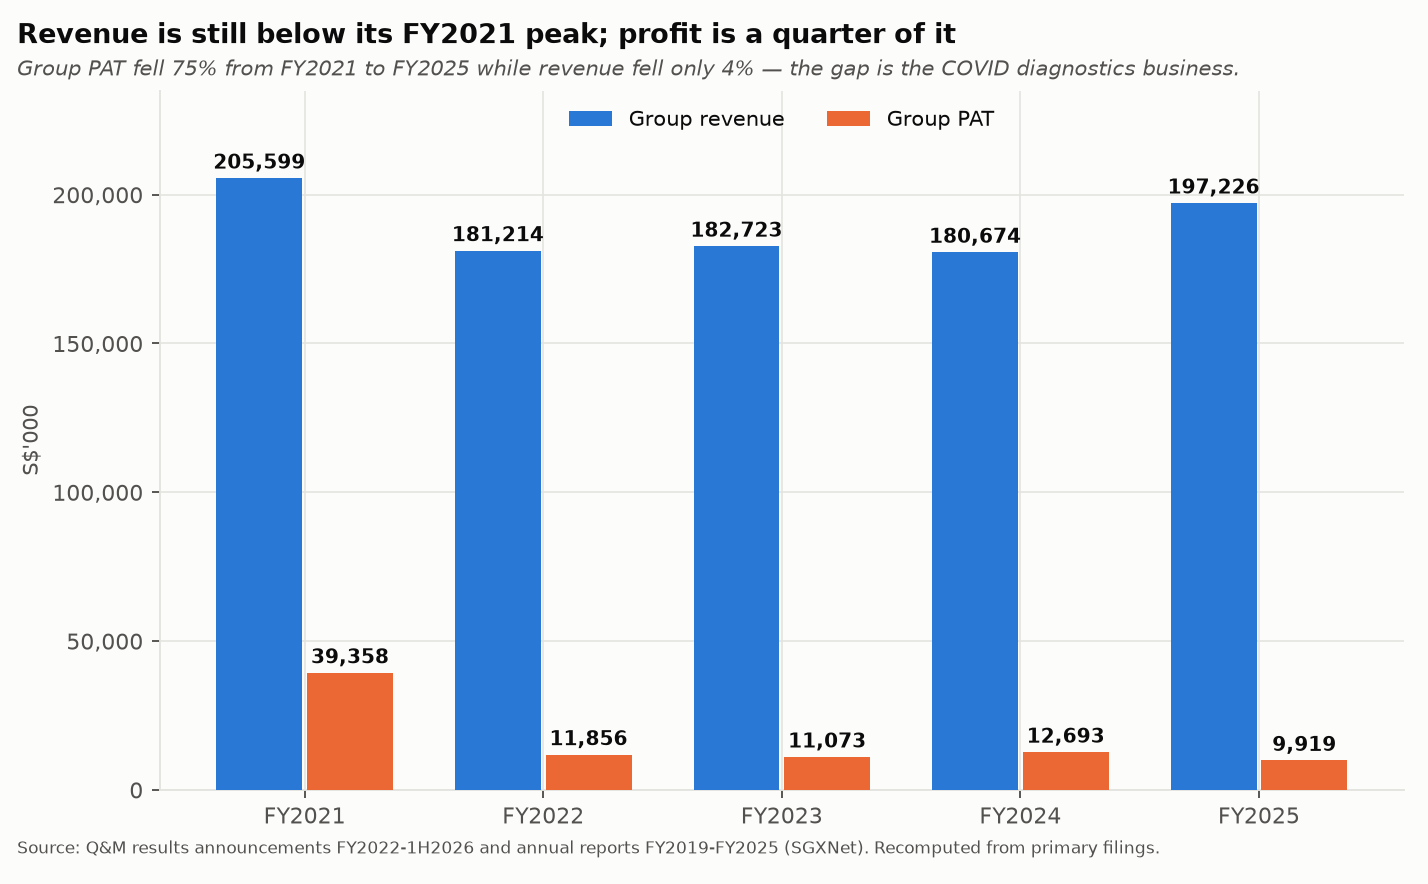
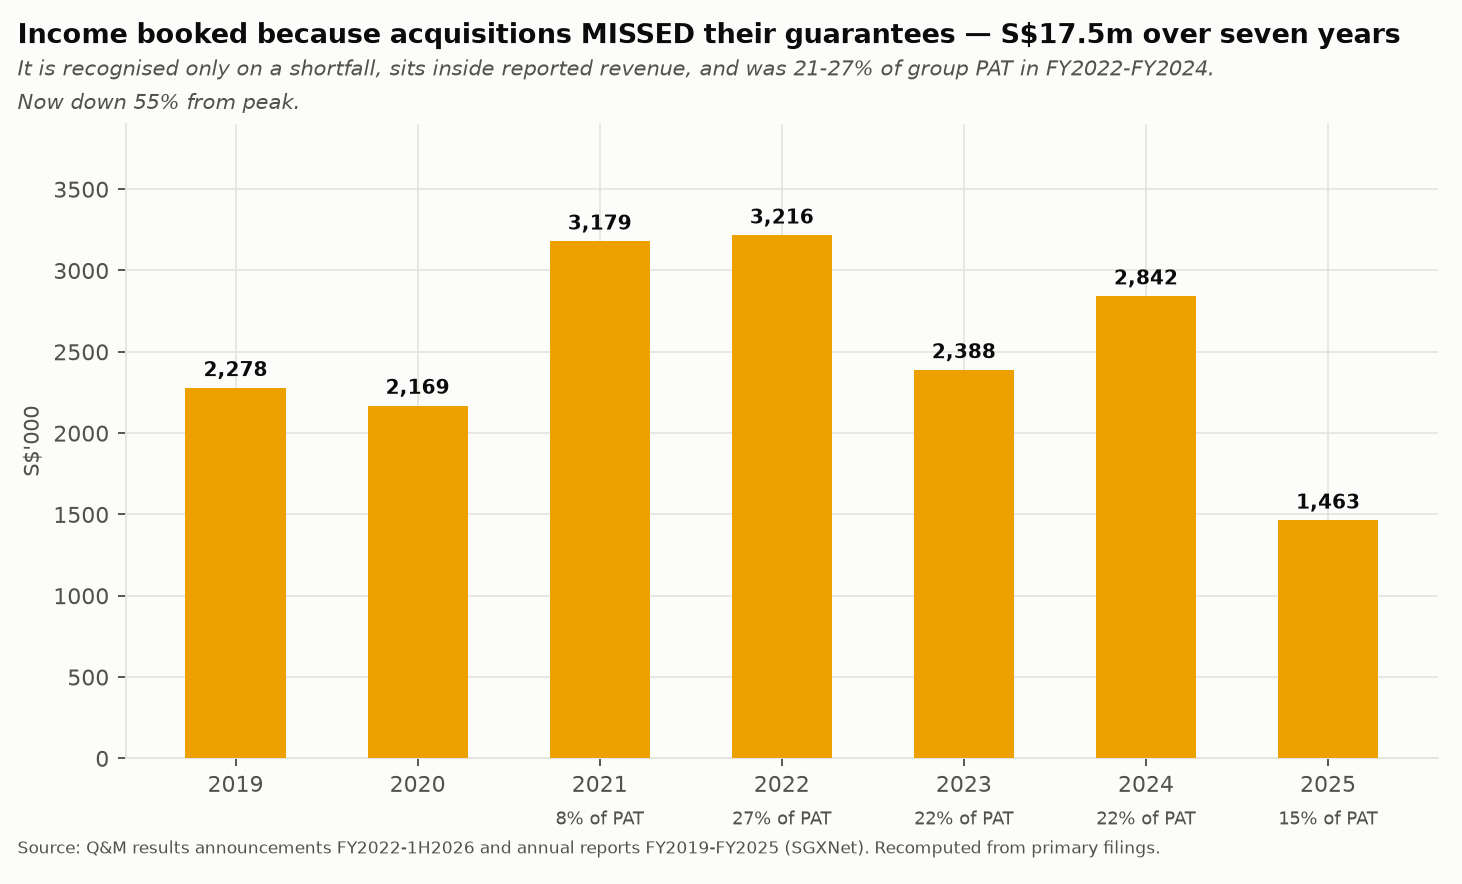
Revenue peaked at S$205.6m in FY2021 and was S$197.2m in FY2025 — still below peak five years later. Group profit went S$39.4m to S$9.9m, −75%. The entire gap is Other Businesses: COVID-era diagnostics revenue of S$45.4m earning a S$22.4m segment result (approximately 49% margin) has become S$2.2m of revenue at a S$(0.9)m loss. FY2024 is shown on the restated basis per note 18 of the FY2025 filing; FY2021–FY2023 sit on an earlier segment-presentation basis (section 15). (R + D)
Revenue fell 4% from its FY2021 peak; profit fell 75%. The gap is the COVID diagnostics business, which no longer exists at scale.
5 · A line inside revenue that exists only when an acquisition misses
Q&M reports profit guarantee income as a line within revenue. The stated accounting policy is identical across FY2019–FY2025: (R)
profit guarantee income is recognised when there is a shortfall between the profit amount guaranteed by the vendors or shareholders of the subsidiaries and the actual performance of the acquired subsidiaries
S$'000
FY2019
FY2020
FY2021
FY2022
FY2023
FY2024
FY2025
Profit guarantee income
2,278
2,169
3,179
3,216
2,388
2,842
1,463
as % of group profit net of tax
—
—
8%
27%
22%
22%
15%
S$17.5m cumulative over seven years, and 21–27% of group profit in FY2022–FY2024. In 1H2026 the line fell to S$81k, down 94%. The FY2025 annual report attributes part of that year's revenue shortfall to “a S$1.4 million reduction in profit guarantee income.” (D on R)
Recognised only on a shortfall, sitting inside reported revenue. S$17.5m over seven years, now down 55% from its FY2022 peak.
This line also sits inside the revenue figure the company headlines as core dental.
Two different FY2025 “core dental revenue” figures are in circulation, and both are as filed.
The revenue note reports core dental services of S$190,792k; the segment note reports a
Core Dental Business total of S$195,002k. The S$4,210k difference is the remainder of the
revenue note attributable to that segment, and it reconciles exactly:
FY2025 revenue, as filed — the revenue note reconciled to the segment note (S$’000)
Revenue note (note 3)
FY2025
Core dental services
190,792
Other services
2,107
Profit guarantee income
1,463
Rental income
443
Other income
2,421
Total revenue
197,226
less Other Businesses, per the segment note
(2,224)
Core Dental Business, per the segment note
195,002
The consequence is arithmetic, not interpretation: the S$1,463k of profit guarantee income
shown above is inside the S$195,002k, together with rental and other income. A growth rate
computed on the segment figure is therefore not computed on dental trading revenue alone. Both figures
are correct; they are different lines, and which one a reader is quoting determines what the growth rate
measures. (D on R — FY2025 results, revenue note 3 and the segment note)
6 · The receivable behind that income, and its Key Audit Matter
Much of the income above has not been collected. At 31 December 2025: (R — FY2025 annual report, auditor's report Key Audit Matter (b) and note 19)
At 31 December
Group 2025
Company 2025
Group 2024
Company 2024
Profit-guarantee receivables, net of allowance
15,123
12,890
15,984
14,497
Of the S$15,123,000 group balance, S$11,243,000 is due from a subsidiary's former director. It is secured by escrow and share-security agreements over that person's shares in the subsidiary. After the March 2026 enforcement recovers S$3,857,000, the accounts state he will continue to owe approximately S$7,386,000, and that:
There are uncertainties over the recoverability of the remaining receivables of about $7,386,000 in full if the subsidiary's former director does not have the financial ability to repay this amount.
The auditors made the impairment assessment a Key Audit Matter. For scale, S$7,386,000 is 79% of FY2025 profit attributable to owners of S$9,312,000. (D on R)
Two facts that cut the other way and belong beside it. First, the auditors record that management concluded no impairment allowance is required, so nothing has been provided against the amount described as uncertain. Second, the recovery case is broader than the pledged shares: the audit procedures reference a valuation report on a property identified by management as a potential source of recovery, and external legal counsel's opinion on the group's ability to pursue the claim under Singapore law and the enforceability of any resulting judgment in the PRC. Neither is quantified in the accounts. (R)
7 · The network — outlet counts on a consistent basis
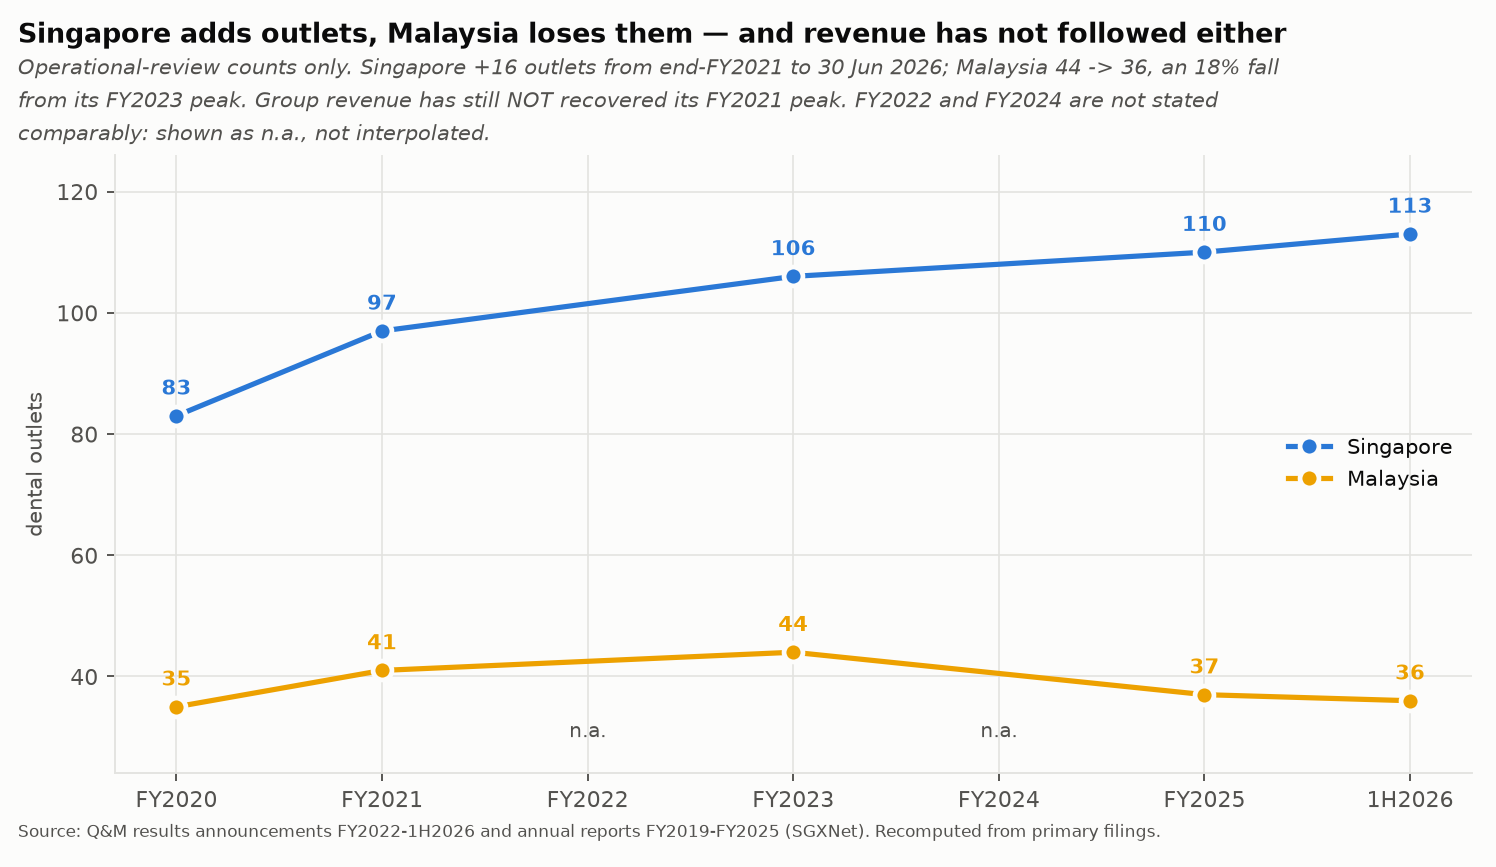
The annual reports give outlet counts in two places — an undated corporate-profile blurb and the operational review — and they do not always agree. The operational-review counts are used here. FY2022 and FY2024 are not stated comparably in either place and are shown as not available rather than interpolated. (R)
As at 31 December
FY2020
FY2021
FY2022
FY2023
FY2024
FY2025
30 Jun 2026
Singapore dental outlets
83
97
n.a.
106
n.a.
110
113
Malaysia dental clinics
35
41
n.a.
44
n.a.
37
36
Singapore added 16 outlets between the end of FY2021 and 30 June 2026. Malaysia has fallen 44 to 36, an 18% reduction from its FY2023 peak. Over the same window group revenue has not recovered its FY2021 peak (section 4). (D on R)
No revenue-per-outlet series is published here, deliberately. The available revenue numerator includes the distribution business, profit-guarantee income and, from FY2025, consolidated Aoxin — none of which is generated by a Singapore or Malaysia dental outlet. A ratio built on it would not measure outlet productivity. The company also discloses no opened / acquired / closed roll-forward, so the mechanism behind the net movement is not in evidence. (O, on R)
Operational-review counts only. Gaps are shown as n.a. rather than interpolated.
8 · Balance sheet, as filed
At 30 June 2026, with every identity recomputed and the residual zero: (R + D)
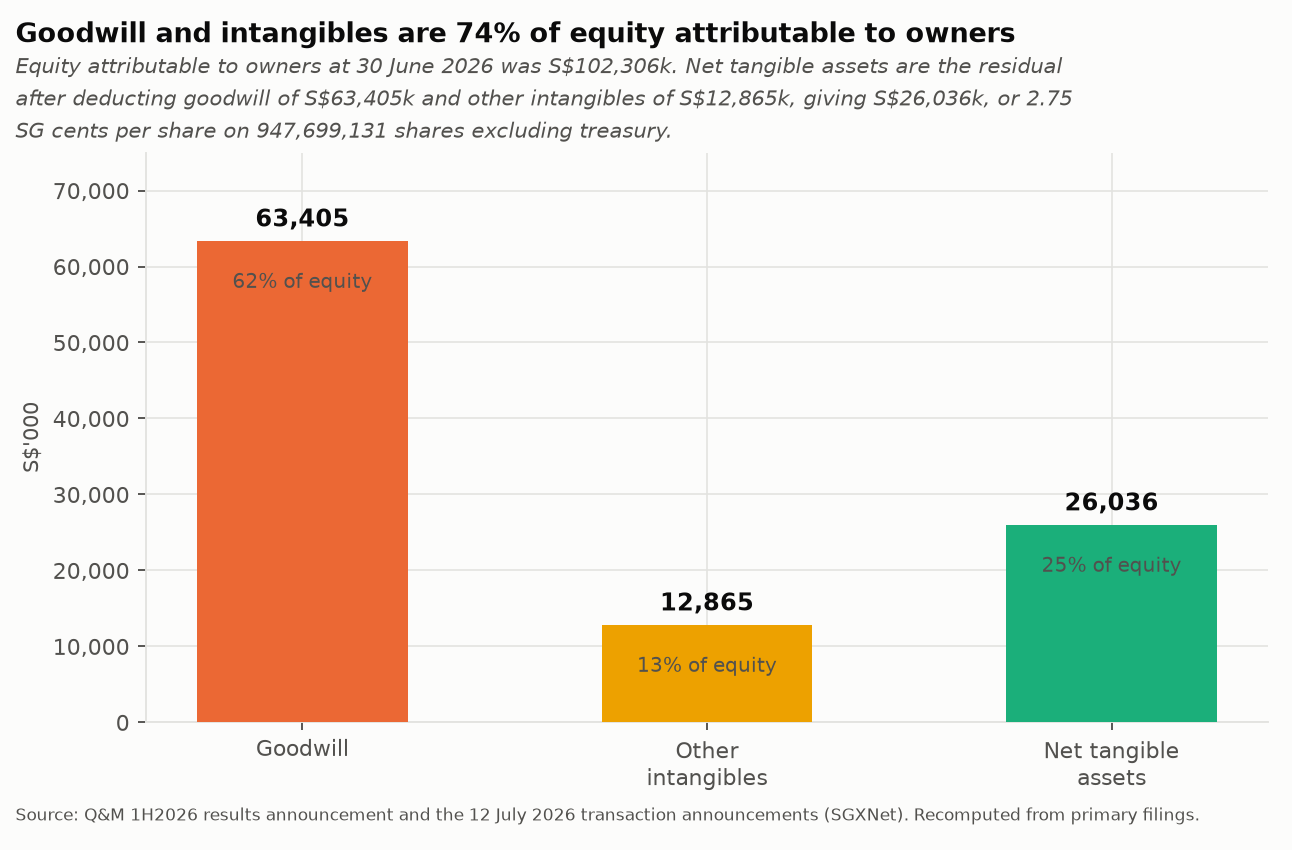
Equity attributable to owners
102,306
less goodwill
(63,405)
less other intangibles
(12,865)
Net tangible assets attributable to owners
26,036
That is 2.75 SG cents per share on 947,699,131 shares excluding treasury. Goodwill alone is 62% of equity attributable to owners, and goodwill plus other intangibles is 74%. (D on R)
Net tangible assets are the residual after goodwill and other intangibles.
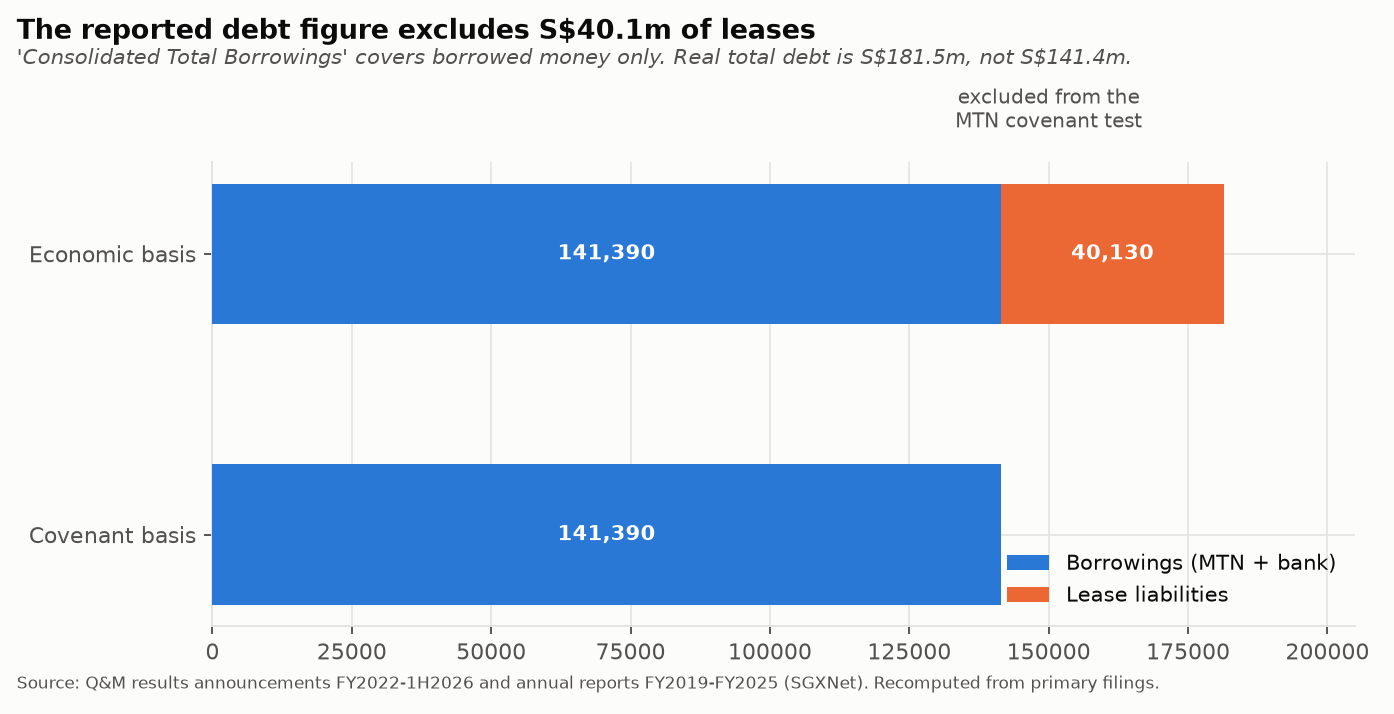
The company's own debt framing excludes the lease book. The 1H2026 press release states that “MTN, bank borrowings and finance leases eased to S$141.4m” — that figure is other financial liabilities (140,884 + 506). Lease liabilities are a separate S$40,130k. Total debt including leases is S$181.5m; against cash of S$119,224k, economic net debt is S$62.3m. For a network of roughly 149 Singapore and Malaysia outlets the lease book is the principal fixed obligation, and any gearing measure using S$141.4m understates the total by 28%. (D on R)
“Consolidated Total Borrowings” in the MTN covenants covers borrowed money only.
Book value growth accrued to minorities. Total equity rose from S$127.7m to S$135.7m over 1H2026, but equity attributable to owners fell from S$104.4m to S$102.3m while non-controlling interests rose from S$23.3m to S$33.4m. Retained earnings fell from S$32.3m to S$28.3m. The driver of the S$10.1m increase in non-controlling interests is not explained in the statement of changes in equity as filed — see section 16. (R + D)
Cash flow and dividends paid in the same period. For 1H2026, operating cash flow of S$12.563m less PPE purchases of S$2.591m and lease principal of S$7.254m gives S$2.718m before cash interest. Deducting S$3.668m of interest paid, classified in financing, gives negative S$0.950m. Owners' cash dividends were S$3.966m and NCI dividends were nil, leaving negative S$4.916m after all cash dividends. For FY2025, owners' cash dividends were S$10.426m and NCI dividends S$0.123m; S$8.804m was the FY2024 owners' amount. These are cash-paid comparisons, separate from dividends declared. (D on R; cash-paid comparison corrected 11 September 2026; financial information cutoff unchanged.)
9 · Funding and the MTN covenants
The MTN information memorandum of 30 June 2025, Condition 4(b), sets three financial covenants tested at each half-year Test Period: (R)
Covenant
Requirement
At 30 Jun 2026
Status
Consolidated Shareholders' Equity
≥ S$60,000k
S$135,702k total / S$102,306k attributable
Met
Consolidated Net Debt / Shareholders' Equity
≤ 2.00x
0.16x / 0.22x
Met
Consolidated EBITDA / Interest Expense
≥ 1.75x
5.23x
Met
The definition matters. “Consolidated Total Borrowings” covers overdrafts, notes, bonds, debentures, other indebtedness for borrowed money and redeemable preference shares. SFRS(I) 16 lease liabilities are not included. Covenant net debt is therefore S$22,166k, not the S$62,296k economic figure in section 8. On the stated limits, additional net debt capacity to the 2.0x threshold is approximately S$249m on total equity and S$182m on the stricter attributable basis, and EBITDA could fall about 67% before the interest-cover test is reached. (D on R)
The S$500m multicurrency debt issuance programme has S$130m drawn — senior unsecured notes at 3.95% due 10 July 2028. Undrawn programme capacity is an issuance framework, not committed liquidity, and is not treated here as available headroom. (R + O)
Against that, the two signed acquisitions carry gross scheduled near-term cash uses of approximately S$95.5m before fees and working capital, against cash on hand of S$119.2m at 30 June 2026 — about 80% of the cash balance. The actual funding mix between cash on hand and new issuance is not disclosed. If the A$18.75m contingent payment becomes payable, cumulative scheduled uses rise to roughly S$112.3m before fees. (D on R)
10 · Where the cash went, and what the network actually costs
S$’000, from the consolidated statements of cash flows in the FY2022 (for FY2021), FY2023, FY2024 and FY2025 annual reports. † FY2024 operating cash flow is the restated figure carried in the FY2025 report; the FY2024 report itself gave 40,098.
S$’000
FY2021
FY2022
FY2023
FY2024
FY2025
Operating cash flow
50,794
33,550
33,260
40,108†
36,903
Purchase of property, plant and equipment
7,799
9,310
5,735
7,962
4,972
Purchase of intangible assets
1,061
1,663
811
152
–
Lease liabilities — principal repaid
8,787
11,467
12,438
12,853
14,148
Lease liabilities — interest paid
1,599
1,855
1,670
1,648
1,774
… leases as a multiple of capex
1.3×
1.4×
2.5×
1.8×
3.2×
Acquisitions of subsidiaries, net of cash acquired
(2,850)
–
–
(800)
+8,084
Dividends paid to equity owners
48,760
13,152
7,193
8,804
10,426
Dividends paid to non-controlling interests
–
5,012
1,960
–
123
Share buy-back
3,053
–
–
–
3,037
Term loans drawn
10,000
2,400
–
2,480
5,000
Medium term notes issued
–
–
–
–
130,000
Bank loans repaid
1,465
900
5,364
8,386
65,483
Interest paid, excluding lease interest
1,422
2,054
3,985
3,724
4,667
Cash and cash equivalents at year end
47,611
39,698
33,993
34,342
117,085
The capital cost of a dental network is the lease, not the capex. In FY2025 the group paid S$4.97m for plant and equipment and S$15.92m to landlords through the lease liability — principal and interest — which is 3.2 times as much. Over the five years the gap is S$39.5m of capex and intangibles against S$68.2m of lease principal and interest. Nothing about that is hidden: leases sit in financing, where a cash flow statement puts them, and the multiple has widened every year except FY2024 because the capex line has fallen by 36% since FY2021 while the lease line has risen by 53%. But a reader who takes “capex” as the measure of what it costs to keep the network open — 110 Singapore outlets and 37 Malaysian clinics at the end of FY2025, on the operational-review basis used in section 7 — is reading the smaller half of the number.
FY2021 paid out 96% of its operating cash flow as dividends and the payout has never returned. S$48.8m went out that year — a 5.5-cent interim and a 0.5-cent final — against S$50.8m of operating cash flow. Dividends then fell to S$13.2m, then S$7.2m, which is 85% below the FY2021 figure, and FY2025’s S$10.4m is still barely a fifth of it. Operating cash flow over the same period fell by 27%, so the dividend fell roughly three times as far as the cash that funds it.
FY2025 rebuilt the funding structure inside a single year. The company issued S$130m of three-year notes on 10 July 2025 at 3.95%, under the S$500m programme established in December 2017, and repaid S$65.5m of bank loans — roughly eight times the previous year’s repayment. Cash went from S$34.3m to S$117.1m. That is the whole explanation for a balance sheet that looks unrecognisable against FY2024: the company did not earn its way to S$117m of cash, it borrowed at a fixed coupon and held the proceeds.
The acquisitions line turned positive in FY2025, which is unusual enough to explain. Buying subsidiaries produced a net S$8.08m inflow. Aoxin Q & M came with S$12.27m of cash against S$8.65m of consideration, of which S$5.38m was settled out of the proceeds of the deemed disposal rather than in cash — a S$9.01m net inflow — and S$0.92m went out for Em2ai, Citizen Dental Surgery and Bedok Dental Surgery combined. The Aoxin shares themselves were not bought for cash: 87,973,480 of them came from Field Health Enterprises on 30 April 2025 in partial settlement of the profit-guarantee amount owed by Dr Shao Yongxin under the 2016 share security agreement, which took the company through the 50% threshold and triggered the mandatory offer.
And the S$4,156k in the Unallocated column above is the residue of S$37.5m of gross movement, roughly half of it provisional. The FY2025 accounts carry a S$20,850k loss on the deemed disposal of the Aoxin associate and a S$1,030k gain on the deemed disposal of Em2ai, against S$15,664k of bargain purchase gains — S$15,477k on Aoxin and S$187k on Em2ai. Those four numbers net to exactly the S$4,156k the segment note reports. The Aoxin acquisition accounting, however, is stated by the company to be preliminary: the twelve-month hindsight period allowed by the business-combinations standard had not expired at the reporting date, the provisional amounts “could change”, and an independent valuer’s report was expected only “in time for the next set of interim financial statements”. A S$15.5m bargain purchase gain resting on amounts the company itself calls provisional sits inside a year whose attributable profit is S$9.3m.
11 · The four acquisitions, side by side
Two are signed sale-and-purchase agreements at the parent (announced 12 July 2026); two are memoranda of understanding at the Aoxin subsidiary (25 March and 20 April 2026). All four are underwritten by vendor profit guarantees. (R)
Deal
Status
Consideration
Profit guarantee
Cash escrow
Escrow / lifetime guarantee
Australia — Experteeth
Signed SPA; EGM required
AUD 119,635,712 plus a mandatory AUD 30,360,000 equity injection
Every lifetime escrow ratio sits in a 5.6–9.9% band across three currencies, with 15-year share moratoria on three of the four. That is a house parameter applied consistently rather than four independent negotiations. (D on R)
Measured instead against the contractual test block rather than the lifetime total — which is the basis on which the guarantees are actually tested and remedied — Australia's A$8m is 37.0% of the first two-year block of A$21.63m, and Thailand's escrow is 77.7% of Q&M's Year-1 attributable guarantee. Both denominators are shown because the two give very different impressions and the filings support both computations. (D on R)
No independent valuation was obtained for any of the four targets, and none was required. Experteeth's Rule 1014 circular, which would carry an independent financial adviser's opinion, had not been published as at the cut-off date. (R)
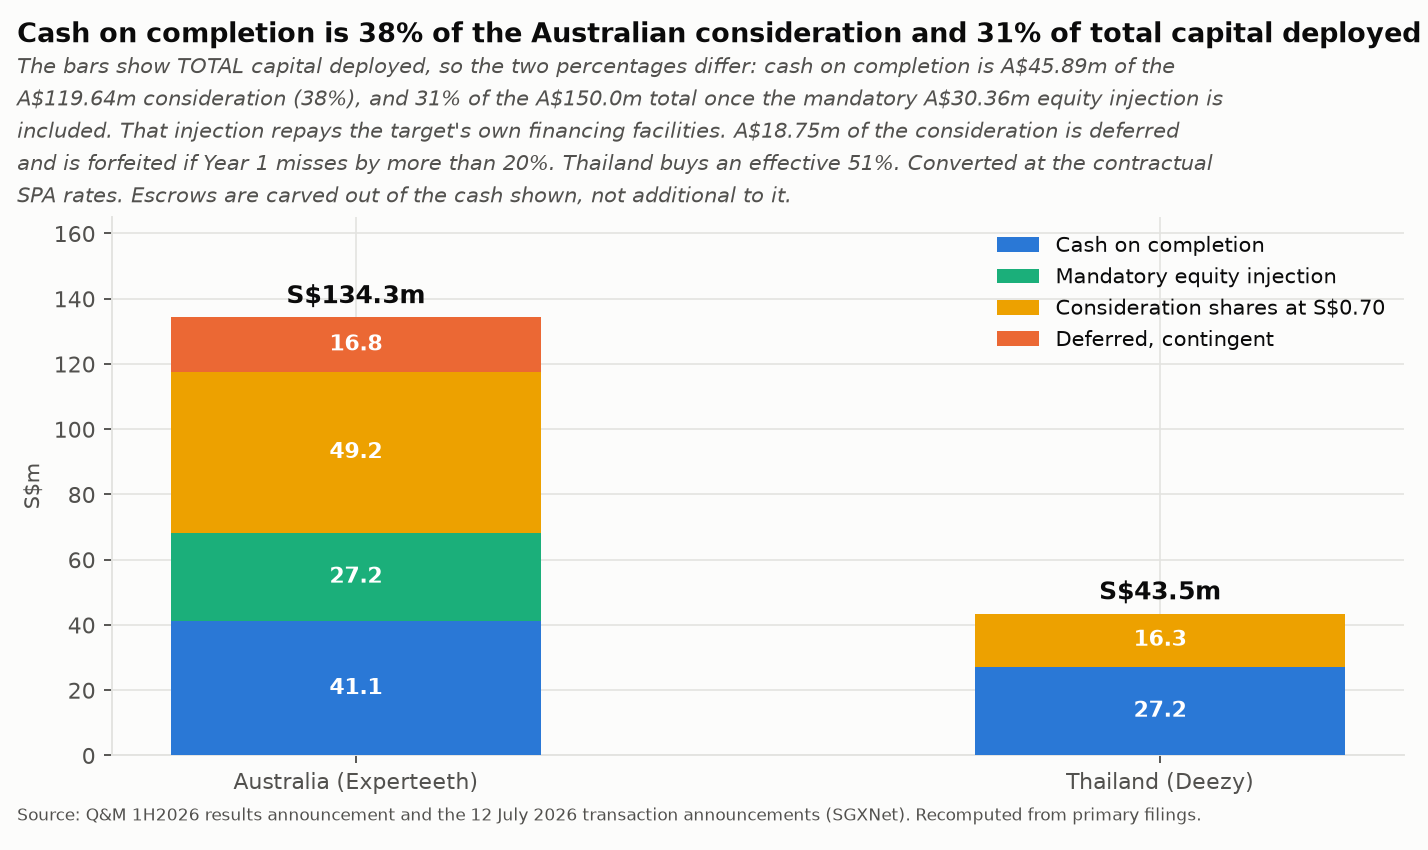
Cash, mandatory equity injection, consideration shares and deferred contingent consideration, at the contractual SPA rates.
Other filed terms
Experteeth consideration shares — 70,337,143 at S$0.70, a 25.7% premium to the S$0.557 VWAP of 9 July 2026, with a 15-year moratorium. Target FY2025 profit before tax attributable to the sale shares was S$9,413,833 on unaudited management accounts; net tangible assets of the sale shares were S$4,869,125. (R)
Experteeth Year-1 test — guaranteed Year-1 NPAT is AUD 10.3m. If the shortfall exceeds 20%, the AUD 18,750,000 deferred payment is forfeited and treated as a reduction of consideration; at 97% or above it becomes payable. The guarantee schedule grows 10% a year to Year 6 then is flat for Years 6, 7 and 8. (R)
Experteeth remedies — a shortfall waterfall taking cash from the sellers first, then the escrow, then residual cash or sale of consideration shares under a share security deed; escrow replenishment of at least 50% in cash, deductible from amounts otherwise payable to the guarantors and key dentists for clinical services; and a put option requiring the sellers to buy back all sale shares at consideration plus the financing facilities amount plus 10% per annum. (R)
Deezy — 16,375,714 consideration shares at S$0.70 under the AGM general mandate, which is why no EGM is required. 51% FY2025 profit before tax was S$2.1m on an unaudited pro forma; 51% net tangible assets S$9.6m. Its waterfall ranks a dividend waiver ahead of the cash escrow, then the obligors jointly and severally at 70.4% in cash within 90 days and 29.6% via sale of consideration shares. It adds personal guarantees, which Australia does not have. (R)
12 · The issuer's own pro-forma financial effects
Both 12 July announcements carry pro-forma financial effects in their section 7. These are the company's own illustrative calculations, not independent valuations, and the Australian figures remain subject to due diligence. Reproduced as published. (R)
Experteeth — NTA assumed at 31 Dec 2025, earnings at 1 Jan 2025
Before
After
NTA attributable to owners (S$'000)
55,784
(24,391)
NTA per share (SG cents)
5.89
(2.40)
Earnings attributable to owners (S$'000)
9,312
19,190
Earnings per share (SG cents)
0.98
1.88
Deezy — same conventions
Before
After
NTA per share (SG cents)
5.89
3.86
Earnings per share (SG cents)
0.98
1.14
The two effects point in opposite directions and both are the company's arithmetic: earnings per share roughly doubles on Experteeth alone, and net tangible assets per share goes negative. (R)
13 · China — a separately filed disclosure stream
Aoxin Q&M files its own announcements on Catalist. None of the following appears on Q&M's own announcement tape, so an investor working only from the parent's filings would not see it. (R throughout)
The guarantee record is mixed
Cumulative shortfall of RMB 60,546,727 at 31 March 2026 under a guarantee from Dr Shao Yongxin and Health Field Enterprises Ltd, secured on Aoxin shares.
After enforcing the security, RMB 39,909,589 remains owed. The company states that attempts to engage the vendor were “ultimately unsuccessful” despite repeated reminders, and that no alternative proposal was offered.
Q&M credited S$3,857,081 of recovery by taking 21,428,229 Aoxin shares at the S$0.180 VWAP — shares whose book value was S$1,367,000 and net tangible assets S$872,000. No independent valuation was obtained.
An independent third party was engaged to find outside buyers for those shares and none were found.
A separate “Vendor 1” had fully repaid in cash the remaining RMB 2,234,150 across Tranches 2 to 6 as at 5 June 2026; Vendors 2 and 3 had no outstanding shortfalls.
An affected person lodged a police report against Dr Shao in Shenyang on 2 July 2026; Aoxin said it was not a party to the report.
Share count and the consolidation threshold
Aoxin weighted-average shares, 1H2025 → 1H2026
511,522,048 → 1,064,732,985
Q&M's holding
560,007,821 = 52.6%
How that level was maintained
An October 2025 undertaking for 269,323,546 rights shares plus up to 242,198,502 excess, then a further 50,000,000-share subscription in March 2026
The 4 May 2026 placement
134,000,000 new shares, of which 50,000,000 to Q&M — 37% of the issue
Both China MOUs pay 50% in new Aoxin shares
central RMB 75m, southern RMB 188m — roughly 164m further shares
Holding if Q&M does not subscribe again (D)
approximately 45.6%, below the 50% at which consolidation rests
The arithmetic in the last row is derived here from the filed share counts and the announced MOU consideration split; it is not a company statement. (D on R)
Operations and governance
Panjin Aoxin Quanmin Stomatology Hospital closed on lease expiry in mid-April 2026. The board states it had been loss-making since incorporation in 2017 and that a near-term turnaround would be “challenging” given “the competitive landscape of the dental industry in China”.
The National Healthcare Security Administration matter. At the NHSA's request Aoxin conducted a self-review of two Shenyang hospitals; NHSA and the hospitals concluded there had been an excess claim of cost of material of approximately RMB 6.2 million for FY2024, corrected retrospectively. Group impact was −S$373k, small only because Aoxin was equity-accounted in FY2024. The RMB 6.2m was fully refunded to the NHSA during FY2025; the parent separately recognised a S$3,078,000 impairment on the carrying value of its investment.
SGX RegCo queried Aoxin on 11 August 2026 about an independent director who sits on nine listed company boards plus five non-listed principal commitments, invoking Provision 4.5 of the Code of Corporate Governance.
14 · EM2AI — an interested-person transaction, and a proposed exit
March 2025. Q&M acquired the remaining 51% of EM2AI for S$1,760,000 — an interested person transaction under Chapter 9, the vendor being controlled by Executive Director and CEO Dr Ng Chin Siau (58.53%) with COO Dr Ang Ee Peng Raymond holding 9.47%. No independent valuation. Implied 100% value approximately S$3.45m. (R)
14 August 2026, announced 16 August. A non-binding MOU to sell 60% of the now wholly-owned EM2AI to Medi Lifestyle Limited (SGX Catalist: Z4D) for 138,000,000 new Medi Lifestyle shares at S$0.049, approximately S$6,762,000 — no cash. Implied 100% value approximately S$11.27m. (R)
The two are not comparable.EM2Clinic, the clinic-management business, is carved out of the target before completion, so the 2025 acquired perimeter and the 2026 disposal perimeter are different businesses. No entry-to-exit comparison is drawn here; a perimeter bridge would be needed and the company has not published one. (O, on R)
Completion is conditional on the buyer undertaking to raise at least S$30m within two years — a post-completion undertaking, not a pre-completion condition — with a profit-target mechanism for FY2027–FY2029. (R)
15 · Corporate-events timeline
Date
Event
26 Nov 2009
Listed on SGX by placement of 74,075,000 shares at S$0.27
18 Mar 2024
Aoxin announces a “Vendor 1” cumulative profit-guarantee shortfall running since FY2022
FY2024
NHSA excess claim of approximately RMB 6.2m identified at two Shenyang hospitals; restated retrospectively
Mar 2025
Acquires the remaining 51% of EM2AI from a CEO-controlled vendor for S$1,760,000 (interested person transaction)
Jun 2025
Aoxin Q&M becomes a consolidated subsidiary, having previously been equity-accounted
30 Jun 2025
MTN information memorandum; S$500m multicurrency programme
Jul 2025
S$130m senior unsecured notes issued at 3.95%, due 10 July 2028
13 Oct 2025
Undertakes to subscribe for 269,323,546 Aoxin rights shares plus up to 242,198,502 excess shares
25 Mar 2026
Aoxin MOU for a central China acquisition: RMB 150m, guarantee RMB 71m over 5 years
23 Mar 2026
Aoxin states a 14-centre network across seven Liaoning cities
31 Mar 2026
Second Security Enforcement: cumulative shortfall RMB 60,546,727; RMB 39,909,589 still owed
Mar 2026
Further 50,000,000-share subscription in Aoxin
mid-Apr 2026
Panjin Aoxin Quanmin Stomatology Hospital closes on lease expiry; loss-making since 2017
20 Apr 2026
Aoxin MOU for a southern China acquisition: RMB 376m, guarantee RMB 358.5m over 10 years
29 Apr 2026
Mr Hareesh V Nair appointed to the board as IMC Dynamic's nominee
4 May 2026
Aoxin placement completes: 134,000,000 new shares, 50,000,000 to Q&M
5 Jun 2026
Aoxin FY2025 profit-guarantee outcome announced
2 Jul 2026
Aoxin lodges a police report against its former director in Shenyang
12 Jul 2026
Experteeth (Australia) and Deezy (Thailand) sale-and-purchase agreements announced
12 Jul 2026
Proposed Bursa secondary listing (announced April 2025) deferred per the update announcement
11 Aug 2026
SGX RegCo queries Aoxin on an independent director's board commitments
14 Aug 2026
1H2026 results released
16 Aug 2026
Non-binding MOU announced to sell 60% of EM2AI to Medi Lifestyle for shares
16 · Three accounting events — why a spliced series misleads
FY2023 core dental segment result was restated from S$37,600k to S$49,415k between the FY2023 filing and the FY2024 comparative column. This is a presentation change: from FY2024 onward “segment results” is struck before unallocated corporate expenses, which are then shown separately. A series splicing the two bases shows a fake +38% jump in core dental profit between FY2023 and FY2024. (R + D)
FY2024 was restated again in the FY2025 filing (note 18): core dental PAT S$27,807k → S$26,124k; group PAT S$13,066k → S$12,693k; unallocated S$(8,917)k → S$(7,234)k. Two unrelated changes are combined in it — a S$373k error correction arising from the NHSA matter, and a segment presentation reclassification that nets to zero at group level. (R + D)
1H2026 note 17 finalised the Aoxin purchase-price allocation retrospectively, cutting provisional goodwill from S$75.151m to S$61.774m and recognising customer relationships, a trademark, inventory and deferred-tax adjustments in its place. This is normal PPA finalisation, not a misstatement — but it demonstrates how much of a goodwill figure can be reallocated once an allocation completes. (R)
16 · The share price and what came with its moves
Over the window Q & M Dental returned +107.7% on a dividend-adjusted basis; the Straits Times Index returned +80.0% and the median of the 3 listed comparisons +73.4%.
Click a quarter — on the chart or in the return strip under it — to read its filings beside its large moves.
Key: Q & M Dental (QC7) as a solid line; Straits Times Index rebased, dashed; peer median rebased, dotted; the peer median runs off scale Aug 24–Feb 25 and is clipped there; filing ticks above the axis; ex-dividend ticks on it; numbered pins are moves with a written note; plain dots are other detected moves.
The peer set is three names (Aoxin 1D4, Raffles Medical BSL, IHH Q0F), of which Aoxin is a thinly traded subsidiary that often prints 0.0% on a move day, so the peer median leans on two large hospital operators and the dispersion is wide (26 Oct 2023: Raffles -1.7, IHH -0.6, Aoxin +3.9).
Key moves
The five largest moves over a day or up to two weeks, with no day counted twice.
Each move is shown next to the market over the same days (and peers, where shown). News listed with a move was published within its dates; that does not mean the news caused the move. The quarter view has all the news.
Index: Straits Times Index. Peers: the median of three listed companies used as a sector check; the notes name them and their limits.
Q3 2023
22 Aug 2023 – 29 Sep 2023 (part quarter)
QC7 −8.1%STI +1.8%Peer median −1.4%Range S$0.26–S$0.29Close S$0.27
Q4 2023
2 Oct 2023 – 29 Dec 2023
QC7 −3.8%STI +0.7%Peer median −13.6%Range S$0.21–S$0.27Close S$0.26
Large price moves
126 Oct 2023 · −6% · index 0% · peers −1%
2week to 27 Oct 2023 · −8% · index −1% · peers 0%
315 Dec 2023 · +6% · index 0% · peers +1%
4week to 15 Dec 2023 · +13% · index 0% · peers 0%
520 Dec 2023 · −8% · index 0% · peers 0%
Q1 2024
2 Jan 2024 – 28 Mar 2024
QC7 +0.3%STI −0.5%Peer median −3.7%Range S$0.23–S$0.27Close S$0.25
The investor, EM2AI Professional HoldCo, is 77% owned by group CEO Dr Ng Chin Siau, making the deal an interested-person transaction. EM2AI had lost S$3,498,000 since incorporation to 30 June 2023, the group was its only customer, and an independent valuation put 100% of the business at S$700,000 to S$900,000. The investor also agreed to lend EM2AI S$3,701,663 interest-free within a year. The company said the deal shifts the funding burden for a loss-making R&D business to the investor while the group keeps a 49% stake; completion was announced on 5 March 2024, after which EM2AI was deconsolidated to an associate.
Next session (26 Jan): QC7 +0.0% · STI +0.4% · peers +0.0%
Dental and medical clinic revenue rose 4% to S$167.8m on Singapore clinics, while medical-laboratory and supplies revenue fell 26% to S$15.0m as Covid-19 testing demand faded. Employee benefits rose to 59.6% of revenue from 57.2% and finance costs rose 45%. 2H2023 PATMI was S$6.2m against S$1.5m a year earlier. Operating cash flow was S$33.5m; cash S$34.0m against bank borrowings and finance leases of S$80.3m, gearing 0.78 from 0.83. The second interim dividend was 0.53 cents (total 0.69 cents, 57% payout). On 7 March the company answered an SGX query on booking a S$0.1m share of profit from Aoxin despite Aoxin's RMB46.1m 2H2023 loss: that loss included a RMB46.9m impairment of Acumen Diagnostics, eliminated on Q&M's consolidation because Acumen is a Q&M subsidiary.
Guidance: No known significant changes in industry trends or competitive conditions, and no other major known factors expected to adversely affect the group in the next reporting period and next 12 months.Next session (1 Mar): QC7 +0.0% · STI −0.2% · peers +0.0%
Sreenivasan, Toh Chooi Gait and Ng Weng Sui Harry all retired at the 16 April 2024 AGM as their tenure exceeded the nine-year independence limit. Lim Yeow Hua joined as independent director chairing the Audit and Remuneration Committees, and COO Dr Ang Ee Peng Raymond stepped down as executive director from 2 May 2024 to focus on operations and recruitment. On 24 June 2024 Prof Chew Chong Yin was added as a third independent director and the board was reconstituted under chairman Tan Teck Koon, with Dr Ang as alternate to CEO Dr Ng.
The 10 June 2024 article quoted Dr Ng as saying the AI treatment-planning tool could multiply the group's 14,000 monthly scaling procedures two to three times and grow revenue by 10%. The board said the statements could have been read as definitive projections, flagged 'teething issues' in implementation, and corrected a second point: the 49% stake in Acumen Diagnostics bought in 2021 was acquired by Aoxin, not Q&M, which holds 51% directly and 67.07% effectively.
Next session (13 Jun): QC7 −2.0% · STI +0.5% · peers +0.0%
Acumen is a 51% subsidiary; Dr Ong was also an executive director of the associate Aoxin. She objected to the leave and disputed any cause for investigation. Mr Lua Chong Hui (Joseph) took over her responsibilities. The board said the matter was not expected to have a material adverse impact on the group.
Next session (1 Jul): QC7 +0.0% · STI +0.2% · peers +0.0%
Q3 2024
1 Jul 2024 – 30 Sep 2024
QC7 +20.5%STI +7.6%Peer median −7.5%Range S$0.24–S$0.29Close S$0.28
The award also requires AR Dental to repay RM2,495,623.50 of shareholder loans and the respondents to pay about RM545,000 of costs, with a Malaysian property to be sold first against the buy-back sum. The group had invested RM8,400,000 for 70% of AR Dental in 2013 and had impaired RM6,300,000 of it; the company said the award would not have a material impact on FY2024. A 21 February 2025 update said the Malaysian High Court recognised the award on 27 August 2024 and dismissed a set-aside application with RM20,000 costs, which the respondents appealed.
Next session (16 Jul): QC7 −3.4% · STI −0.3% · peers +0.0%
Clinic revenue rose 4% to S$82.2m on Singapore dental clinics, offset by lower profit-guarantee income; medical-laboratory and supplies revenue fell 20% to S$6.6m. Net other gains of S$1.8m came from the gain on deconsolidating EM2AI and compensation from ex-vendors of Shanghai Chuangyi and AR Dental. Other expenses fell 6%, finance costs fell 3%, and associates contributed S$0.2m as Aoxin turned profitable. EBITDA rose 27% to S$23.4m. Operating cash flow was S$17.3m; cash S$32.3m against borrowings and finance leases of S$76.5m, gearing 0.71 from 0.78; NAV per share 11.0 cents. Dividend payout 39%. Singapore dental outlets numbered 104 against 107 a year earlier. Released 07:58, before the open.
Guidance: No known significant changes in industry trends or competitive conditions, and no other major known factors expected to adversely affect the group in the next reporting period and next 12 months.Same session: QC7 +3.8% · STI −0.8% · peers +1.1%
The net book value of the business's assets was S$203,486 at end-2023; the vendor dentist was to sign a ten-year service agreement and the guarantee was to be secured by cash escrow. On completion on 14 November 2024 the terms were lengthened: a 15-year service agreement and a 12-year guarantee totalling S$1,539,003. The company classed the deal as non-discloseable under Rule 1008.
MOH rejected the change of principal officer and of licensee, so Acumen would need a new licence. On 28 October 2024 the board said the laboratory business would be suspended with no immediate plan to reapply, as non-Covid PCR testing had been loss-making in FY2023 and 1H2024; MOH also directed the Sengkang joint testing and vaccination centre, Acumen's only profitable activity, to close from 1 December 2024, leaving Acumen without a revenue stream. Dr Ong's employment was terminated on 26 October 2024 with two months' pay in lieu, the CLA fact-finding review was discontinued without conclusions on misconduct, and the board said ceasing Acumen's businesses would bring a non-recurring material adverse financial impact. She was removed as a director of Acumen on 16 December 2024.
Next session (17 Sep): QC7 +0.0% · STI +0.6% · peers +0.6%
Large price moves
810 Jul 2024 · +7% · index +1% · peers 0%
9week to 12 Jul 2024 · +16% · index +3% · peers +1%
103 Sep 2024 · +6% · index +1% · peers 0%
Q4 2024
1 Oct 2024 – 31 Dec 2024
QC7 −1.8%STI +5.6%Peer median −2.2%Range S$0.27–S$0.32Close S$0.28
No consideration was stated; terms were to be negotiated after due diligence. The company described it as an opportunity to expand in southern China. No definitive agreement was announced in the window.
Next session (24 Oct): QC7 −3.2% · STI +0.1% · peers +0.0%
Large price moves
1122 Oct 2024 · +5% · index −1% · peers 0%
1223 Oct 2024 · +5% · index 0% · peers 0%
Q1 2025
2 Jan 2025 – 28 Mar 2025
QC7 +7.9%STI +4.9%Peer median −2.0%Range S$0.28–S$0.30Close S$0.29
Core dental revenue edged up to S$173.8m on Malaysia; other-business revenue fell 29% to S$6.9m after the medical laboratory ceased in September 2024. Other losses rose 60% to S$4.7m on impairments of goodwill, equipment and inventory at Acumen, so the second half was weaker: 2H2024 profit before tax S$3.0m against S$6.8m. Group net profit rose 18% to S$13.1m, and PATMI excluding other losses rose 28% to S$17.3m. Operating cash flow was S$40.1m; cash S$34.3m against borrowings and finance leases of S$73.7m, gearing 0.68x; NAV per share 11.2 cents. The second interim dividend was 0.7 cents (total 1.1 cents, 71% payout). Malaysia had 38 outlets against 44 a year earlier; Singapore 106. The company flagged Johor, the wider region and China as expansion targets. Released on a Saturday.
Guidance: No significant changes in industry trends or competitive conditions anticipated; no known major factors expected to adversely impact the group in the next reporting period or 12 months.Next session (3 Mar): QC7 −1.8% · STI +0.3% · peers +0.0%
The settlement covered Q&M, Aoxin, Acumen and Acumen Research. The company said it was not expected to have a material impact on FY2025 earnings or NTA.
Next session (24 Mar): QC7 +1.7% · STI +0.3% · peers +0.0%
An interested-person transaction: the vendor was 58.53% owned by Dr Ng. EM2AI had lost S$1,385,833 on a deconsolidated basis from incorporation to end-2024 but, the company said, now had positive cash flow: it won medical-device licences in Thailand, the Philippines, Vietnam and Indonesia (13 January 2025) and on 21 March 2025 signed a regional dental-solutions provider serving about 1,000 clinics, taking its reach to more than 1,100 clinics. No independent valuation was done. The company cited full control over the AI platform, consolidation of EM2AI's revenue, and avoiding Chapter 9 interested-person implications as reasons. Completion was announced on 11 April 2025.
Next session (1 Apr): QC7 +1.7% · STI −0.1% · peers −0.5%
Large price moves
1319 Feb 2025 · +5% · index 0% · peers 0%
1410 Mar 2025 · +6% · index 0% · peers 0%
Q2 2025
1 Apr 2025 – 30 Jun 2025
QC7 +50.8%STI −0.2%Peer median +2.5%Range S$0.24–S$0.45Close S$0.45
Advisers were appointed for the Bursa listing but no application had been made; the board cited a wider investor base, liquidity and future fund-raising flexibility. The demand relates to guarantees given by Dr Shao on the 2013-2016 Shenyang hospital acquisitions, secured by an escrow account and by the Aoxin shares held by his vehicle HFEL; the board said it would consider enforcing that share security. Q&M then held 32.78% of Aoxin.
Next session (21 Apr): QC7 +3.6% · STI +1.0% · peers +1.0%
No cash was paid for the enforced shares, which count as partial settlement of the RMB72.3m shortfall. The offer, at Aoxin's last traded VWAP, would cost at most S$8,122,444 for the remaining shares; the company said it intends to keep Aoxin listed, fund the offer from cash reserves, and treat Aoxin as a subsidiary. Aoxin's NTA was S$25,646,217 at end-2024. Replying to an SGX query on 7 May, the company said Dr Shao had never maintained the required escrow balance, so no escrow claim was possible, and about S$10.18m remained owed.
Next session (2 May): QC7 +3.4% · STI +0.3% · peers +4.3%
The offer document was dated 19 May 2025 and the offer closed on 16 June 2025. Consolidation from this point drives the FY2025 revenue step-up and a deemed-disposal loss booked in 1H2025.
Next session (17 Jun): QC7 −1.3% · STI +0.6% · peers +0.0%
Large price moves
157 Apr 2025 · −10% · index −8% · peers −2%
169 Apr 2025 · −8% · index −2% · peers 0%
1710 Apr 2025 · +6% · index +5% · peers +1%
18week to 11 Apr 2025 · −10% · index −8% · peers −1%
1926 May 2025 · +6% · index 0% · peers −1%
2030 May 2025 · +6% · index −1% · peers +1%
21week to 27 Jun 2025 · +17% · index +2% · peers 0%
Q3 2025
1 Jul 2025 – 30 Sep 2025
QC7 +2.0%STI +8.5%Peer median +14.2%Range S$0.39–S$0.51Close S$0.45
DBS, OCBC and UOB were joint lead managers; the notes are unsecured, sold to institutional and accredited investors in S$250,000 denominations, and were listed on 11 July 2025. Proceeds are for general corporate purposes including acquisitions, investments in associates, refinancing and working capital. About 2.88% of the issue was allocated to directors, controlling shareholders or persons related to them.
Next session (4 Jul): QC7 +0.0% · STI −0.1% · peers +0.0%
The Citizen and Bedok purchases had completed on 28 March and 29 May 2025. The aggregate book value of the assets acquired was nil. Non-discloseable under Rule 1008.
Next session (25 Jul): QC7 −1.2% · STI −0.3% · peers +0.0%
Dr Shao is the counterparty owing the profit-guarantee shortfall. The board said the resignation was not expected to have a material impact and that interim leadership was in place at Aoxin.
Next session (28 Jul): QC7 −1.2% · STI −0.5% · peers +0.5%
Core dental revenue rose 4% to S$87.2m, mainly from consolidating Aoxin from June, with Singapore clinics marginally lower; other-business revenue fell 74% to S$1.2m after the laboratory closed. Excluding other gains and losses, PATMI rose 5% to S$8.3m and core dental profit after tax rose 10% to S$13.7m. Profit before tax was S$4.8m against S$11.6m. Operating cash flow was S$15.0m; cash S$47.1m (Aoxin's cash now included) against borrowings and finance leases of S$78.5m, before the S$130m notes issued on 10 July. The company bought back 2,814,200 shares in the half for S$1.06m. Dividend payout 98%. Singapore had 108 dental outlets, Malaysia 37, and China 7 polyclinics and 7 hospitals. Released 07:48, before the open.
Guidance: Management 'actively looking for M&A and organic expansion opportunities' for the note proceeds, in Singapore, Johor and China; no significant changes in industry trends anticipated.Same session: QC7 +0.0% · STI −0.4% · peers +1.0%
The undertaking covers 269,323,546 pro rata and up to 242,198,502 excess rights shares, ranking last for excess allocations. The company said Aoxin had sufficient working capital but the funds would support its planned China expansion. The FY2025 results later showed the rights issue raised S$15,346,000 gross and Q&M's holding at 538,579,592 shares (52.64%), consistent with pro rata take-up only.
The target operates mainly in Bangkok and the north-east; the founder was to sign a 15-year service agreement and the vendors to procure THB 285m of net income for each of 2031-2033. The stake to be acquired was not specified at this stage. The company cited geographic diversification away from Singapore and Malaysia.
Next session (16 Oct): QC7 +3.3% · STI −0.3% · peers −0.8%
Large price moves
2322 Oct 2025 · +6% · index 0% · peers −1%
24week to 24 Oct 2025 · +11% · index +2% · peers 0%
Q1 2026
2 Jan 2026 – 31 Mar 2026
QC7 −2.9%STI +5.1%Peer median +7.7%Range S$0.49–S$0.57Close S$0.53
Ann Arbor's sellers are to take S$360,000 in shares under a five-year moratorium, sign seven-year service agreements and fund a cash escrow. The two targets had combined book value of about S$1.5m and net profit of S$0.2m. Funded internally; non-discloseable. Ann Arbor completed on 10 June 2026.
Next session (12 Feb): QC7 −1.9% · STI +0.6% · peers −0.7%
Core dental revenue rose 12% to S$195.0m on consolidating Aoxin from mid-2025 and higher Singapore clinic revenue, offset by S$1.4m less profit-guarantee income. Net other losses were S$4.6m (the deemed-disposal loss plus head-office relocation write-offs), MTN interest was S$2.4m, and PATMI excluding other items, MTN and PSP costs was S$17.0m against S$16.9m. Core dental profit after tax rose 16% to S$30.4m. The second half improved: 2H2025 PATMI S$5.5m against S$4.6m. FY2024 comparatives were restated for a RMB6.2m excess medical-insurance claim at two Aoxin hospitals, cutting FY2024 PATMI to S$14.3m from S$14.6m. The company bought back 6,962,500 shares in FY2025. The second interim dividend was 0.42 cents (total 0.82 cents against 1.10, 83% payout). Released 23:05 on a Saturday; a 1 March replacement corrected the payment date.
Guidance: A 'partnership-driven acquisition model' paying in cash and moratorium shares across Asia-Pacific; Aoxin to deploy about RMB43.7m (S$8.0m) on dental chains beyond north-eastern China; no significant changes in industry trends anticipated.Next session (2 Mar): QC7 −1.0% · STI −2.1% · peers −1.0%
The stake moves from 52.64% to about 51.81% of the enlarged capital. The company said the funds strengthen Aoxin's balance sheet for its China expansion and that it intends to use Aoxin as the platform for the PRC. Released at 00:47.
Definitive documents were targeted by 31 July 2026, with 15-year service agreements from the sellers. The target was not named and no consideration was disclosed; a 13 March release described it as 'another well-known dental operator in Singapore' in due diligence. No definitive agreement was announced in the window. Released 07:50, before the open.
The price splits into an AUD30m capital injection to repay the target's loans, AUD59.5m cash (AUD18.75m deferred a year against the first-year guarantee) and AUD55m in new Q&M shares at S$0.70 under a 15-year moratorium. Guaranteed NPAT runs from about AUD11.7m in year one to AUD17.1m by year five, with AUD8m in escrow, and the sellers sign 15-year service agreements. The 13 March media release added the 400-clinic internal objective and said the group was in due diligence in Australia, Thailand and Singapore. The binding SPA followed on 12 July 2026 at AUD119.6m plus a separate AUD30.36m injection.
Next session (12 Mar): QC7 +1.8% · STI −0.2% · peers +1.0%
The shortfall stood at RMB60,546,727 (about S$11,316,183) before this step; Q&M's Aoxin stake rises from 52.64% to 54.74%. The company said attempts to engage Dr Shao had failed and no third-party buyer could be found for the shares. Non-discloseable under Rule 1008.
Next session (1 Apr): QC7 +0.0% · STI +1.8% · peers +0.0%
Q2 2026
1 Apr 2026 – 30 Jun 2026
QC7 +3.8%STI +5.8%Peer median −5.2%Range S$0.53–S$0.64Close S$0.55
Large price moves
2518 May 2026 · +5% · index 0% · peers 0%
2629 May 2026 · +6% · index +1% · peers +2%
Q3 2026
1 Jul 2026 – 21 Aug 2026 (part quarter)
QC7 +0.7%STI +10.0%Peer median −4.9%Range S$0.54–S$0.57Close S$0.55
Announced at 23:07 on a Sunday after a trading halt requested on 9 July. The business had over 411 dentists; 51% of its pro forma FY2025 profit before tax was about S$2.1m and net assets S$9.6m. The guarantee runs from THB 123m in year one to THB 285m in years five and six (Q&M's 51% share from THB 62.73m to THB 145.35m), secured by a THB 48,740,000 escrow deducted from the cash and a share security. Consideration shares carry a 15-year moratorium and are issued under the general mandate; the deal is discloseable under Chapter 10 and needs no shareholder vote. The consideration equals 51% of the THB 1.95bn enterprise value set in the October 2025 MOU (computed).
Next session (13 Jul): QC7 −0.9% · STI +0.0% · peers −0.5%
Consideration is AUD64,635,712 cash (AUD18,750,000 deferred a year and conditional on the first-year guarantee) and AUD55,000,000 in shares, 7.42% of the existing share count, under a 15-year moratorium. The injection repays Experteeth's facilities and funds expansion. Guaranteed NPAT starts at AUD10,300,000 in year one and rises to AUD16,588,253 by year six; AUD8,000,000 sits in escrow. Net profit before tax attributable to the shares was about S$9,413,833 for the June-2025 year and NTA about S$4,869,125. The relative figure on net profits was 77.26%, so shareholder approval and a circular are required. The same evening the company said it would defer further steps on the proposed Bursa Malaysia secondary listing.
Next session (13 Jul): QC7 −0.9% · STI +0.0% · peers −0.5%
The materials, from a 10 July investor event held during the trading halt, set out the Australian and Thai deal structures, vendor alignment and escrow protections, and group synergies in AI, training and procurement. The company stated the scenarios 'do not constitute a forecast, projection or guarantee'. Released 07:36, before the open.
Core dental revenue rose 13% to S$98.6m on the full-period consolidation of Aoxin plus Singapore and Malaysia clinic and supplies growth, offset by lower profit-guarantee income; other-business revenue fell 22% to S$0.9m as four medical clinics were closed. EBITDA rose 19% to S$19.2m and core dental profit after tax rose 10% to S$15.0m. Finance costs rose 57% to S$3.7m on a full period of bond interest and employee benefits rose 16% to S$59.9m. Net other gains of S$0.9m came from selling the Jurong East Central property; profit before tax was S$5.4m against S$4.8m. Operating cash flow was S$12.6m; cash S$119.2m against MTN, borrowings and finance leases of S$141.4m; NAV per share 10.8 cents. Singapore dental outlets rose to 113 from 108, Malaysia fell to 36, and China's hospitals fell to 4 from 7. Released 07:05, before the open.
Guidance: Immediate priority is completing the Australian and Thai acquisitions and integrating them; Singapore expansion to continue mainly organically alongside acquisitions the company calls 'value-accretive'; no significant changes in industry trends anticipated.Same session: QC7 +0.9% · STI +0.4% · peers −0.6%
The buyer is to raise at least S$30 million within two years to fund EM2AI, and the parties intend profit targets of S$1,000,000, S$1,500,000 and S$2,500,000 net profit for FY2027-FY2029. Three-month exclusivity. This is the second time the AI unit has been partly divested, after the 2024 sale to a CEO-controlled vehicle that was reversed in 2025. Released 22:10 on a Sunday.
Next session (17 Aug): QC7 +0.9% · STI +0.4% · peers +0.4%
Record date 24 August 2026, payable 4 September 2026. The ex-date is the last session of the price window.
Notes and sources
Share price record
How this section was built
The detector flagged 26 large moves in the window — 19 single sessions and 7 weekly windows — before any news was read. 4 market moves, 1 sector move; 21 are left over after both controls, unexplained by them. Of those, 3 coincided with one in the same session or week and 18 have nothing filed against them beyond routine notices and are recorded as unexplained rather than explained away.
This section records the 36-month price history and puts every large move through two subtractions and reports what is left over, not what caused it: first the Straits Times Index, then the median of the 3 listed comparisons — Raffles Medical, IHH Healthcare and Aoxin Q & M — which trade the same session. “Left over” is what survives both controls.
Each quarter panel pairs two records. Key developments are the filings that carry information — results, the Aoxin security enforcements and mandatory offer, the placement and bond, the clinic acquisitions and MOUs, the EM2AI sale, board and dividend events — with the figures as filed, the guidance given, the close on the day and how the reacting session traded against the controls; a filing after the 09:00 open is read against the next session. Large price moves are the threshold-detected sessions, detected before any news was read and dispositioned from the controls and the enumerated tape; rows with a written note carry a numbered pin, the rest are dots on the line.
How to read the tags.Market-wide and Sector-wide mean the index or the peer median moved with the share over the same session or week; Residual means the move is still large after both are subtracted. A residual is what is left over, not a cause: it does not establish that the company’s own news moved the price, and an unchanged or thinly traded price is not proof that no information arrived. Returns use the dividend-adjusted close; a filing released after the open is read against the next session.
Prices are Yahoo Finance daily closes for QC7.SI, adjusted for dividends, over 755 sessions from 22 Aug 2023 to 21 Aug 2026; the filing tape is every Q & M Dental Group broadcast on SGXNet in that window from the SGX announcements API (company filter, with SGX broadcast times), retrieved 23 Aug 2026. A filing after the open is read against the next session.
Limitations bound every row above. The tape is the SGX announcements API's company filter for Q & M Dental Group, 234 broadcasts between 22 August 2023 and 21 August 2026 with SGX broadcast times; 19 daily share buy-back notices (8 May to 17 Nov 2025) and 99 director and substantial-shareholder interest notices, most of them the CEO's and Quan Min Holdings' open-market purchases from May 2025, were excluded individually rather than enumerated. Broker notes, block trades and substantial-shareholder timing, trade press and index reviews were not examined. Aoxin Q & M Dental Group (SGX: 1D4), a consolidated subsidiary from 16 June 2025 with its own SGXNet stream, is not enumerated here: the pack's entity register records its tape as gapped (coverage only from 3 March 2026 and non-exhaustive), so Aoxin events such as the rights issue, the NHSA self-review, Dr Shao's 22 July 2025 resignation, the March 2026 placement and hospital closures appear only where Q & M itself filed; Acumen Diagnostics and EM2AI are private and surface only through Q & M filings. The peer set is three names (Aoxin 1D4, Raffles Medical BSL, IHH Q0F), of which Aoxin is a thinly traded subsidiary that often prints 0.0% on a move day, so the peer median leans on two large hospital operators and the dispersion is wide (26 Oct 2023: Raffles -1.7, IHH -0.6, Aoxin +3.9).
A quarter shows only the columns it has. An empty developments column means: No filings beyond routine disclosures this quarter. An empty moves column means: No session cleared the large-move threshold this quarter.
The full move register — every large move and its market and sector controls
Every threshold-detected move in the window with its controls, dispositioned in the price-driver register; rows with a written note carry a numbered pin on the chart.
#
Session
QC7
STI
Peers
Left over
Control result
What the evidence supports
1
26 Oct 2023
−6.2%
−0.2%
−0.6%
−5.7%
Residual
Against an index move of −0.2% and a peer median of −0.6%, about 6 points are left over; 0.9× median volume. No filing beyond routine notices in the prior three sessions. Raffles −1.7 · IHH −0.6 · AoxinQM +3.9
2
week to 27 Oct 2023
−8.2%
−0.5%
+0.0%
−8.2%
Residual
Weekly window, 20 to 27 October 2023: −4.1% on 23 October and −6.3% on 26 October took the shares from S$0.245 to S$0.225, on 1.8× and 0.9× median volume. The index fell 0.5%, Raffles Medical 2.5% and IHH was unchanged; about 8 points survive both controls. The only filing of the month was the 9 October notice of an EGM on the performance share plan and constitution; nothing was filed inside the window or in the three sessions after it. There was no reversal: the shares fell a further 4.4% on 1 November to S$0.215, the low of the three-year window. Raffles −2.5 · IHH +0.0 · AoxinQM +2.6
3
15 Dec 2023
+6.0%
−0.2%
+0.6%
+5.4%
Residual
Against an index move of −0.2% and a peer median of +0.6%, about 5 points are left over; 2.4× median volume. No filing beyond routine notices in the prior three sessions. Raffles +0.9 · IHH +0.6 · AoxinQM +0.0
4
week to 15 Dec 2023
+12.8%
+0.2%
+0.0%
+12.8%
Residual
Weekly window, 8 to 15 December 2023: from S$0.235 to S$0.265 in three sessions (13 to 15 December, +4.3%, +4.2% and +6.0%), the last two on 2.2× and 2.4× median volume after a fortnight of almost no trade. The index rose 0.2%, Raffles Medical fell 0.9% and IHH rose 1.2%; about 13 points survive both controls. The tape is silent from the EGM minutes of 30 November to the EM2AI announcement of 25 January 2024, so nothing filed explains it. Most of the gain reversed within four sessions: −7.5% on 20 December and −2.0% on 21 December took the shares back to S$0.24. Raffles −0.9 · IHH +1.2 · AoxinQM +0.0
5
20 Dec 2023
−7.5%
−0.3%
+0.0%
−7.5%
Residual
The reversal of the previous week's gain, on 0.8× median volume, three sessions after the close of S$0.265. The index fell 0.3%, Raffles Medical was unchanged and IHH rose 0.6%, so the full 7.5 points are company-specific on the controls, and the tape is silent on both sides of it. With the next session's −2.0% the shares were at S$0.24, half a cent above where the rise had begun on 12 December. Raffles +0.0 · IHH +0.6 · AoxinQM +0.0
6
13 Mar 2024
+8.5%
+0.6%
+0.0%
+8.5%
Residual
An 8.5% gain on 2.6× median volume, from S$0.235 to S$0.255. The index rose 0.6%, Raffles Medical 1.9% and IHH was unchanged; about 8 points are left over. The filings of the prior fortnight had each passed without a move: the FY2023 results (revenue up 1% to S$182.7m and PATMI up 2% to S$11.5m, the company's figures, filed 29 February at 22:22 and flat on 1 March), the completion of the EM2AI sale on 5 March, and a reply to an SGX query on 7 March that reconciled Aoxin's 2H2023 loss to Q&M's S$0.1m share of profit and carried no new figure for the group. The gain reversed over the next three sessions (−2.0% each) to S$0.24. No filing sits against it. Raffles +1.9 · IHH +0.0 · AoxinQM +0.0
7
20 Mar 2024
+6.2%
+0.1%
+0.0%
+6.2%
Residual
Against an index move of +0.1% and a peer median of +0.0%, about 6 points are left over; 0.8× median volume. No filing beyond routine notices in the prior three sessions. Raffles +1.0 · IHH −1.2 · AoxinQM +0.0
8
10 Jul 2024
+7.4%
+1.0%
+0.0%
+7.4%
Residual
Against an index move of +1.0% and a peer median of +0.0%, about 7 points are left over; 7.7× median volume. No filing beyond routine notices in the prior three sessions. Raffles +1.0 · IHH +0.0 · AoxinQM −6.0
9
week to 12 Jul 2024
+16.0%
+2.5%
+1.1%
+14.9%
Residual
Weekly window, 5 to 12 July 2024: from S$0.25 to S$0.29 in three sessions (8 to 10 July, +4.0%, +3.9% and +7.4%) on 5×, 8× and 8× median volume, the step that ended eleven months of drift. The index rose 2.6%, Raffles Medical 3.0% and IHH 1.1%; about 15 points are left over. Nothing was filed in the window: the nearest filing before it was the 29 June notice placing Acumen's CEO on leave, four sessions earlier, and the first after it was the SIAC arbitral award against AR Dental's minority holders, filed at 22:31 on 15 July, so the rise preceded the award. There was no reversal; the shares closed between S$0.275 and S$0.295 through the rest of July. No filing explains it. Raffles +3.0 · IHH +1.1 · AoxinQM −6.0
10
3 Sep 2024
+5.6%
+0.5%
+0.0%
+5.6%
Residual
Against an index move of +0.5% and a peer median of +0.0%, about 6 points are left over; 3.9× median volume. No filing beyond routine notices in the prior three sessions. Raffles −1.6 · IHH +1.1 · AoxinQM +0.0
11
22 Oct 2024
+5.3%
−0.8%
+0.0%
+5.3%
Residual
Against an index move of −0.8% and a peer median of +0.0%, about 5 points are left over; 10.2× median volume. No filing beyond routine notices in the prior three sessions. Raffles −1.7 · IHH +0.5 · AoxinQM +0.0
12
23 Oct 2024
+5.0%
+0.4%
+0.0%
+5.0%
Residual
The second of two sessions on 10× and 11× median volume, +5.3% on 22 October and +5.0% on 23 October, from S$0.285 to S$0.315. The index fell 0.8% and then rose 0.4%, Raffles Medical moved −1.7% and +0.6%, IHH +0.5% and −0.9%; about 10 points over the two sessions survive both controls. The non-binding MOU to acquire 25% of Guangdong Delun, a South China chain with one hospital, 28 clinics and more than 400 chairs, was dated 22 October but filed at 17:35 on 23 October, after both sessions' closes, with no consideration stated, so the rise preceded the filing. The next three sessions gave back two-thirds of it (−3.2%, −1.6% and −1.7%) to S$0.295, the last of them the session after the 08:01 notice on 28 October that Acumen's laboratory would be suspended. Raffles +0.6 · IHH −0.9 · AoxinQM +0.0
13
19 Feb 2025
+5.3%
+0.2%
+0.0%
+5.3%
Residual
Against an index move of +0.2% and a peer median of +0.0%, about 5 points are left over; 3.6× median volume. No filing beyond routine notices in the prior three sessions. Raffles +0.0 · IHH −0.9 · AoxinQM +0.0
14
10 Mar 2025
+5.9%
−0.4%
+0.0%
+5.9%
Residual
Against an index move of −0.4% and a peer median of +0.0%, about 6 points are left over; 6.2× median volume. No filing beyond routine notices in the prior three sessions. Raffles −2.5 · IHH +1.8 · AoxinQM +0.0
15
7 Apr 2025
−10.2%
−7.5%
−1.9%
−8.2%
Market-wide
In line with the market: against an index move of −7.5% and a peer median of −1.9%, about 8 points are left over. Raffles −5.6 · IHH −2.0 · AoxinQM +66.7
16
9 Apr 2025
−7.5%
−2.2%
+0.0%
−7.5%
Market-wide
The third session of the April 2025 tariff sell-off, on 4.1× median volume. The index fell 2.2% while Raffles Medical was unchanged and IHH rose 0.5%, so on the day about 5 points are left over against the index and 7.5 against the peers. The next session reversed it: +6.1% with the index up 5.4%. Over the week of 4 to 11 April the shares fell 10.2% against the index's 8.2%, a residual of two points, and the only filing in the week was the AGM notice at 22:22 on 10 April. On the controls this is a market move that the shares took a session late, not a company event. Raffles +0.0 · IHH +0.5 · AoxinQM +0.0
17
10 Apr 2025
+6.1%
+5.4%
+0.5%
+5.6%
Market-wide
In line with the market: against an index move of +5.4% and a peer median of +0.5%, about 6 points are left over. Raffles +0.5 · IHH +1.0 · AoxinQM +0.0
18
week to 11 Apr 2025
−10.2%
−8.2%
−0.5%
−9.7%
Market-wide
In line with the market: against an index move of −8.2% and a peer median of −0.5%, about 10 points are left over. Raffles −0.5 · IHH −1.0 · AoxinQM +66.7
19
26 May 2025
+6.0%
−0.2%
−0.9%
+6.9%
Residual
Against an index move of −0.2% and a peer median of −0.9%, about 7 points are left over; 7.7× median volume. No filing beyond routine notices in the prior three sessions. Raffles +0.0 · IHH −1.0 · AoxinQM −10.6
20
30 May 2025
+6.0%
−0.6%
+0.5%
+5.5%
Residual
Against an index move of −0.6% and a peer median of +0.5%, about 5 points are left over; 4.4× median volume. No filing beyond routine notices in the prior three sessions. Raffles +0.5 · IHH +0.5 · AoxinQM +0.0
21
week to 27 Jun 2025
+17.1%
+2.1%
+0.0%
+17.1%
Residual
Weekly window, 20 to 27 June 2025: the largest move in the register, five consecutive gains of 1–4% a session on 7–15× median volume, from S$0.38 to S$0.445. The index rose 2.1%, Raffles Medical 1.1% and IHH fell 1.5%, so about 15 points survive both controls. No announcement was filed in the week; the nearest before it was the close of the Aoxin offer at 22:26 on 16 June, leaving Q&M with 52.65%, after which the shares had slipped 2.6% over four sessions. What the tape does record is who was buying: Quan Min Holdings, the CEO's vehicle, filed an open-market purchase after each of the five sessions, 9,241,300 shares for about S$3.9m in all and roughly half the volume reported for the week, taking Dr Ng's deemed interest from 55.03% to 55.78%. The level held until 3 July, when the shares fell 5.6% in the session before the S$130m bond pricing was filed at 21:57. Raffles +1.0 · IHH −1.5 · AoxinQM +0.0
22
week to 22 Aug 2025
+11.4%
+0.5%
−1.9%
+13.3%
Residual
Weekly window, 15 to 22 August 2025, beginning the session after the 1H2025 results, filed at 07:48 on 14 August (revenue flat at S$88.4m, PATMI down to S$3.9m from S$9.7m on a S$4.4m deemed-disposal loss from consolidating Aoxin, the company's figures), a session the shares closed flat on 12× median volume. The index rose 0.5% and both hospital peers fell, Raffles Medical 1.9% and IHH 2.4%, so the whole 11 points survive the controls. The rise came on 18 and 19 August (+3.5% and +4.5%, on 10× and 26× volume), after each of which Quan Min Holdings, the CEO's vehicle, filed an open-market purchase of 2,753,400 and then 2,888,400 shares. The week also included its sale of 20,000,000 shares to Lion Global Investors in an off-market married deal at S$0.45 a share, filed on 20 August, the 69×-volume session in the middle of the week, and company buy-backs of 1,206,300 and 1,011,500 shares on 21 and 22 August. The shares went ex the 0.40-cent interim dividend on 21 August (the series is adjusted for it) and continued to S$0.505 by 2 September; no reversal. Raffles −1.9 · IHH −2.4 · AoxinQM +0.0
23
22 Oct 2025
+6.4%
+0.3%
−1.0%
+7.4%
Residual
Against an index move of +0.3% and a peer median of −1.0%, about 7 points are left over; 12.7× median volume. No filing beyond routine notices in the prior three sessions. Raffles −1.0 · IHH +0.4 · AoxinQM −17.0
24
week to 24 Oct 2025
+10.6%
+2.1%
+0.0%
+10.6%
Residual
Weekly window, 17 to 24 October 2025: two sessions did the work, +6.4% on 22 October (13× median volume) and +4.0% on 24 October (22×), to S$0.52. The index rose 2.2%, Raffles Medical was unchanged and IHH rose 2.4% (Aoxin, in the middle of its 1-for-1 rights issue, printed −29.8%); about 11 points survive both controls. The two filings of substance came before the window: the undertaking to take up to S$15.3m of Aoxin's rights issue (13 October, 07:41) and the non-binding MOU for a Thai chain of more than 30 clinics at an enterprise value of THB 1.95bn (15 October, 21:11), after which the 16 October session had risen 3.3%. Inside the window the tape holds a 300,000-share buy-back on 21 October and, after each of the two moving sessions, a filed open-market purchase by Quan Min Holdings, the CEO's vehicle: 1,335,300 shares on 22 October and 3,273,800 on 24 October, a third and a half of those sessions' volume. The shares went on to S$0.535 on 29 October; no reversal. Raffles +0.0 · IHH +2.4 · AoxinQM −29.8
25
18 May 2026
+5.2%
+0.1%
+0.0%
+5.2%
Residual
Against an index move of +0.1% and a peer median of +0.0%, about 5 points are left over; 8.8× median volume. No filing beyond routine notices in the prior three sessions. Raffles −0.5 · IHH +1.0 · AoxinQM +0.0
26
29 May 2026
+5.8%
+1.0%
+2.1%
+3.7%
Sector-wide
Tracked the sector: against an index move of +1.0% and a peer median of +2.1%, about 4 points are left over. Raffles +2.1 · IHH +1.1 · AoxinQM +8.6
Key developments: sources, timing and notes
25 Jan 2024 · EM2AI, the group's dental-AI unit, ceded to a CEO-controlled vehicle: the investor puts in S$1,606,500 for 51%, Q&M converts S$1,443,500 of loans for 49%.Corporate actionReaction (next session, 26 Jan): QC7 +0.0% · STI +0.4% · peers +0.0% · 8.5× median volumeSource: SGX announcement, 25 Jan 2024 · Completion announcement, 5 Mar 2024
29 Feb 2024 · FY2023 results: revenue up 1% to S$182.7m and PATMI up 2% to S$11.5m; full-year dividend cut to 0.69 cents from 1.0 cent.ResultsReaction (next session, 1 Mar): QC7 +0.0% · STI −0.2% · peers +0.0% · 0.9× median volumeSource: SGX announcement, 29 Feb 2024 · Response to SGX query, 7 Mar 2024
12 Jun 2024 · Clarification of a Business Times interview: the CEO's figures of 10% revenue and 10-20% bottom-line uplift from the AI programme are 'expectations rather than quantifications of future profits'.AnnouncementReaction (next session, 13 Jun): QC7 −2.0% · STI +0.5% · peers +0.0% · 0.2× median volumeSource: SGX announcement, 12 Jun 2024
29 Jun 2024 · Acumen Diagnostics places its CEO Dr Ong Siew Hwa on leave pending an investigation into her indirect interest in a supplier's assets.AnnouncementReaction (next session, 1 Jul): QC7 +0.0% · STI +0.2% · peers +0.0% · 0.5× median volumeSource: SGX announcement, 29 Jun 2024
15 Jul 2024 · SIAC arbitral award in the group's favour against the minority holders of AR Dental Supplies: RM5,353,998 of dividends plus an RM8,400,000 buy-back with 10% interest from July 2013.AnnouncementReaction (next session, 16 Jul): QC7 −3.4% · STI −0.3% · peers +0.0% · 1.9× median volumeSource: SGX announcement, 15 Jul 2024 · Update on arbitral award, 21 Feb 2025
12 Aug 2024 · 1H2024 results: revenue up 2% to S$88.8m and PATMI up 84% to S$9.8m; interim dividend raised 150% to 0.40 cents.ResultsReaction (same session): QC7 +3.8% · STI −0.8% · peers +1.1% · 2.5× median volumeSource: SGX announcement, 12 Aug 2024 (released 07:58, before the open)
11 Sep 2024 · Binding MOU to buy the Veritas Dental clinic business at Bukit Timah for S$800,000 cash, with a vendor profit guarantee of S$1,018,839 over eight years.Corporate actionReaction (same session): QC7 +0.0% · STI +0.5% · peers +0.0% · 0.4× median volumeSource: SGX announcement, 11 Sep 2024 (released 08:00) · Completion announcement, 15 Nov 2024
23 Oct 2024 · Non-binding MOU to acquire 25% of Guangdong Delun Medical Group, a South China dental chain with one hospital, 28 clinics and more than 400 chairs.Corporate actionReaction (next session, 24 Oct): QC7 −3.2% · STI +0.1% · peers +0.0% · 9.8× median volumeSource: SGX announcement, 23 Oct 2024
1 Mar 2025 · FY2024 results: revenue down 1% to S$180.7m but PATMI up 27% to S$14.6m; full-year dividend raised to 1.1 cents and a buyback of up to 50 million shares announced.ResultsReaction (next session, 3 Mar): QC7 −1.8% · STI +0.3% · peers +0.0% · 4.2× median volumeSource: SGX announcement, 1 Mar 2025
22 Mar 2025 · Settlement with Dr Ong on confidential terms and no admission of liability; she resigns from Aoxin's board and Q&M withdraws its requisition for an Aoxin EGM.AnnouncementReaction (next session, 24 Mar): QC7 +1.7% · STI +0.3% · peers +0.0% · 1.8× median volumeSource: SGX announcement, 22 Mar 2025
17 Apr 2025 · Proposed secondary listing on Bursa Malaysia's Main Market; the same evening, a letter of demand to Aoxin's CEO Dr Shao for RMB72,274,588 (about S$13,009,426) of profit-guarantee shortfalls.Corporate actionReaction (next session, 21 Apr): QC7 +3.6% · STI +1.0% · peers +1.0% · 2.9× median volumeSource: SGX announcement, 17 Apr 2025 (secondary listing) · SGX announcement, 17 Apr 2025 (letter of demand)
30 Apr 2025 · Security enforcement takes 87,973,480 Aoxin shares from HFEL at S$0.0321 (S$2,823,949), lifting the concert-party stake to 50.53% and triggering a mandatory cash offer for the rest at S$0.0321.Corporate actionReaction (next session, 2 May): QC7 +3.4% · STI +0.3% · peers +4.3% · 5.5× median volumeSource: SGX announcement, 30 Apr 2025 (released 23:58) · Response to SGX queries, 7 May 2025
16 Jun 2025 · Aoxin offer closes: Q&M holds 269,323,546 shares, 52.65%, and Aoxin becomes a consolidated subsidiary.Corporate actionReaction (next session, 17 Jun): QC7 −1.3% · STI +0.6% · peers +0.0% · 0.3× median volumeSource: SGX announcement, 16 Jun 2025
3 Jul 2025 · Inaugural bond: S$130,000,000 of 3.95% notes due 2028 priced under the S$500m MTN programme, issued 10 July 2025.Corporate actionReaction (next session, 4 Jul): QC7 +0.0% · STI −0.1% · peers +0.0% · 5.0× median volumeSource: SGX announcement, 3 Jul 2025 · Issue announcement, 10 Jul 2025
24 Jul 2025 · Three Singapore clinic deals for S$730,000 in aggregate: a binding MOU for 49% of Sengkang Dental Surgery, and completed asset purchases of Citizen Dental and Bedok Dental.Corporate actionReaction (next session, 25 Jul): QC7 −1.2% · STI −0.3% · peers +0.0% · 0.9× median volumeSource: SGX announcement, 24 Jul 2025
25 Jul 2025 · Dr Shao Yongxin resigns as executive director and CEO of Aoxin, citing differences with Q&M over Liaoning strategy; Aoxin's audit committee had received a whistle-blowing report against him on 21 July.BoardReaction (next session, 28 Jul): QC7 −1.2% · STI −0.5% · peers +0.5% · 1.3× median volumeSource: SGX announcement, 25 Jul 2025
13 Oct 2025 · Aoxin launches a 1-for-1 rights issue at S$0.030; Q&M undertakes its S$8,079,706.38 pro rata entitlement and up to S$7,265,955 of excess shares, up to S$15,345,661.44 in all.Corporate actionReaction (same session): QC7 +0.0% · STI −0.8% · peers +0.0% · 0.5× median volumeSource: SGX announcement, 13 Oct 2025 (released 07:41)
15 Oct 2025 · Non-binding MOU to buy into a Thai dental chain of more than 30 clinics at an enterprise value of THB 1,950,000,000, paid in cash and moratorium shares, with net-income guarantees rising from THB 123m in 2026 to THB 285m in 2030.Corporate actionReaction (next session, 16 Oct): QC7 +3.3% · STI −0.3% · peers −0.8% · 2.4× median volumeSource: SGX announcement, 15 Oct 2025
11 Feb 2026 · Sengkang Dental acquisition completed; binding MOUs for Ann Arbor Dental Surgery at S$1,200,000 (30% in new shares) with a profit guarantee of up to S$800,000, and Southbank (TEETH @ Tiong Bahru) at S$400,000.Corporate actionReaction (next session, 12 Feb): QC7 −1.9% · STI +0.6% · peers −0.7% · 1.4× median volumeSource: SGX announcement, 11 Feb 2026 · Completion of Ann Arbor acquisition, 10 Jun 2026
28 Feb 2026 · FY2025 results: revenue up 9% to S$197.2m but PATMI down 35% to S$9.3m; cash S$117.1m against S$143.4m of borrowings and leases after the bond; full-year dividend cut to 0.82 cents and the buyback allocation raised to 90 million shares.ResultsReaction (next session, 2 Mar): QC7 −1.0% · STI −2.1% · peers −1.0% · 2.1× median volumeSource: SGX announcement, 28 Feb 2026 (released 23:05) · Replacement announcement, 1 Mar 2026
3 Mar 2026 · Q&M subscribes for 50,000,000 new Aoxin shares at S$0.1566 (S$7,830,000), a 10.0% discount to VWAP, alongside Aoxin's placement of up to 63,000,000 shares to third parties.Corporate actionReaction (same session): QC7 +1.0% · STI +0.5% · peers +0.0% · 1.5× median volumeSource: SGX announcement, 3 Mar 2026
4 Mar 2026 · Non-binding MOU to acquire 100% of a multi-clinic Singapore dental group for cash and 15-year-moratorium shares, backed by a profit guarantee of up to S$34,000,000 over five years.Corporate actionReaction (same session): QC7 −1.9% · STI −2.1% · peers −1.9% · 4.0× median volumeSource: SGX announcement, 4 Mar 2026 (released 07:50) · Media release, 13 Mar 2026
11 Mar 2026 · Non-binding MOU for an Australian network of more than 40 clinics and about 120 dentists at AUD144.5 million, with a seven-year profit guarantee of about AUD105.7m; the company later set an objective of about 400 Australian clinics in five years.Corporate actionReaction (next session, 12 Mar): QC7 +1.8% · STI −0.2% · peers +1.0% · 10.7× median volumeSource: SGX announcement, 11 Mar 2026 · Media release, 13 Mar 2026
31 Mar 2026 · Second security enforcement: the remaining 21,428,229 HFEL shares in Aoxin taken at S$0.180 (S$3,857,081), leaving Dr Shao owing RMB39,909,589 (about S$7,459,102).Corporate actionReaction (next session, 1 Apr): QC7 +0.0% · STI +1.8% · peers +0.0% · 1.5× median volumeSource: SGX announcement, 31 Mar 2026 (released 23:22)
12 Jul 2026 · Binding SPA for 51% of Deezy Dental Home in Thailand (33 clinics) at THB 994,500,000: THB 700m cash plus 16,375,714 new shares at S$0.70, a 25.7% premium to the S$0.557 VWAP, with a six-year profit guarantee of about THB 1,251,000,000.Corporate actionReaction (next session, 13 Jul): QC7 −0.9% · STI +0.0% · peers −0.5% · 2.2× median volumeSource: SGX announcement, 12 Jul 2026 (released 23:07) · Request for trading halt, 9 Jul 2026
12 Jul 2026 · SPA for 100% of Australia's Experteeth Group (40 clinics, about 120 dentists) at AUD119,635,712 plus an AUD30,364,288 equity injection; 70,337,143 new shares at S$0.70 and an eight-year profit guarantee of about AUD112,647,289; a major transaction needing an EGM.Corporate actionReaction (next session, 13 Jul): QC7 −0.9% · STI +0.0% · peers −0.5% · 2.2× median volumeSource: SGX announcement, 12 Jul 2026 (released 23:09) · Update on proposed secondary listing, 12 Jul 2026
14 Jul 2026 · Corporate update presentation published: an 'illustrative' five-year scenario takes group revenue from S$197.2m to S$424.9m and PATMI to S$45.8m by year five on the profit guarantees, which the company said is not a forecast.Business updateReaction (same session): QC7 −0.9% · STI +0.5% · peers −0.7% · 0.5× median volumeSource: Media release and presentation, 14 Jul 2026
14 Aug 2026 · 1H2026 results: revenue up 13% to S$99.5m and PATMI up 27% to S$4.9m against a half that carried the S$4.4m deemed-disposal loss; interim dividend unchanged at 0.40 cents.ResultsReaction (same session): QC7 +0.9% · STI +0.4% · peers −0.6% · 3.2× median volumeSource: SGX announcement, 14 Aug 2026 (released 07:05, before the open)
16 Aug 2026 · Non-binding MOU to sell 60% of EM2AI to Catalist-listed Medi Lifestyle for 138,000,000 new Medi Lifestyle shares at S$0.049, about S$6.76m, with the EM2Clinic management system carved out first.Corporate actionReaction (next session, 17 Aug): QC7 +0.9% · STI +0.4% · peers +0.4% · 0.3× median volumeSource: SGX announcement, 16 Aug 2026
Every other test on this page waits for the company to file. These do not. Each row is a series you can look up yourself, free, today — with the level this reading was built against, the levels that would put it in question, and what the series cannot tell you.
dental clinics and distribution — nothing public to watch
Searched the health ministry's statistics, the dental council's practitioner register and the national retail-sales index. The practitioner register is public and free but counts dentists nationally rather than at this network's outlets, and private dental demand is not separately published; the outlet count and revenue per outlet, which are what actually move the earnings, come from the issuer.
Watchlist reviewed on 2026-08-27; each observation has its own date above. This watchlist date does not change the company research cutoff. A series moving past a level is a reason to re-read the case, not a recommendation. The same series across every company covered: what you can watch.
Notes and sources
18 · Questions the filings do not answer
Each entry names a figure or mechanism the filings do not provide, and what would resolve it. These are gaps in the public record rather than criticisms: several could be answered in a single line, and their resolution could support or weaken any reading of the company. This page takes no view on the shares. Items 9 to 19 were added on 24 August 2026.
The China centre count does not reconcile. Aoxin's own 23 March 2026 announcement states 14 dental centres — 7 hospitals and 7 polyclinics — across seven Liaoning cities. Q&M's 1H2026 release states 4 hospitals and 7 polyclinics, being 11. Only one closure was announced between the two dates. Either the two count on different bases, or two further hospitals closed without separate disclosure. No China outlet figure is printed anywhere on this page. Resolving it needs Aoxin's FY2025 annual report.
What drove the S$10.1m increase in non-controlling interests over 1H2026. The statement of changes in equity as filed does not explain it.
An outlet roll-forward — opened, acquired, closed. Not disclosed, so the mechanism behind the net outlet movement cannot be attributed.
The Experteeth Rule 1014 circular and its independent financial adviser's opinion. Not published as at the cut-off date; the company has announced no date.
Any independent valuation of any of the four acquisition targets. None exists from any source; none was required and none was obtained.
Guarantee mechanics for the two Aoxin memoranda — waterfall, escrow operation, put option, personal guarantees. Not disclosed at all, and whether Aoxin can fund RMB 263m of cash consideration is not evidenced.
The realisable value of 138,000,000 Medi Lifestyle shares, were the EM2AI disposal to complete. The consideration is illiquid sub-5-cent Catalist paper.
A like-for-like organic revenue series across all years. Segment definitions changed in FY2024 and the consolidation perimeter changed in FY2025; the company publishes no bridge, which is why this page anchors on the single clean 1H2026 comparison in section 3.
Whether the dentist headcount and patient-visit figures are current measurements.
Every results release from FY2022 through 1H2026, and the 14 July 2026 corporate update, describes the
Singapore business as about 270 experienced dentists seeing roughly 40,000 patient visits a month
— while the Singapore outlet count in those same sentences moves from 107 to 114. The FY2025
annual report instead says about 42,000 visits. No dated headcount or patient-visit series is
published, so whether these are current figures or standing description cannot be established from
the filings.
The sums held in, and withdrawn from, the Aoxin escrow. The 30 April 2025
announcement discloses that the Aoxin profit guarantee was secured by an escrow account which the
guarantor was required to fund and to replenish after any withdrawal, alongside security over his
Aoxin shares. No amount deposited, withdrawn or outstanding under that escrow appears in any filing.
It is the only instance in which this two-part structure has been tested.
Cash actually received against profit guarantee income. The income recognised
across FY2019–FY2025 and the receivable balance are both disclosed; the cumulative amount
settled in cash is not.
How many vendor profit guarantees are in arrears, and the aggregate outstanding.
The 1H2026 statement discloses, under Recent Developments, an enforcement completed on 19 May 2026
recovering S$1,320,713 owed by a counterparty separate from the one named in the 2025 and 2026
security-enforcement announcements. No group-wide count or aggregate is published.
The profit guarantee receivable at 30 June 2026. The 1H2026 statement does not
disclose the gross balance, the loss allowance or the net balance separately, so the closing position
after the May enforcement cannot be derived from the filing.
Whether security is held over the property cited in the audit report. The FY2025
audit report records that the recoverability assessment referred to a valuation report on a property
identified as a source of recovery. Whether a registered charge is held over it, and where it would
rank, is not disclosed.
Whether the Australian profit guarantee is joint and several. The Australian SPA
states that each seller's obligations are guaranteed by its respective guarantor. The Thailand
SPA, announced the same day, states that its obligors are jointly and severally liable. The
construction of the Australian obligation is not stated.
Whether the issuer's pro-forma financial effects are struck before Australian tax and
acquisition interest. The announcement sets out the assumptions behind the illustration;
neither Australian tax on the acquired earnings nor interest on the acquisition borrowings appears in
that list.
How the AUD 30,364,288 equity injection is applied. AUD 364,288 is identified as
working capital. The application of the balance is not disclosed, and neither are Experteeth's
own gross borrowings and lease liabilities, so the acquired capital structure cannot be
reconstructed.
Committed undrawn facilities at the Company. The 1H2026 balance sheet reports the
group and the Company in separate columns. Facilities available to the Company, and whether they are
committed or repayable on demand, are not disclosed.
Whether the Singapore revenue movement was price or volume. The geographical note
gives Singapore revenue for each half. No split between the number of patient visits and the average
fee per visit is published.
Download
A print-ready PDF of this page, for reading away from the screen: Q&M Dental Group evidence library (PDF). It carries the same content as this page — the three FY2025 profit numbers, the core business, the track record, acquisition-shortfall income and its receivable, the network, the balance sheet, funding and the MTN covenants, where the cash went, the four acquisitions, pro-forma effects, China, EM2AI, the events timeline, the accounting events, the share price and open questions — and the same omissions: no rating, no fair value, no forecast.
19 · Corrections log
Figures on this page that changed after publication, and why. Fuller detail, including what independent review found, is in the assurance note.
Item
Was
Now
Singapore revenue direction, 1H2026
“fell 1.3%”, presented as the headline operating fact
Both readings shown. Profit-guarantee income fell S$1,222k against a S$1,032k Singapore decline, so net of it Singapore grew 0.24% and Singapore + Malaysia 1.20%
Singapore and Malaysia outlet counts, FY2020 and FY2021
85 and 99, from the undated corporate-profile blurbs
83 and 97, from the operational review. FY2022 and FY2024 shown as n.a. rather than interpolated
Revenue per outlet
Published as a productivity series
Withdrawn. The numerator includes distribution, guarantee income and consolidated Aoxin, so it does not measure outlet productivity
EM2AI entry against proposed exit
Compared directly
Marked non-comparable: EM2Clinic is carved out of the disposal perimeter
Thailand shortfall protection
Described as a dividend waiver rather than escrowed cash
A THB 48,740,000 cash escrow exists, plus personal guarantees and a put option
Australian escrow cover
7.1% of the 8-year cumulative guarantee
Both bases shown: 37.0% of the first two-year test block, which is how the guarantee is tested, and 7.1% of the lifetime total
Aoxin ownership
54.7%
52.6%. The 54.74% figure applies after the Second Security Enforcement completes and is phrased as an intention
Acquisition cash requirement
S$102.7m
S$95.5m. Both escrows are carved out of the cash already being paid, not additional to it
FY2024 restatement
Described as wholly an error correction
Two unrelated changes: a S$373k NHSA error correction, and a segment presentation reclassification netting to zero at group level
Undrawn MTN programme capacity
Referred to as headroom and an intended funding route
An issuance framework, not committed liquidity; not treated as available headroom
Separate Aoxin Vendor 1 shortfall
RMB 2,234,150 described as outstanding
The 5 June filing says it was fully repaid in cash across Tranches 2 to 6; Vendors 2 and 3 had no outstanding shortfalls
Q&M annual reports FY2009–FY2025 and the half-year and full-year results series to 1H2026 (released 14 August 2026); the Experteeth and Deezy sale-and-purchase announcements of 12 July 2026 including their section 7 pro-forma financial effects; the MTN information memorandum of 30 June 2025 including the Condition 4(b) covenant package; the 2009 placement and admission documents; the Second Security Enforcement announcement of 31 March 2026; the EM2AI acquisition and disposal announcements; Aoxin Q&M (SGX Catalist: 1D4) announcements including the 1H2026 results, the March and April 2026 memoranda of understanding, the Panjin closure, the 4 May 2026 placement completion, the 5 June 2026 profit-guarantee outcome, the 4 July 2026 former-director update and the 13 August 2026 SGX query response; and Ministry of Health registered-dentist counts via data.gov.sg. Where two of the issuer's own documents disagree, both figures are recorded and the audited annual report governs.
A note on the Aoxin source set. This page does not describe the Aoxin announcement record as a complete tape. The subsidiary's issuer announcement page was unavailable and the exchange enumeration route throttled during the 20 August refresh, so the set is described as the filings actually retrieved and read rather than as exhaustive. (O)
Reader questions & corrections
Ask about this company, challenge a source or suggest a factual correction. Only selected questions that SMID Research has reviewed and answered are published.
Submissions are private by default. Your email is encrypted and never published. Please do not send confidential or inside information, allegations about individuals, promotions, or requests for personalised investment advice.
Behind the lock. Author-only research notes remain private in the password-protected author vault 🔒.
Transcripts
Find available event transcripts in the transcript library.