Zhejiang DunAn makes refrigeration components, air-conditioning equipment and automotive thermal-management products for manufacturers.
Latest figures
In 1H2026 revenue rose 7.45% to RMB7.231bn, profit attributable to owners fell 12.79% to RMB466.8m and operating cash flow rose 71.12% to RMB546.9m; FY2025 cash after capital expenditure was about RMB1.071bn.
Main risk
The central risk is that automotive growth and refrigeration competition dilute margins or consume more capital than the repaired funding structure can support.
Next proof
The next test is the next filing's segment margin, automotive cash conversion and debt trend.
1H2026 revenue
CNY7.231bn
1H2026 PATMI
CNY0.467bn
1H2026 CFO
CNY0.547bn
Cash equivalents
CNY3.469bn
Borrowings
CNY0.714bn
Reporting
Quarterly · FY ends 31 Dec
This public page carries no proprietary rating, fair value, expected return, credit outlook or recommendation. Information cut-off: 28 August 2026; official tape monitored through 28 August. The 1H2026 result and post-result guarantee, hedge and accounting-policy filings are incorporated; the integrated model, decision and factual catalyst/falsifier set have been rebuilt behind the private vault boundary. R = primary source · D = derived from primary inputs · O = opinion/question.
Evidence balance
The live questionAs automotive thermal management grows, does it convert into segment margin and operating cash, or only into revenue mix?In 1H2026 automotive thermal management revenue rose 25.89% while profit attributable to owners fell 12.79%, so the automotive line is expanding into a period of falling reported earnings.
What improved
Revenue rose 7.45% year on year to CNY7.231bn in 1H2026 and operating cash flow rose 71.12% to CNY546.9m; refrigeration equipment revenue rose 35.03% and automotive thermal management 25.89%, so both lines grew alongside better reported cash conversion.
What became more demanding
PATMI fell 12.79% to CNY466.8m and component gross margin slipped 0.53 percentage point to 17.25%; the 1H2026 cash bridge leaned on operating payables of about CNY874m while receivables and inventory absorbed about CNY578m and CNY356m. Separately, the debt and security disclosures record pledged receivables financing of CNY0.765bn and restricted cash of CNY0.266bn.
Strongest alternative explanation
The pattern could reflect timing: inventory partly unwound to CNY1.688bn at June. FY2025 disclosed automotive revenue and costs imply a 23.3824% gross margin. This is neither EBIT nor a measure of cash conversion or return on capital; lower component gross margin alone does not establish weaker automotive economics.
The decisive missing fact
The decisive disclosures are the automotive thermal contribution margin, utilisation and returns on incremental capex, together with how much of the 1H inventory and receivables build is backed by firm customer schedules and what its ageing is.
Drawn from the evidence on this page: the improvement, the constraint, the benign reading and the fact that would settle it. It states no view on the shares.
About the private research record
A refreshed integrated write-up, formula-linked financial/valuation/credit workbook, canonical model outputs and independent-review disposition exist behind the rated view 🔒. They are private, access-controlled and not part of this public evidence library.
On this page
Business anatomy · from inputs to customer value
DunAn components sit inside larger cooling and thermal systems
The company supplies valves, heat exchangers, piping and equipment to HVAC, refrigeration and automotive manufacturers rather than most end users directly.
Follow the operating chain from demand or inputs to customer outcome and cash.
InputsIndustrial materials
Source thermal components
What happensMetals, electronics and other thermal-management inputs enter the production system.
Capital at workPurchased material and working capital precede the sale.
Company actionManufacturing
Make the control hardware
What happensDunAn manufactures valves, heat exchangers, piping and related thermal equipment.
Value createdPrecision conversion creates the component sold to the system maker.
Customer integrationOEM integration
Fit inside the larger system
What happensCustomers integrate the components into refrigeration, air-conditioning or vehicle thermal-management systems.
Revenue triggerThe HVAC, refrigeration or automotive manufacturer is the direct payer.
End-market exposureEnd use
Control heat and cooling
What happensThe completed system manages temperature in buildings, cold chains or vehicles.
Demand driverEnd-market demand reaches DunAn through OEM production volumes.
Original SMID Research comic. AI-assisted, analyst-directed monochrome artwork depicts the evidenced operating steps of Zhejiang DunAn Artificial Environment Co., Ltd.; deterministic captions and dated mix figures state the economics using issuer disclosures available to 2026-08-28. The drawings are representative—not issuer artwork, an exact product or site design, a statement of scale, or a company forecast.
Investor translation
What matters after the operating picture
Four questions connect the business model to cash and balance-sheet risk. This is a factual reading aid, not a valuation or recommendation.
Value lever
Normalized component earnings and margin recovery after raw materials, warranty and capital spending.
Cash bottleneck
Inventory, receivables and project work absorb cash before customers pay.
Balance-sheet pressure
Accessible cash after guarantees cannot cover current debt and working-capital needs.
Next proof
Core margin, operating cash, capex, guarantees and the exact earnings anchor used for valuation.
Text version of this comic
Inputs · Source thermal components Metals, electronics and other thermal-management inputs enter the production system. Capital at work: Purchased material and working capital precede the sale.
Company action · Make the control hardware DunAn manufactures valves, heat exchangers, piping and related thermal equipment. Value created: Precision conversion creates the component sold to the system maker.
Customer integration · Fit inside the larger system Customers integrate the components into refrigeration, air-conditioning or vehicle thermal-management systems. Revenue trigger: The HVAC, refrigeration or automotive manufacturer is the direct payer.
End-market exposure · Control heat and cooling The completed system manages temperature in buildings, cold chains or vehicles. Demand driver: End-market demand reaches DunAn through OEM production volumes.
1 · What the company is
DunAn manufactures refrigeration and air-conditioning components, refrigeration equipment and automotive thermal-management products. The product set described by the issuer includes valves, heat exchangers and piping. The group reports 20 production bases and a make-to-order model. Gree Electric Appliances controls 38.13%; because Gree Electric reports no actual controller, DunAn reports no actual controller. (R)
Economic engineRevenue × operating margin becomes cash only after tax, capex and working capital. Segment growth is therefore less useful without margin, receivable, inventory and reinvestment evidence. (D)
2 · Eleven-year balance-sheet repair
CNYbn
FY2015
FY2020
FY2023
FY2024
FY2025
Revenue
5.859
7.381
11.382
12.678
13.035
PATMI
0.082
−1.000
0.738
1.045
1.078
CFO
0.269
0.437
0.812
1.161
1.440
Gross borrowings
3.264
3.468
1.739
1.416
0.728
Cash
1.002
1.552
3.003
3.200
3.469
Independently re-keyed from FY2015–FY2025 annual reports. Gross borrowings = short-term borrowings + current portion + long-term borrowings + bonds payable; the integrated model additionally includes lease liabilities. (R/D)
The evidence shows a material change in financial posture: revenue expanded while gross borrowings fell to less than one quarter of the FY2015 level. FY2025 operating cash flow exceeded PATMI by 34%, and cash capex was CNY0.369bn, leaving CNY1.071bn of cash flow after capex. (D)
Fastest-growing pillar; derived FY2025 gross margin 23.3824% = (CNY1,234,029,443.63 revenue − CNY945,483,138.42 cost) / revenue. This is not EBIT or ROIC. FY2025 annual report, pp. 183–184.
Other
CNY0.800bn
+5.4%
Lower analytical visibility.
Domestic revenue was CNY10.865bn at a 17.0% gross margin; overseas revenue was CNY2.170bn at 25.8%. The margin gap may reflect product and customer mix and is not enough by itself to infer structural overseas pricing power. (R/O)
4 · FY2025 cash conversion
CNYbn except ratios
FY2023
FY2024
FY2025
PATMI
0.738
1.045
1.078
Operating cash flow
0.812
1.161
1.440
Cash capex
0.430
0.442
0.369
CFO / PATMI
1.10×
1.11×
1.34×
Inventory fell from CNY1.660bn to CNY1.335bn in FY2025, while accounts receivable and receivables financing increased. The cash improvement is real in the audited statements, but the working-capital burden did not disappear. (R/D)
Revenue rose 7.45% year on year to CNY7.231bn, while PATMI fell 12.79% to CNY466.8m and adjusted PATMI fell 9.70% to CNY466.6m. Operating cash flow rose 71.12% to CNY546.9m. Refrigeration-component revenue fell 1.96%; refrigeration equipment rose 35.03%; automotive thermal management rose 25.89%; and other revenue rose 88.79%. Component gross margin slipped 0.53 percentage point to 17.25%. (R/D)
The 1Q inventory build partly unwound to CNY1.688bn at June, but the cash-flow bridge still depends on timing: operating payables contributed about CNY874m while receivables and inventory absorbed about CNY578m and CNY356m respectively. Cash equivalents were CNY3.469bn against CNY0.714bn of short- and long-term borrowings. The result is mixed rather than a clean confirmation of the prior private thesis. (R/D/O)
Post-1Q capital events. The current legal share count is 1,074,477,339 after a completed cancellation. A CNY0.10-per-share dividend totalling CNY107.448m was paid on 11 August 2026. A further 1,118,466 options became exercisable, equivalent to 0.104% of current shares before any treasury-stock-method offset; a separate 492,479-share cancellation remained pending the 25 August shareholder vote at the cutoff. (R/D)
6 · Debt, security and guarantees
Disclosure
Amount
Interpretation
Gross debt + leases
CNY0.733bn
Low relative to CNY3.181bn cash equivalents.
Undiscounted maturity within one year
CNY0.242bn
Headline cash covers the disclosed bucket.
Undiscounted maturity, one to three years
CNY0.270bn
Spread beyond the next twelve months.
Undiscounted maturity after three years
CNY0.286bn
Longer-dated portion.
Restricted cash
CNY0.266bn
Not treated as freely accessible.
Pledged receivables financing
CNY0.765bn
Material encumbrance.
Actual guarantees at FY2025 year-end
CNY0.050bn
Year-end actual balance.
Actual guarantees at 29 Apr 2026
CNY0.351bn
5.27% of FY2025 parent net assets.
Guarantee programme ceiling
CNY1.800bn
Capacity, not current exposure.
Actual guarantees at 27 Aug 2026
CNY0.330bn
4.95% of FY2025 parent net assets; includes a new CNY0.300bn guarantee for the wholly owned Thailand unit.
Cumulative transaction amount; margin and premium ceiling CNY0.060bn.
No external committed/uncommitted facility split, covenant definitions, covenant headroom or legal-entity cash map was located. The page therefore does not claim unused committed liquidity or fully fungible consolidated cash. (R/O)
7 · Group finance-company exposure
FY2025 deposits with Gree Finance were CNY0.299bn; loans were nil after a CNY0.300bn loan repayment. The 2026 framework sets a CNY0.300bn deposit cap and CNY1.500bn credit limit. The special audit stated that the disclosed schedule was prepared in all material respects. The credit limit is not labelled a committed external bank facility. (R)
The five-year record
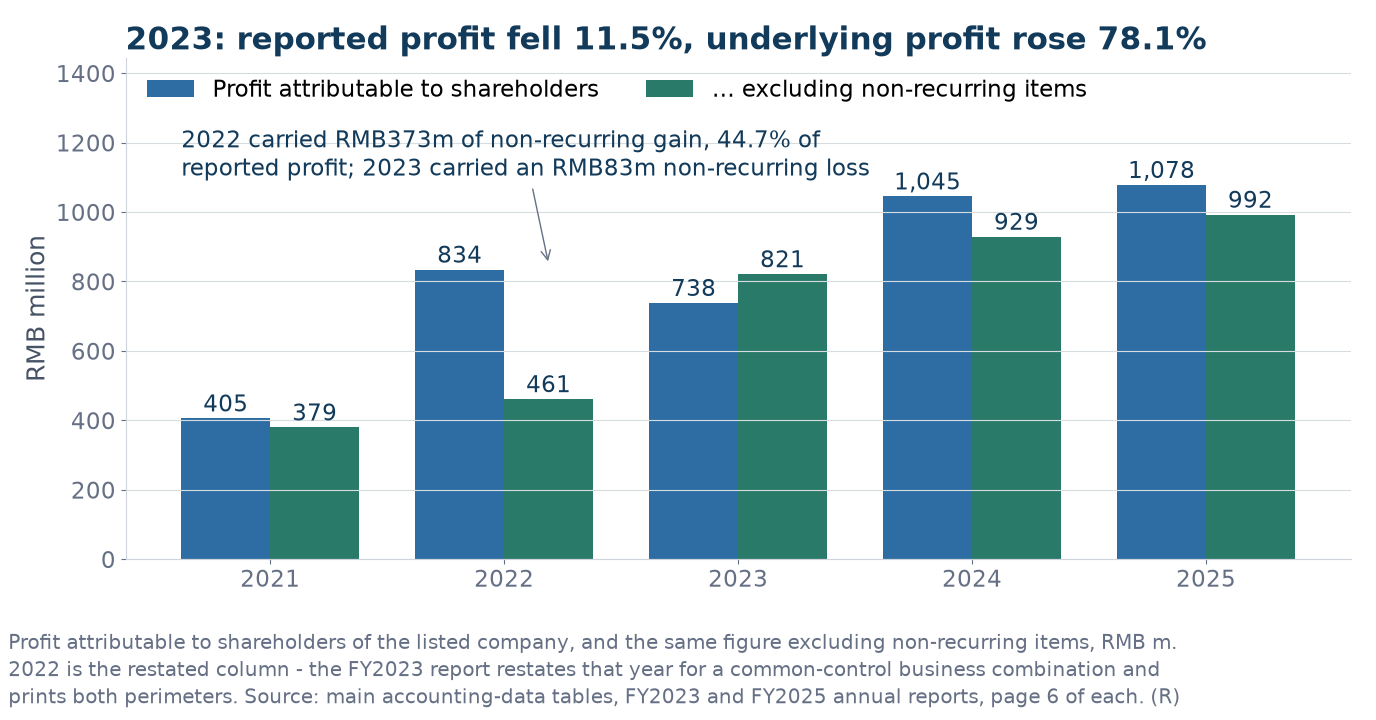
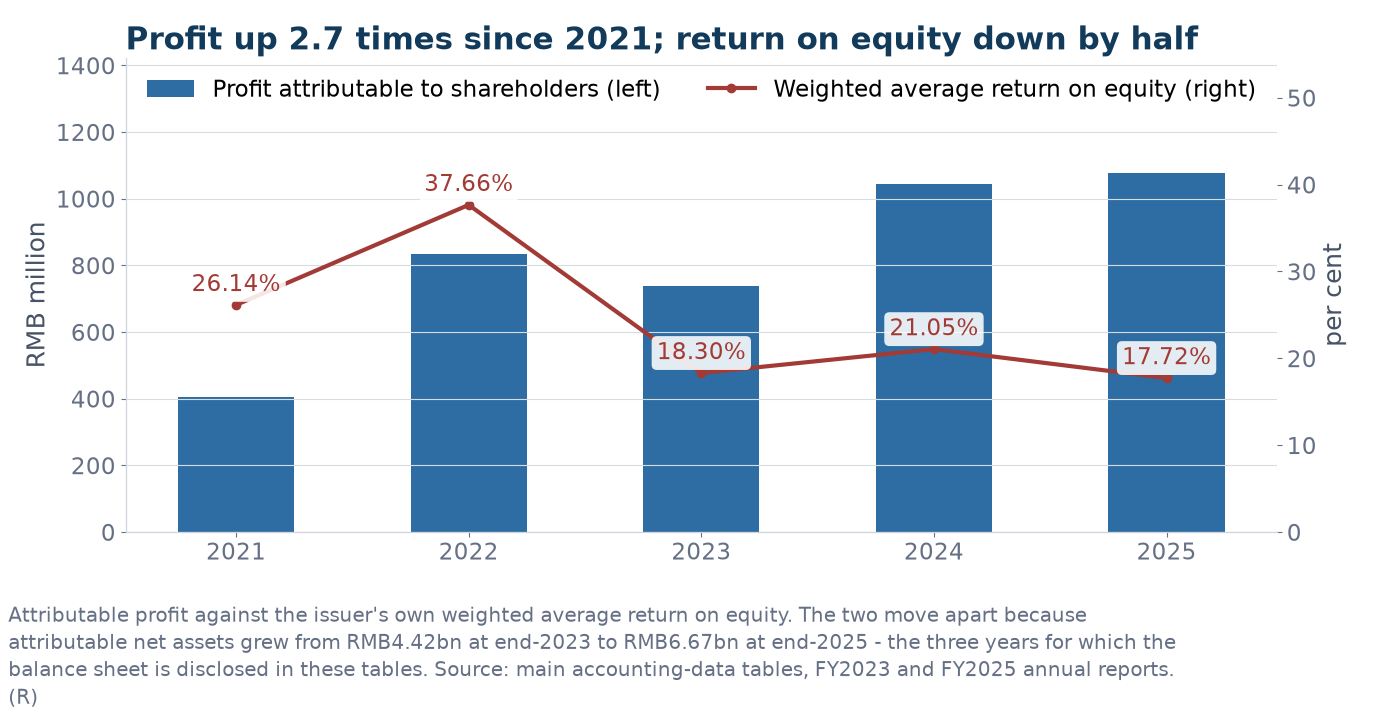
The five-year record, RMB million, from the main accounting-data tables of the FY2023 and FY2025 annual reports. FY2022 is the restated column. The FY2023 report restates that year for a common-control business combination and prints both versions; the restated figures are used throughout here, because mixing the two would splice two different perimeters.
RMB m unless stated
2021
2022
2023
2024
2025
Revenue
9,837.0
10,208.9
11,382.4
12,678.4
13,034.5
Profit attributable to shareholders
405.4
834.0
738.0
1,044.9
1,077.9
… excluding non-recurring items
379.4
460.9
820.8
928.8
992.2
… non-recurring share of reported
6.4%
44.7%
−11.2%
11.1%
8.0%
Operating cash flow
517.7
1,268.4
811.8
1,160.6
1,440.2
Basic earnings per share (RMB)
0.44
0.91
0.70
0.99
1.02
Weighted average return on equity
26.14%
37.66%
18.30%
21.05%
17.72%
Total assets
n/a
n/a
10,783.0
12,153.3
12,290.2
Net assets attributable to shareholders
n/a
n/a
4,417.3
5,509.5
6,666.4
The two bolded rows are why this table is worth reading rather than the headline. Reported profit fell 11.5% in 2023, and underlying profit rose 78.1% in the same year. Both are the issuer’s own numbers. In 2022 non-recurring items contributed RMB373m, 44.7% of reported profit; in 2023 they were a net RMB83m loss. So the apparent decline is entirely an artefact of what sits outside the operating business, and the direction of travel reverses depending on which line is read. On the underlying line profit has risen every year since 2021. The return-on-equity row moves the other way and for a different reason: it more than halves from 37.66% to 17.72% while profit roughly doubles, because attributable net assets grew from RMB4.42bn to RMB6.67bn over the three years the balance sheet is disclosed here.
The two profit lines and the year they disagree. Reported profit fell 11.5% in 2023 while profit excluding non-recurring items rose 78.1%; both percentages are the issuer’s own. 2022 is the restated column. Source: main accounting-data tables, FY2023 and FY2025 annual reports. (R)Attributable profit against the issuer’s own weighted average return on equity. The two move apart because attributable net assets grew from RMB4.42bn to RMB6.67bn over the three years the balance sheet is disclosed. Source: as above. (R)
FY2025, as filed
FY2025 revenue by segment, as filed. Components are 75.5% of revenue — this is a components manufacturer with three much smaller businesses attached, not a diversified group. Automotive thermal, the segment the equity story usually rests on, is 9.5%. The four segments sum to the reported revenue line exactly.
Segment
RMB m
Share
Components
9,837.7
75.5%
Automotive thermal
1,234.0
9.5%
Refrigeration equipment
1,163.0
8.9%
Other
799.8
6.1%
Total revenue
13,034.5
100.0%
FY2025 cash and debt, as filed, RMB million. The group ended the year with RMB2.45bn of net cash against RMB733m of gross debt including leases, and generated RMB1.44bn from operations while investing only RMB332m. The cash walk reconciles: RMB2,733.6m opening plus RMB447.3m net change gives the RMB3,180.8m closing balance.
RMB m
Operating cash flow
1,440.2
Investing cash flow
(332.5)
Financing cash flow
(651.0)
Effect of exchange rates
(9.4)
Net change in cash
447.3
Cash at 1 January 2025
2,733.6
Cash at 31 December 2025
3,180.8
Gross debt including leases
733.2
… of which current
243.3
Net cash
2,447.7
Total assets were RMB12,290.2m against liabilities of RMB5,631.5m and equity of RMB6,658.8m, and profit attributable to owners was RMB1,077.9m. Every figure here is a registered claim from the FY2025 report; the pack holds no earlier year on the same basis, so no multi-year series is shown rather than one being assembled from mixed sources.
8 · Who controls it, and what that cost
The change of control, from the announcements filed at the time and the FY2025 annual report. Amounts as stated by the issuer.
Date
What the filings record
16 November 2021
Gree Electric Appliances of Zhuhai (SZSE 000651) signs a share transfer agreement with Zhejiang Dun’An Precision Industry Group, the then controlling shareholder, for 270,360,000 shares — 29.48% of the share capital — at a stated consideration of about RMB2.190bn. Gree agrees separately to subscribe 139,414,802 new shares for about RMB810m. The announcement states that on completion Gree will have the right to reorganise the board and nominate more than half the directors.
24 February 2022
The State Administration for Market Regulation issues its decision not to prohibit the concentration.
27 April 2022
Transfer registration completes. Dun’An Precision goes from 270,360,000 shares to nil; Gree goes from nil to 270,360,000. The controlling shareholder becomes Gree Electric and the actual controller becomes nobody — the announcement states that because Gree Electric itself has no actual controller, DunAn’s actual controller changes from Yao Xinyi to a state of having none.
13 December 2022
Gree pays RMB809,999,999.62 for the placement. Net of RMB10,866,212.50 of issue costs the company receives RMB799,133,787.12.
6 January 2023
The 139,414,802 new shares list, priced at RMB5.81, locked up for 36 months. That lock expired in early January 2026, within this page’s window.
31 December 2025
Gree holds 409,774,802 shares, 38.13% of a share capital of 1,074,677,139 — 1,065,436,182 at the start of the year, less 834,043 restricted shares repurchased and cancelled, plus 10,075,000 incentive shares listed on 18 December 2025.
Gree paid 39% more per share for control than for the new shares it subscribed a year later. RMB2.190bn for 270,360,000 shares is RMB8.10 each; the placement was struck at RMB5.81, the floor being 80% of the twenty-day average before the pricing base date. The difference is what the control block was worth over the market: the first purchase bought the right to reorganise the board, the second bought only stock.
The FY2025 annual report discloses an unresolved competition problem between DunAn and its own controlling shareholder, and it has a deadline. Under the heading for horizontal competition the report names Gree Electric, gives the cause as the 29.48% acquisition, and records Gree’s written undertaking to resolve the existing competition within five years of completion of the acquisition — by merger or restructuring, asset disposal, equity transfer, entrusted operation, entrusted shareholding, or by granting new business opportunities to DunAn. Dating that deadline needs care. The undertaking runs five years from completion of “本次收购”, and the acquisition report defines that term as the share transfer and the placement together, not the transfer alone. The transfer completed 27 April 2022 and the placement only on 6 January 2023, so the five years run to January 2028 on the definition the documents use, rather than to April 2027 as the transfer date alone would suggest. Either way the report published in April 2026 still lists the matter as outstanding. The undertaking terminates early on one condition only: that Gree ceases to be the controlling shareholder.
The same undertaking gives DunAn a right of first refusal with a clock on it. If Gree or its other subsidiaries obtain a business opportunity that substantially competes with DunAn’s main business — minority financial investments excepted — Gree will notify DunAn in writing, and if DunAn replies in writing within 30 days that it wants the opportunity, Gree will use its best efforts to see it offered to DunAn first on reasonable and fair terms. The filings do not say how many times that notice has been given.
Roughly a fifth of revenue is sold to the controlling shareholder’s group. The 2024 annual general meeting, held 19 June 2025, approved a cap of RMB3.200bn on ordinary-course related-party transactions with Gree Electric and its subsidiaries for 2025. The actual figure was RMB2.832bn — 88.5% of the cap. That total is not all sales: the report splits it into RMB2.689bn of goods and services sold to the Gree group and RMB0.143bn bought from it, and prints the sales ratio in its own column as 20.63% of revenue. Across all related parties, sales of goods and services came to RMB2.689bn against RMB2.477bn the year before, a rise of 8.5%. The cap is a governance limit rather than a commercial one, but it does put a number on how much of this company’s trade its controlling shareholder can absorb before a fresh shareholder vote is needed.
What the share price did, and how much of it was DunAn Environment
Over the window DunAn Environment returned −19.5% on a dividend-adjusted basis; the SZSE Component Index returned +35.9% and the median of the 3 listed comparisons +23.7%.
The detector flagged 26 large moves in the window — 20 single sessions and 6 weekly windows — before any news was read. 3 market moves, 3 sector moves; 20 are left over after both controls, unexplained by them. Of those, 5 coincided with one in the same session or week and 15 have nothing filed against them beyond routine notices and are recorded as unexplained rather than explained away.
This section records the 36-month price history and puts every large move through two subtractions and reports what is left over, not what caused it: first the SZSE Component Index, then the median of the 3 listed comparisons — Sanhua Intelligent Controls, Hisense Home Appliances and Vatti — which trade the same session. “Left over” is what survives both controls.
Each quarter below pairs two records. Key developments are the filings that carry information — periodic reports, earnings pre-announcements and warnings, profit distributions, stake moves by the controller and major holders, incentive plans, regulatory letters — with the figures as filed, the guidance given, the close on the day and how the reacting session traded against the controls; a filing after the 09:30 open is read against the next session. Large price moves are the threshold-detected sessions, detected before any news was read and dispositioned from the controls and the enumerated tape; rows with a written note carry a numbered pin, the rest are dots on the line.
Click a quarter — on the chart or in the return strip under it — to read its filings beside its large moves.
Key: DunAn Environment (002011) as a solid line; SZSE Component Index rebased, dashed; peer median rebased, dotted; the benchmark runs off scale from Feb 24 and is clipped there; the peer median runs off scale from Apr 24 and is clipped there; filing ticks above the axis; ex-dividend ticks on it; numbered pins are moves with a written note; plain dots are other detected moves.
How to read the tags.Market-wide and Sector-wide mean the index or the peer median moved with the share over the same session or week; Residual means the move is still large after both are subtracted. A residual is what is left over, not a cause: it does not establish that the company’s own news moved the price, and an unchanged or thinly traded price is not proof that no information arrived. Returns use the dividend-adjusted close; a filing released after the open is read against the next session.
Q3 2023
22 Aug 2023 – 28 Sep 2023 (part quarter)
002011 −10.3%SZSE −2.6%Peer median +2.4%Range RMB 10.93–RMB 12.56Close RMB 11.12
Key developments
24Aug
RMB 11.76Results
1H2023 results: revenue up 13.95% to RMB 5.573bn, net profit down 44.15% to RMB 329.1m after a contingent-liability charge; recurring profit up 58.94% to RMB 422.1m.
The reported decline reflects non-operating expenses of RMB 103.1m, which the company attributed to contingent liabilities confirmed under court rulings and a tripartite payment agreement over the 2019 disposal of the Tianjin energy-saving business, against prior-year non-recurring gains of RMB 323.6m (computed). Refrigeration components revenue rose 9.72% to RMB 4.298bn at a 20.06% gross margin, up 4.22 points; refrigeration equipment fell 0.95% to RMB 684.7m; EV thermal management rose 158.46% to RMB 136.9m. Overseas revenue was flat at RMB 1.012bn at a 30.58% margin. Operating cash flow was an outflow of RMB 173.9m, attributed to less discounting of supply-chain finance instruments; financing inflows were RMB 395.0m on new borrowings. Comparatives were restated for the common-control purchase of Zhuhai Ligao Precision from Gree Electric. No interim dividend.
24 Aug 2023 · −6.4% · Residual · index +1.0%, peers +1.8%, left over −8.2%
Against an index move of +1.0% and a peer median of +1.8%, about 8 points are left over; 1.9× median volume. Coincided with the filing “关于开展外汇套期保值业务的可行性分析报告” (release order not established).
002011 +23.7%SZSE −5.8%Peer median −0.8%Range RMB 10.03–RMB 13.75Close RMB 13.75
Key developments
27Oct
RMB 11.03Results
3Q2023: revenue up 18.56% to RMB 2.872bn and net profit up 98.27% to RMB 211.1m; nine-month net profit down 22.36% to RMB 540.2m.
Nine-month revenue rose 15.48% to RMB 8.445bn and recurring net profit rose 66.75% to RMB 623.5m; the reported nine-month decline reflects RMB 96.7m of contingent-liability expenses booked mainly in the first half and non-recurring gains in the prior-year period. Nine-month operating cash flow was an outflow of RMB 305.7m. Short-term borrowings rose to RMB 1.367bn from RMB 825.0m and notes payable to RMB 1.371bn from RMB 524.9m, which the company attributed to pledged bank-acceptance arrangements; selling expenses rose 31.79% on revenue growth and market development.
First tranche of the long-term incentive plan: 8.978m restricted shares at RMB 6.61 and 5.07m options at RMB 13.21 for 416 people, vesting on recurring-profit growth of 100%, 130% and 170% over 2022 in 2024, 2025 and 2026.
The restricted shares are 0.85% and the options 0.48% of the 1,056.6m shares in issue. Recurring net profit, excluding share-based payment expense, must at least double the 2022 base (RMB 460.9m) in 2024, reach 2.3 times it in 2025 and 2.7 times in 2026; completion between 80% and 100% vests pro rata and below 80% lapses, with individual appraisal applied on top. Independent directors, supervisors and holders of 5% or more are excluded. Half of each vested tranche may not be sold for ten years without company consent.
Guidance: Vesting requires audited recurring net profit growth over 2022 of at least 100% in 2024, 130% in 2025 and 170% in 2026.Reaction (same session, order not established): 002011 −4.2% · SZSE −1.1% · peers −2.1% · 3.1× median volumeSource: cninfo announcement (incentive plan summary), 26 Dec 2023
Large price moves
2
23 Oct 2023 · −6.9% · Residual · index −1.5%, peers −1.9%, left over −5.0%
Against an index move of −1.5% and a peer median of −1.9%, about 5 points are left over; 0.8× median volume. No filing beyond routine notices in the prior three sessions.
27 Oct 2023 · +10.0% · Residual · index +2.1%, peers +2.9%, left over +7.1%
Against an index move of +2.1% and a peer median of +2.9%, about 7 points are left over; 0.9× median volume. Coincided with the filing “关于子公司为母公司担保的进展公告” (release order not established).
23 Nov 2023 · +6.4% · Residual · index +0.8%, peers +2.0%, left over +4.4%
Against an index move of +0.8% and a peer median of +2.0%, about 4 points are left over; 1.3× median volume. No filing beyond routine notices in the prior three sessions.
002011 −8.4%SZSE −1.3%Peer median −2.6%Range RMB 10.07–RMB 13.70Close RMB 12.60
Key developments
25Jan
RMB 12.05Corporate action
Incentive grant made: 8.809m restricted shares at RMB 6.61 to 367 people and 4.99m options at RMB 13.21 to 41 people, grant date 24 January 2024.
Some intended recipients waived 168,800 shares, cutting the restricted-share grant from 8.978m. Registration of both instruments was completed on 23 February 2024.
26 Jan 2024 · −5.8% · Residual · index −1.1%, peers +1.0%, left over −6.8%
Against an index move of −1.1% and a peer median of +1.0%, about 7 points are left over; 1.2× median volume. No filing beyond routine notices in the prior three sessions.
week to 8 Feb 2024 · +14.1% · Residual · index +9.5%, peers +3.6%, left over +10.5%
Weekly window, 2024-02-02 to 2024-02-08: against an index move of +9.5% and a peer median of +3.6%, about 10 points are left over. No filing beyond routine notices inside the window.
week to 1 Mar 2024 · +12.0% · Residual · index +4.0%, peers +1.2%, left over +10.8%
Weekly window, 2024-02-23 to 2024-03-01: against an index move of +4.0% and a peer median of +1.2%, about 11 points are left over. No filing beyond routine notices inside the window.
002011 −22.0%SZSE −5.9%Peer median +6.0%Range RMB 9.77–RMB 12.67Close RMB 9.83
Key developments
19Apr
RMB 11.04Results
FY2023 results: revenue up 11.50% to RMB 11.382bn, net profit down 11.50% to RMB 738.0m, recurring profit up 78.08% to RMB 820.8m; no dividend.
Refrigeration components revenue rose 8.74% to RMB 8.456bn at a 19.44% gross margin, up 2.64 points; refrigeration equipment rose 10.53% to RMB 1.646bn at 24.70%; EV thermal management rose 136.54% to RMB 472.8m. Overseas revenue slipped 1.63% to RMB 1.949bn at a 29.83% margin. Operating cash flow fell 36.00% to RMB 811.8m. Credit and asset impairments of RMB 128.8m cut net profit by RMB 117.3m. Sales to controlling shareholder Gree Electric were RMB 2.413bn in 2023, with a RMB 2.9bn cap set for 2024. The board proposed no distribution because the parent company's undistributed profit was RMB -874.7m even after RMB 533.1m of subsidiary dividends. Net assets rose 21.07% to RMB 4.417bn.
1Q2024: revenue up 7.31% to RMB 2.626bn and net profit up 28.88% to RMB 208.5m.
Recurring net profit rose 13.94% to RMB 199.7m. Operating cash flow turned to an inflow of RMB 67.3m from an outflow of RMB 172.2m. Non-operating expenses fell 87.96%, the prior-year quarter having carried the Tianjin energy-saving contingent liabilities; other income rose 136.81% on VAT super-deductions. Other non-current assets doubled to RMB 296.3m on a land payment.
week to 12 Apr 2024 · −10.5% · Residual · index −3.3%, peers +6.3%, left over −16.7%
Weekly window, 2024-04-03 to 2024-04-12: against an index move of −3.3% and a peer median of +6.3%, about 17 points are left over. No filing beyond routine notices inside the window.
22 May 2024 · +6.1% · Residual · index +0.1%, peers −2.0%, left over +8.1%
Against an index move of +0.1% and a peer median of −2.0%, about 8 points are left over; 3.0× median volume. No filing beyond routine notices in the prior three sessions.
002011 +21.3%SZSE +19.0%Peer median +24.9%Range RMB 9.61–RMB 11.92Close RMB 11.92
Key developments
1Jul
RMB 10.10Corporate action
Acquisition: 62.95% of Shanghai Dachuang Automotive Technology for RMB 215m in cash plus a RMB 30m capital injection, taking the stake to 65.95%.
Dachuang makes OBD electronic-control products and EV thermal-management water-side valves, with plants in Tianjin and Nantong; it reported 2023 revenue of RMB 91.5m and a net loss of RMB 12.5m, and 100% of its equity was valued at RMB 341m by the income approach (RMB 88.2m by the asset approach). The sellers committed to cumulative 2024-2026 revenue of at least RMB 910m and net profit of at least RMB 71m, backed by cash compensation and pledged shares. The company said the deal fills its water-side valve line and raises content per vehicle. Dachuang was consolidated after registration completed on 8 August 2024.
1H2024 profit alert: net profit guided to RMB 444.2m-493.6m, up 35%-50%, on revenue of RMB 6.130bn-6.688bn, up 10%-20%.
Recurring net profit was guided up 5%-15% to RMB 443.2m-485.4m. The company attributed the increase to steady volume growth in refrigeration components; sharply higher volumes in automotive thermal management, electronic expansion valves, microchannel heat exchangers and some special air-conditioning products; rising overseas and commercial sales; and the prior-year period's non-operating expenses from the Tianjin energy-saving legacy. Figures were preliminary and unaudited.
Guidance: 1H2024 net profit RMB 444.2m-493.6m (up 35%-50%) and revenue RMB 6.130bn-6.688bn (up 10%-20%), unaudited.Reaction (same session, order not established): 002011 +7.7% · SZSE +0.3% · peers −1.4% · 2.4× median volumeSource: cninfo announcement (2024 half-year earnings pre-announcement), 5 Jul 2024
28Aug
RMB 10.02Results
1H2024 results: revenue up 13.87% to RMB 6.346bn and net profit up 44.02% to RMB 473.9m; components gross margin down 1.54 points to 18.52%.
Recurring net profit rose 10.23% to RMB 465.3m, inside the July guidance range. Refrigeration components revenue rose 15.74% to RMB 4.974bn; refrigeration equipment rose 2.91% to RMB 704.6m at a 22.16% margin, down 3.09 points; EV thermal management rose 93.22% to RMB 264.5m. Overseas revenue rose 8.91% to RMB 1.102bn at a 27.72% margin, down 2.86 points. Administrative expenses rose 13.46%, attributed to share-based payment; finance costs turned to net income of RMB 11.9m. Operating cash flow was RMB 272.4m against an outflow a year earlier, attributed to more cash collection and note settlement; net assets reached RMB 4.890bn.
Zijin Mining Investment, holder of 8.36%, plans to sell up to 19,177,900 shares (1.80%) within three months after a 15-trading-day notice.
Zijin held 89,069,416 shares acquired by agreement transfer, the second-largest holding after Gree Electric. Sales are by centralised bidding or block trade at market price, for the holder's own operating needs; the company said control is unaffected.
5 Jul 2024 · +7.7% · Residual · index +0.2%, peers −1.4%, left over +9.1%
Against an index move of +0.2% and a peer median of −1.4%, about 9 points are left over; 1.9× median volume. Coincided with the filing “2024年半年度业绩预告” (release order not established).
10 Jul 2024 · +6.2% · Residual · index −0.1%, peers −1.3%, left over +7.5%
Against an index move of −0.1% and a peer median of −1.3%, about 7 points are left over; 2.0× median volume. No filing beyond routine notices in the prior three sessions.
002011 −9.3%SZSE −1.1%Peer median −8.1%Range RMB 10.37–RMB 12.30Close RMB 10.81
Key developments
11Oct
RMB 10.91Board
Chairman Deng Xiaobo resigns; Gree Electric nominates its vice-president Fang Xiangjian as director, with president Li Jianjun acting as chairman meanwhile.
The company attributed the resignation to a change in work assignments; Deng held no shares and leaves all posts. Fang was elected chairman on 28 October 2024 after the EGM and chairs the strategy committee; the legal-representative registration was changed on 26 November 2024.
3Q2024: revenue up 4.09% to RMB 2.990bn but net profit down 17.18% to RMB 174.9m after a RMB 60m bad-debt provision; nine-month net profit up 20.10% to RMB 648.8m.
The quarter's recurring profit fell 18.95% to RMB 163.2m. The company said it individually provided RMB 60m against the consideration and pre-disposal balances left from Zhejiang DunAn Energy-saving's sale of subsidiaries, reducing net profit by that amount; cumulative nine-month credit and asset impairments were RMB 113.9m. Nine-month revenue rose 10.54% to RMB 9.336bn and operating cash flow rose 282.14% to RMB 556.7m. Receivables financing rose 42.17% to RMB 2.550bn on pledged bank acceptances and supply-chain finance instruments.
Director Tan Jianming retires and director Zhang Zhouhu steps down as vice-president and board secretary; president Li Jianjun acts as board secretary.
Zhang keeps his board seat and his 180,000 restricted shares and 180,000 options under the 2023 plan. Gree Electric nominated vice-president Feng Zhongbo, a former chairman of the company, to the vacant seat on 10 February 2025, and Wu Qingqing, previously of Gree Electric's securities office, was appointed board secretary on 28 March 2025 alongside Lou Jiayang as vice-president.
21 Jan 2025 · +6.5% · Residual · index +0.5%, peers −0.3%, left over +6.8%
Against an index move of +0.5% and a peer median of −0.3%, about 7 points are left over; 2.4× median volume. Coincided with the filing “关于股东减持计划实施期限届满暨实施结果的公告” (release order not established).
week to 24 Jan 2025 · +9.3% · Residual · index +1.3%, peers −2.9%, left over +12.2%
Weekly window, 2025-01-17 to 2025-01-24: against an index move of +1.3% and a peer median of −2.9%, about 12 points are left over. The week included the filing “关于职工代表监事辞职及补选职工代表监事的公告” (2025-01-22).
week to 21 Feb 2025 · +11.2% · Residual · index +2.2%, peers +1.1%, left over +10.1%
Weekly window, 2025-02-14 to 2025-02-21: against an index move of +2.2% and a peer median of +1.1%, about 10 points are left over. No filing beyond routine notices inside the window.
18 Mar 2025 · +5.0% · Residual · index +0.5%, peers +0.4%, left over +4.6%
Against an index move of +0.5% and a peer median of +0.4%, about 5 points are left over; 2.2× median volume. No filing beyond routine notices in the prior three sessions.
002011 −4.2%SZSE −0.4%Peer median −9.6%Range RMB 10.57–RMB 12.34Close RMB 11.60
Key developments
18Apr
RMB 11.64Results
FY2024 results: revenue up 11.39% to RMB 12.678bn and net profit up 41.58% to RMB 1.045bn, recurring profit up 13.16% to RMB 928.8m; still no dividend.
Refrigeration components revenue rose 13.67% to RMB 9.612bn at an 18.60% gross margin, down 0.84 points; refrigeration equipment fell 9.16% to RMB 1.496bn at 21.07%, down 2.71 points; EV thermal management rose 71.66% to RMB 811.6m. Overseas revenue rose 17.06% to RMB 2.281bn at a 26.51% margin, down 3.28 points. Non-recurring gains of RMB 116.1m included a RMB 99.7m reversal of individually tested receivable provisions, and fourth-quarter net profit was RMB 396.1m; goodwill of RMB 12.5m was impaired. Operating cash flow rose 42.96% to RMB 1.161bn and net assets rose 24.72% to RMB 5.509bn. The board again proposed no distribution because the parent's undistributed profit was RMB -345.5m; no cash dividend had been paid in the last three years.
1Q2025: revenue up 15.05% to RMB 3.021bn and net profit up 4.34% to RMB 217.5m; operating cash flow up 118.37% to RMB 147.0m.
Recurring net profit rose 5.44% to RMB 210.6m. Taxes and surcharges rose 97.47% as the prior-year quarter carried a property-tax refund. Total assets fell 1.93% to RMB 11.919bn and net assets rose 3.89% to RMB 5.724bn.
28 Apr 2025 · −7.4% · Residual · index −0.6%, peers +0.1%, left over −7.6%
Against an index move of −0.6% and a peer median of +0.1%, about 8 points are left over; 1.9× median volume. No filing beyond routine notices in the prior three sessions.
002011 +22.7%SZSE +29.3%Peer median +6.5%Range RMB 11.41–RMB 14.99Close RMB 14.23
Key developments
30Jul
RMB 11.61Corporate action
2023 incentive plan: first tranche vests after FY2024 recurring profit of RMB 954m (before share-based pay) rose 106.93% over 2022; 3.074m shares unlock while 834,000 shares and 371,100 options lapse.
Audited FY2024 recurring net profit was RMB 929m, or RMB 954m before RMB 25m of share-based payment expense, clearing the 100% growth hurdle. 334 people may unlock 3,073,600 restricted shares (0.29% of share capital). The company will repurchase and cancel 834,000 restricted shares at the RMB 6.61 grant price plus interest from 23 leavers, two retirees, a supervisor and 178 people whose individual appraisal scored below 100%, and cancel 371,100 options from two leavers and 19 people with partial scores.
1H2025 results: revenue up 6.05% to RMB 6.729bn and net profit up 12.94% to RMB 535.2m; refrigeration equipment revenue down 31.43%.
Recurring net profit rose 11.04% to RMB 516.7m. Refrigeration components revenue rose 8.80% to RMB 5.412bn at a 17.78% gross margin, down 0.66 points; refrigeration equipment fell 31.43% to RMB 483.1m at 18.86%, down 2.69 points; EV thermal management rose 81.84% to RMB 481.0m, 7.15% of revenue. Overseas revenue rose 13.23% to RMB 1.248bn at a 27.63% margin. Administrative expenses fell 17.01%; finance costs swung to RMB 0.5m from net income of RMB 11.9m on exchange losses. Operating cash flow rose 17.34% to RMB 319.6m and a RMB 365.7m financing outflow was attributed to loan repayments. Second-quarter revenue was RMB 3.708bn, down 0.3%, with net profit up 19.7% to RMB 317.7m (computed).
Zijin Mining Investment, holder of 7.36%, plans to sell up to 31,963,085 shares (3%) within three months after a 15-trading-day notice.
Zijin held 78,468,916 shares; sales by centralised bidding or block trade at market price, for its own operating needs. The ceiling is larger than the 1.80% plan of September 2024.
Capex: a smart-manufacturing headquarters base in Zhuji, Zhejiang, with planned total investment of about RMB 5bn over two phases, funded from own and raised funds.
The agreement with the Zhuji Economic Development Zone and Zhuji New City Investment covers a first phase for refrigeration core components and a second for EV thermal-management parts, each with R&D, manufacturing and sales facilities. The company committed to tax yield of RMB 300,000 per mu a year for three years and rooftop solar on new plants, and said the investment figure is an estimate to be phased with construction, with limited near-term financial impact and a funding risk if self-raised money is late. Shareholders approved the project on 26 September 2025.
Second incentive tranche: 10.378m restricted shares at RMB 7.05 and 4.77m options at RMB 14.10 for 415 people, vesting on recurring-profit growth of 14.10%, 34.02% and 51.78% over 2024 in 2025, 2026 and 2027.
The shares are 0.97% and the options 0.45% of the 1,065.4m shares in issue. The company said the 2025 and 2026 hurdles are the same as the 2023 plan's; on the FY2024 base of RMB 928.8m they imply recurring net profit of RMB 1.060bn, RMB 1.245bn and RMB 1.410bn (computed). Completion between 80% and 100% vests pro rata.
Guidance: Vesting requires audited recurring net profit growth over 2024 of at least 14.10% in 2025, 34.02% in 2026 and 51.78% in 2027.Reaction (same session, order not established): 002011 +3.9% · SZSE +2.0% · peers +0.5% · 2.1× median volumeSource: cninfo announcement (2025 incentive plan draft), 27 Sep 2025
Large price moves
22
15 Aug 2025 · +10.0% · Residual · index +1.6%, peers +1.2%, left over +8.7%
Against an index move of +1.6% and a peer median of +1.2%, about 9 points are left over; 6.2× median volume. No filing beyond routine notices in the prior three sessions.
18 Sep 2025 · +6.8% · Residual · index −1.1%, peers −0.9%, left over +7.7%
Against an index move of −1.1% and a peer median of −0.9%, about 8 points are left over; 8.0× median volume. No filing beyond routine notices in the prior three sessions.
22 Sep 2025 · +8.3% · Residual · index +0.7%, peers −0.9%, left over +9.2%
Against an index move of +0.7% and a peer median of −0.9%, about 9 points are left over; 5.4× median volume. No filing beyond routine notices in the prior three sessions.
002011 −10.9%SZSE −0.0%Peer median −0.5%Range RMB 12.18–RMB 14.72Close RMB 12.68
Key developments
9Oct
RMB 14.72Capacity
Zhuji base breaks ground: phase one on about 300 mu, due to complete in 2027, is designed for 330m sets a year of refrigeration components; phase two on about 100 mu for 100m sets of EV thermal parts.
Land and construction permits for phase one have been obtained; the second-phase plot is to be confirmed as the project progresses. The company said the build period and capacities are its own estimates and the project is at the construction stage.
3Q2025: revenue flat at RMB 2.993bn (up 0.11%) while net profit rose 33.43% to RMB 233.3m; nine-month operating cash flow up 31.50% to RMB 732.1m.
Recurring net profit rose 35.14% to RMB 220.5m against a prior-year quarter that carried the RMB 60m energy-saving provision; nine-month credit impairment losses fell to RMB 2.9m from RMB 113.6m. Nine-month revenue rose 4.15% to RMB 9.723bn and net profit 18.46% to RMB 768.5m. Non-current liabilities due within a year fell 92.84% to RMB 47.7m on loan repayments; new borrowings were RMB 808m against RMB 1.474bn a year earlier and the financing outflow was RMB 632.0m.
Second-tranche grant made: 10.075m restricted shares at RMB 7.05 to 365 people and 4.77m options at RMB 14.10 to 44 people, grant date 25 November 2025.
Twenty-four intended recipients waived some or all of their shares, cutting the restricted-share grant from 10.378m. Registration was completed on 16 December 2025.
Zijin sold 10,499,300 shares (0.99%) at an average RMB 12.60 between 15 September and 12 December 2025, cutting its stake to 6.38%.
Sales were by centralised bidding within RMB 12.31-15.10, against a plan ceiling of 31,963,085 shares; Zijin retains 67,969,616 shares. The stake crossed below 7% on 8 December 2025.
No session cleared the large-move threshold this quarter.
Q1 2026
5 Jan 2026 – 31 Mar 2026
002011 −7.3%SZSE −0.3%Peer median −13.2%Range RMB 11.75–RMB 13.55Close RMB 11.75
Key developments
8Jan
RMB 12.94Corporate action
Lock-up expiry: 139,414,802 shares (12.97%) that Gree Electric bought in the 2023 private placement at RMB 5.81 become tradable on 9 January 2026.
The placement raised RMB 810.0m and listed on 6 January 2023 with a 36-month lock-up for the controlling shareholder. The notice records Gree's commitments as fulfilled.
No session cleared the large-move threshold this quarter.
Q2 2026
1 Apr 2026 – 30 Jun 2026
002011 −9.7%SZSE +20.2%Peer median +3.1%Range RMB 9.98–RMB 12.91Close RMB 10.61
Key developments
29Apr
RMB 11.86Results
FY2025 results: revenue up 2.81% to RMB 13.035bn, net profit up 3.16% to RMB 1.078bn, recurring profit up 6.82% to RMB 992.2m; first cash dividend after three years without one, RMB 0.10 a share.
Refrigeration components revenue rose 2.35% to RMB 9.838bn at an 18.67% gross margin; refrigeration equipment fell 22.24% to RMB 1.163bn; EV thermal management rose 52.04% to RMB 1.234bn, 9.47% of revenue. Overseas revenue fell 4.86% to RMB 2.170bn at a 25.78% margin, down 0.73 points. Fourth-quarter revenue was RMB 3.312bn and net profit RMB 309.4m, down 21.9% (computed) against a prior-year quarter with a RMB 99.7m provision reversal. Operating cash flow rose 24.09% to RMB 1.440bn; net assets rose 21.00% to RMB 6.666bn. With the parent's undistributed profit turned positive at RMB 155.0m, the board proposed RMB 1.00 per 10 shares, RMB 107.5m in total or 9.97% of net profit.
1Q2026: revenue up 1.17% to RMB 3.057bn and net profit down 9.86% to RMB 196.1m; inventories up 37.84% to RMB 1.840bn.
Recurring net profit fell 6.32% to RMB 197.3m. The company attributed the inventory build to stocking for the peak production season; other income fell 40.82% on lower government grants. Operating cash flow rose 39.45% to RMB 205.0m on higher cash collections while cash paid for purchases rose 48.11%. Diluted EPS was RMB 0.18 against basic RMB 0.19.
Financial services agreement with Gree Group Finance renewed for three years: deposits capped at a RMB 300m daily balance and a RMB 1.5bn credit line.
The related-party deposit balance was RMB 298.0m with no loans drawn at the date of the notice; deposit rates are to be no lower than the major state banks' and loan rates no higher than other lenders'. The agreement needs shareholder approval with Gree abstaining. Gree Group Finance reported total assets of RMB 46.36bn and net profit of RMB 205.1m for 2025.
2023 incentive plan: FY2025 recurring profit of RMB 1.003bn (before share-based pay) reached 94.6% of the 130%-growth hurdle, so 1.989m shares vest pro rata while 492,479 shares and 300,534 options lapse.
Audited FY2025 recurring net profit was RMB 992m, or RMB 1.003bn before RMB 11m of share-based payment, against a hurdle of 2.3 times the 2022 base (RMB 1.060bn, computed); between 80% and 100%, each holder's unlock is scaled by the 94.6% completion rate, so 297 people lose 202,079 shares to the shortfall, with leavers, demotions and a supervisor accounting for the rest. Repurchase is at RMB 6.61 plus interest. Separately, 1,744,866 options from the first exercise window expired unexercised and were cancelled in February 2026.
week to 5 Jun 2026 · −9.1% · Residual · index −1.7%, peers +2.5%, left over −11.7%
Weekly window, 2026-05-29 to 2026-06-05: against an index move of −1.7% and a peer median of +2.5%, about 12 points are left over. No filing beyond routine notices inside the window.
002011 −6.0%SZSE −13.0%Peer median −4.1%Range RMB 9.87–RMB 10.93Close RMB 9.88
Key developments
11Aug
RMB 10.27Dividend
Ex-dividend: FY2025 cash dividend of RMB 0.10 per share (RMB 1.00 per 10 shares), RMB 107.4m in total.
Approved at the AGM of 25 June 2026; record date 10 August 2026 and payment from 11 August 2026 on 1,074,477,339 shares after the cancellation of 199,800 restricted shares. The chart's return series is adjusted for it, so the ex-date step is not counted as a move.
No session cleared the large-move threshold this quarter.
Prices are Yahoo Finance daily closes for 002011.SZ (returns on the dividend-adjusted series) from 22 Aug 2023 to 21 Aug 2026, benchmarked to the SZSE Component Index (399001) with Sanhua Intelligent Controls (002050), Hisense Home Appliances (000921) and Vatti (002035) as peers; the filing tape is the cninfo announcement list for the same window, 348 items, retrieved 23 Aug 2026. cninfo records the publication date only; SZSE filings are published after the close, so every filing is read against the next session.
The full move register — every large move and its market and sector controls
Every threshold-detected move in the window with its controls, dispositioned in the price-driver register; rows with a written note carry a numbered pin on the chart.
#
Session
002011
SZSE
Peers
Left over
Control result
What the evidence supports
1
24 Aug 2023
−6.4%
+1.0%
+1.8%
−8.2%
Residual
Against an index move of +1.0% and a peer median of +1.8%, about 8 points are left over; 1.9× median volume. Coincided with the filing “关于开展外汇套期保值业务的可行性分析报告” (release order not established).Sanhua +1.8 · HisenseHA +2.0 · Vatti +0.9
2
23 Oct 2023
−6.9%
−1.5%
−1.9%
−5.0%
Residual
Against an index move of −1.5% and a peer median of −1.9%, about 5 points are left over; 0.8× median volume. No filing beyond routine notices in the prior three sessions.Sanhua −1.7 · HisenseHA −1.9 · Vatti −2.9
3
27 Oct 2023
+10.0%
+2.1%
+2.9%
+7.1%
Residual
Against an index move of +2.1% and a peer median of +2.9%, about 7 points are left over; 0.9× median volume. Coincided with the filing “关于子公司为母公司担保的进展公告” (release order not established).Sanhua −1.0 · HisenseHA +3.4 · Vatti +2.9
4
23 Nov 2023
+6.4%
+0.8%
+2.0%
+4.4%
Residual
Against an index move of +0.8% and a peer median of +2.0%, about 4 points are left over; 1.3× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +2.8 · HisenseHA +2.0 · Vatti +1.1
5
26 Jan 2024
−5.8%
−1.1%
+1.0%
−6.8%
Residual
Against an index move of −1.1% and a peer median of +1.0%, about 7 points are left over; 1.2× median volume. No filing beyond routine notices in the prior three sessions.Sanhua −4.1 · HisenseHA +1.0 · Vatti +1.4
6
6 Feb 2024
+8.7%
+6.2%
+5.9%
+2.8%
Market-wide
In line with the market: against an index move of +6.2% and a peer median of +5.9%, about 3 points are left over.Sanhua +8.1 · HisenseHA +5.9 · Vatti +4.4
7
week to 8 Feb 2024
+14.1%
+9.5%
+3.6%
+10.5%
Residual
Weekly window, 2024-02-02 to 2024-02-08: against an index move of +9.5% and a peer median of +3.6%, about 10 points are left over. No filing beyond routine notices inside the window.Sanhua +10.9 · HisenseHA +3.6 · Vatti +2.8
8
week to 1 Mar 2024
+12.0%
+4.0%
+1.2%
+10.8%
Residual
Weekly window, 2024-02-23 to 2024-03-01: against an index move of +4.0% and a peer median of +1.2%, about 11 points are left over. No filing beyond routine notices inside the window.Sanhua +1.2 · HisenseHA +13.7 · Vatti +1.1
9
week to 12 Apr 2024
−10.5%
−3.3%
+6.3%
−16.7%
Residual
Weekly window, 2024-04-03 to 2024-04-12: against an index move of −3.3% and a peer median of +6.3%, about 17 points are left over. No filing beyond routine notices inside the window.Sanhua −6.5 · HisenseHA +7.2 · Vatti +6.3
10
22 May 2024
+6.1%
+0.1%
−2.0%
+8.1%
Residual
Against an index move of +0.1% and a peer median of −2.0%, about 8 points are left over; 3.0× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +2.5 · HisenseHA −2.0 · Vatti −2.6
11
5 Jul 2024
+7.7%
+0.2%
−1.4%
+9.1%
Residual
Against an index move of +0.2% and a peer median of −1.4%, about 9 points are left over; 1.9× median volume. Coincided with the filing “2024年半年度业绩预告” (release order not established).Sanhua −5.0 · HisenseHA −1.4 · Vatti +1.9
12
10 Jul 2024
+6.2%
−0.1%
−1.3%
+7.5%
Residual
Against an index move of −0.1% and a peer median of −1.3%, about 7 points are left over; 2.0× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +1.0 · HisenseHA −2.1 · Vatti −1.3
13
30 Sep 2024
+8.7%
+10.7%
+9.7%
−1.0%
Sector-wide
Tracked the sector: against an index move of +10.7% and a peer median of +9.7%, about 1 points are left over.Sanhua +10.0 · HisenseHA +9.7 · Vatti +8.4
14
9 Oct 2024
−9.1%
−8.2%
−8.8%
−0.3%
Sector-wide
Tracked the sector: against an index move of −8.2% and a peer median of −8.8%, about 0 points are left over.Sanhua −3.0 · HisenseHA −10.0 · Vatti −8.8
15
21 Jan 2025
+6.5%
+0.5%
−0.3%
+6.8%
Residual
Against an index move of +0.5% and a peer median of −0.3%, about 7 points are left over; 2.4× median volume. Coincided with the filing “关于股东减持计划实施期限届满暨实施结果的公告” (release order not established).Sanhua +6.3 · HisenseHA −0.3 · Vatti −3.7
16
week to 24 Jan 2025
+9.3%
+1.3%
−2.9%
+12.2%
Residual
Weekly window, 2025-01-17 to 2025-01-24: against an index move of +1.3% and a peer median of −2.9%, about 12 points are left over. The week included the filing “关于职工代表监事辞职及补选职工代表监事的公告” (2025-01-22).Sanhua +10.9 · HisenseHA −2.9 · Vatti −4.6
17
21 Feb 2025
+5.2%
+1.8%
−0.4%
+5.6%
Market-wide
In line with the market: against an index move of +1.8% and a peer median of −0.4%, about 6 points are left over.Sanhua +0.9 · HisenseHA −1.0 · Vatti −0.4
18
week to 21 Feb 2025
+11.2%
+2.2%
+1.1%
+10.1%
Residual
Weekly window, 2025-02-14 to 2025-02-21: against an index move of +2.2% and a peer median of +1.1%, about 10 points are left over. No filing beyond routine notices inside the window.Sanhua +7.4 · HisenseHA −7.4 · Vatti +1.1
19
18 Mar 2025
+5.0%
+0.5%
+0.4%
+4.6%
Residual
Against an index move of +0.5% and a peer median of +0.4%, about 5 points are left over; 2.2× median volume. No filing beyond routine notices in the prior three sessions.Sanhua −1.2 · HisenseHA +0.4 · Vatti +1.0
20
7 Apr 2025
−10.0%
−9.7%
−10.0%
+0.0%
Sector-wide
Tracked the sector: against an index move of −9.7% and a peer median of −10.0%, about 0 points are left over.Sanhua −10.0 · HisenseHA −9.0 · Vatti −10.0
21
28 Apr 2025
−7.4%
−0.6%
+0.1%
−7.6%
Residual
Against an index move of −0.6% and a peer median of +0.1%, about 8 points are left over; 1.9× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +0.4 · HisenseHA −1.3 · Vatti +0.1
22
15 Aug 2025
+10.0%
+1.6%
+1.2%
+8.7%
Residual
Against an index move of +1.6% and a peer median of +1.2%, about 9 points are left over; 6.2× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +5.0 · HisenseHA +0.7 · Vatti +1.2
23
18 Sep 2025
+6.8%
−1.1%
−0.9%
+7.7%
Residual
Against an index move of −1.1% and a peer median of −0.9%, about 8 points are left over; 8.0× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +8.7 · HisenseHA −0.9 · Vatti −1.4
24
22 Sep 2025
+8.3%
+0.7%
−0.9%
+9.2%
Residual
Against an index move of +0.7% and a peer median of −0.9%, about 9 points are left over; 5.4× median volume. No filing beyond routine notices in the prior three sessions.Sanhua +3.2 · HisenseHA −1.3 · Vatti −0.9
25
week to 5 Jun 2026
−9.1%
−1.7%
+2.5%
−11.7%
Residual
Weekly window, 2026-05-29 to 2026-06-05: against an index move of −1.7% and a peer median of +2.5%, about 12 points are left over. No filing beyond routine notices inside the window.Sanhua +2.5 · HisenseHA +8.4 · Vatti −1.4
26
26 Jun 2026
−5.1%
−3.4%
−3.4%
−1.7%
Market-wide
In line with the market: against an index move of −3.4% and a peer median of −3.4%, about 2 points are left over.Sanhua −5.6 · HisenseHA −3.4 · Vatti −2.0
Limitations bound every row above. The tape is the complete cninfo (巨潮资讯) announcement list for 002011 over 22 Aug 2023 to 21 Aug 2026, 348 filings, which is the primary disclosure venue for a Shenzhen-listed company and complete for statutory filings; cninfo stamps each filing with its disclosure date rather than a broadcast time, and filings are posted after the previous session's close, so the reacting session is the stamped date, or the next trading day when that date falls on a weekend. Exchange interactive-platform Q&A (互动易), the annual results briefings, media reports, broker notes and block-trade prints were not examined, so moves with no filing beside them are left unexplained rather than attributed. The issuer is the only entity with a separate disclosure stream in the pack's `research/entity-tape-register.json`; subsidiaries (DunAn Mechatronics, Shanghai Dachuang) and the controlling shareholder Gree Electric's own filings were not enumerated. The peer set is three companies (Sanhua, Hisense Home Appliances, Vatti) and their dispersion is wide on several episode days (week to 1 Mar 2024: Hisense +13.7% against Sanhua +1.2%), so the peer median is a coarse sector control.
10 · Primary sources
Where the primary sources are filed.CNINFO disclosure index for 002011 (the official Shenzhen filing archive). Exchange portals re-file and purge documents over time; the text above cites each document by name and date so it can be found again. Tables on this page as data:JSON · CSV — the page’s own as-filed and recomputed tables, cell for cell, with their section and caption.
1H2026 interim report - income statement, balance sheet, cash flow, product mix and management discussion.
No proprietary rating, fair value, price target, expected return, credit outlook or recommendation is published here. The 2026 interim report is incorporated; next decision update follows a complete integrated rerun or another material announcement.
What you can watch yourself
Every other test on this page waits for the company to file. These do not. Each row is a series you can look up yourself, free, today — with its latest recorded value and date, source, and limitations. Market-price context is not a company-specific operating trigger.
In the LME Closing Prices table, read Copper in the 3-month column, in USD per metric tonne. Use the Data valid for date, not the page date or the separate copper-page headline. London Metal Exchange
Last recorded
14,618 US$/t, 2026-09-23
Threshold status
No calibrated operating threshold; No verified historical comparison retained.
How often to look
weekly (the series prints daily)
What it points to. Valves and fittings are copper and brass, so the metal price moves the input cost of the core component line.
Direction only — this pack does not carry a coefficient from this series to reported earnings.
What it cannot tell you. The exchange closing price is market context, not the company's purchase cost. Procurement timing, inventories, hedges, product mix and customer pass-through can separate it from reported margins. The 10 September 2026 correction withdraws the former watch/alert bands: their sources were not verified on a comparable benchmark, and no company-specific cost threshold was established. Check the next margin disclosure and management's explanation before inferring an earnings effect.
Settled by the next quarterly report, due 2026-10-31. Lead time: depends on procurement, inventory and customer pricing terms.
CAAM's monthly release, published around the 10th-12th; read NEV production, not sales. China Association of Automobile Manufacturers, reported by CnEVPost
Last recorded
1,576 k units/month, 2026-07-31
What the reading assumes
1,385 k units/month (monthly average of 2025 full-year production of 16.626m units, 2025)
Watch / alert
1,385 and 1,100 k units/month, on a move below — currently at or better than the level the reading assumed
How often to look
monthly (the series prints monthly)
What it points to. The thermal-management line supplies valves and assemblies into vehicle cooling loops, so national NEV output points to the direction of that segment's volumes.
Direction only — this pack does not carry a coefficient from this series to reported earnings.
What it cannot tell you. This is national NEV output across every maker. A components supplier's own volumes depend on which platforms it is designed into, and a supplier can lose content on a winning platform while national output rises. It also says nothing about price: NEV component tenders in China have repriced downward through periods of rising volume.
Settled by the next quarterly report, due 2026-10-31. Lead time: one to two quarters from build to supplier revenue.
Watchlist reviewed on 2026-09-24; each observation has its own date above. This watchlist date does not change the company research cutoff. A series moving past a level is a reason to re-read the case, not a recommendation. The same series across every company covered: what you can watch.
Notes and sources
9 · Open questions
What portion of automotive thermal growth came from acquisition carryover, new programme launches and underlying volume?
What are the automotive thermal contribution margin, utilisation and returns on incremental capex?
How much of the 1H inventory and receivables build is backed by firm customer schedules, and what is its ageing?
Which external facilities are committed, what covenants apply, and what headroom remains?
How much cash is legally available to the listed parent and what restrictions apply to transfers?
What is the expected maximum use of the approved guarantee programme?
Download
A print-ready PDF of this page, for reading away from the screen: Zhejiang DunAn Artificial Environment evidence library (PDF). It carries the same content as this page — what the company is, the eleven-year balance-sheet repair, the segment mix, FY2025 cash conversion, the first half of 2026, debt, security and guarantees, group finance-company exposure, the five-year record, FY2025 as filed, control, the share price and open questions — and the same omissions: no rating, no fair value, no forecast.
Reader questions & corrections
Ask about this company, challenge a source or suggest a factual correction. Only selected questions that SMID Research has reviewed and answered are published.
Submissions are private by default. Your email is encrypted and never published. Please do not send confidential or inside information, allegations about individuals, promotions, or requests for personalised investment advice.
Behind the lockA complete private working pack exists beyond this page: integrated initiation PDF, standalone credit initiation, formula-linked model, editable deck, source library and review artifacts. It is maintained for the author’s own records—not published and not available for sharing.
These bounded retrospective corrections clarify specific published facts or calculations. They retain each report's existing research cutoff and do not represent a full refresh or a finding that all possible issues are resolved.
Zhejiang DunAn Artificial Environment Co., Ltd.
Verified Fact. FY2025 automotive thermal-management gross margin is derivable as 23.3824% from CNY1,234,029,443.63 revenue less CNY945,483,138.42 cost, divided by revenue. Sources: Source. Limitation: This is gross margin, not EBIT, cash conversion, ROIC or a return on incremental capital.
Transcripts
Find available event transcripts in the transcript library.